
Branch Launches New High Yield Savings Feature
Source: PR Newswire
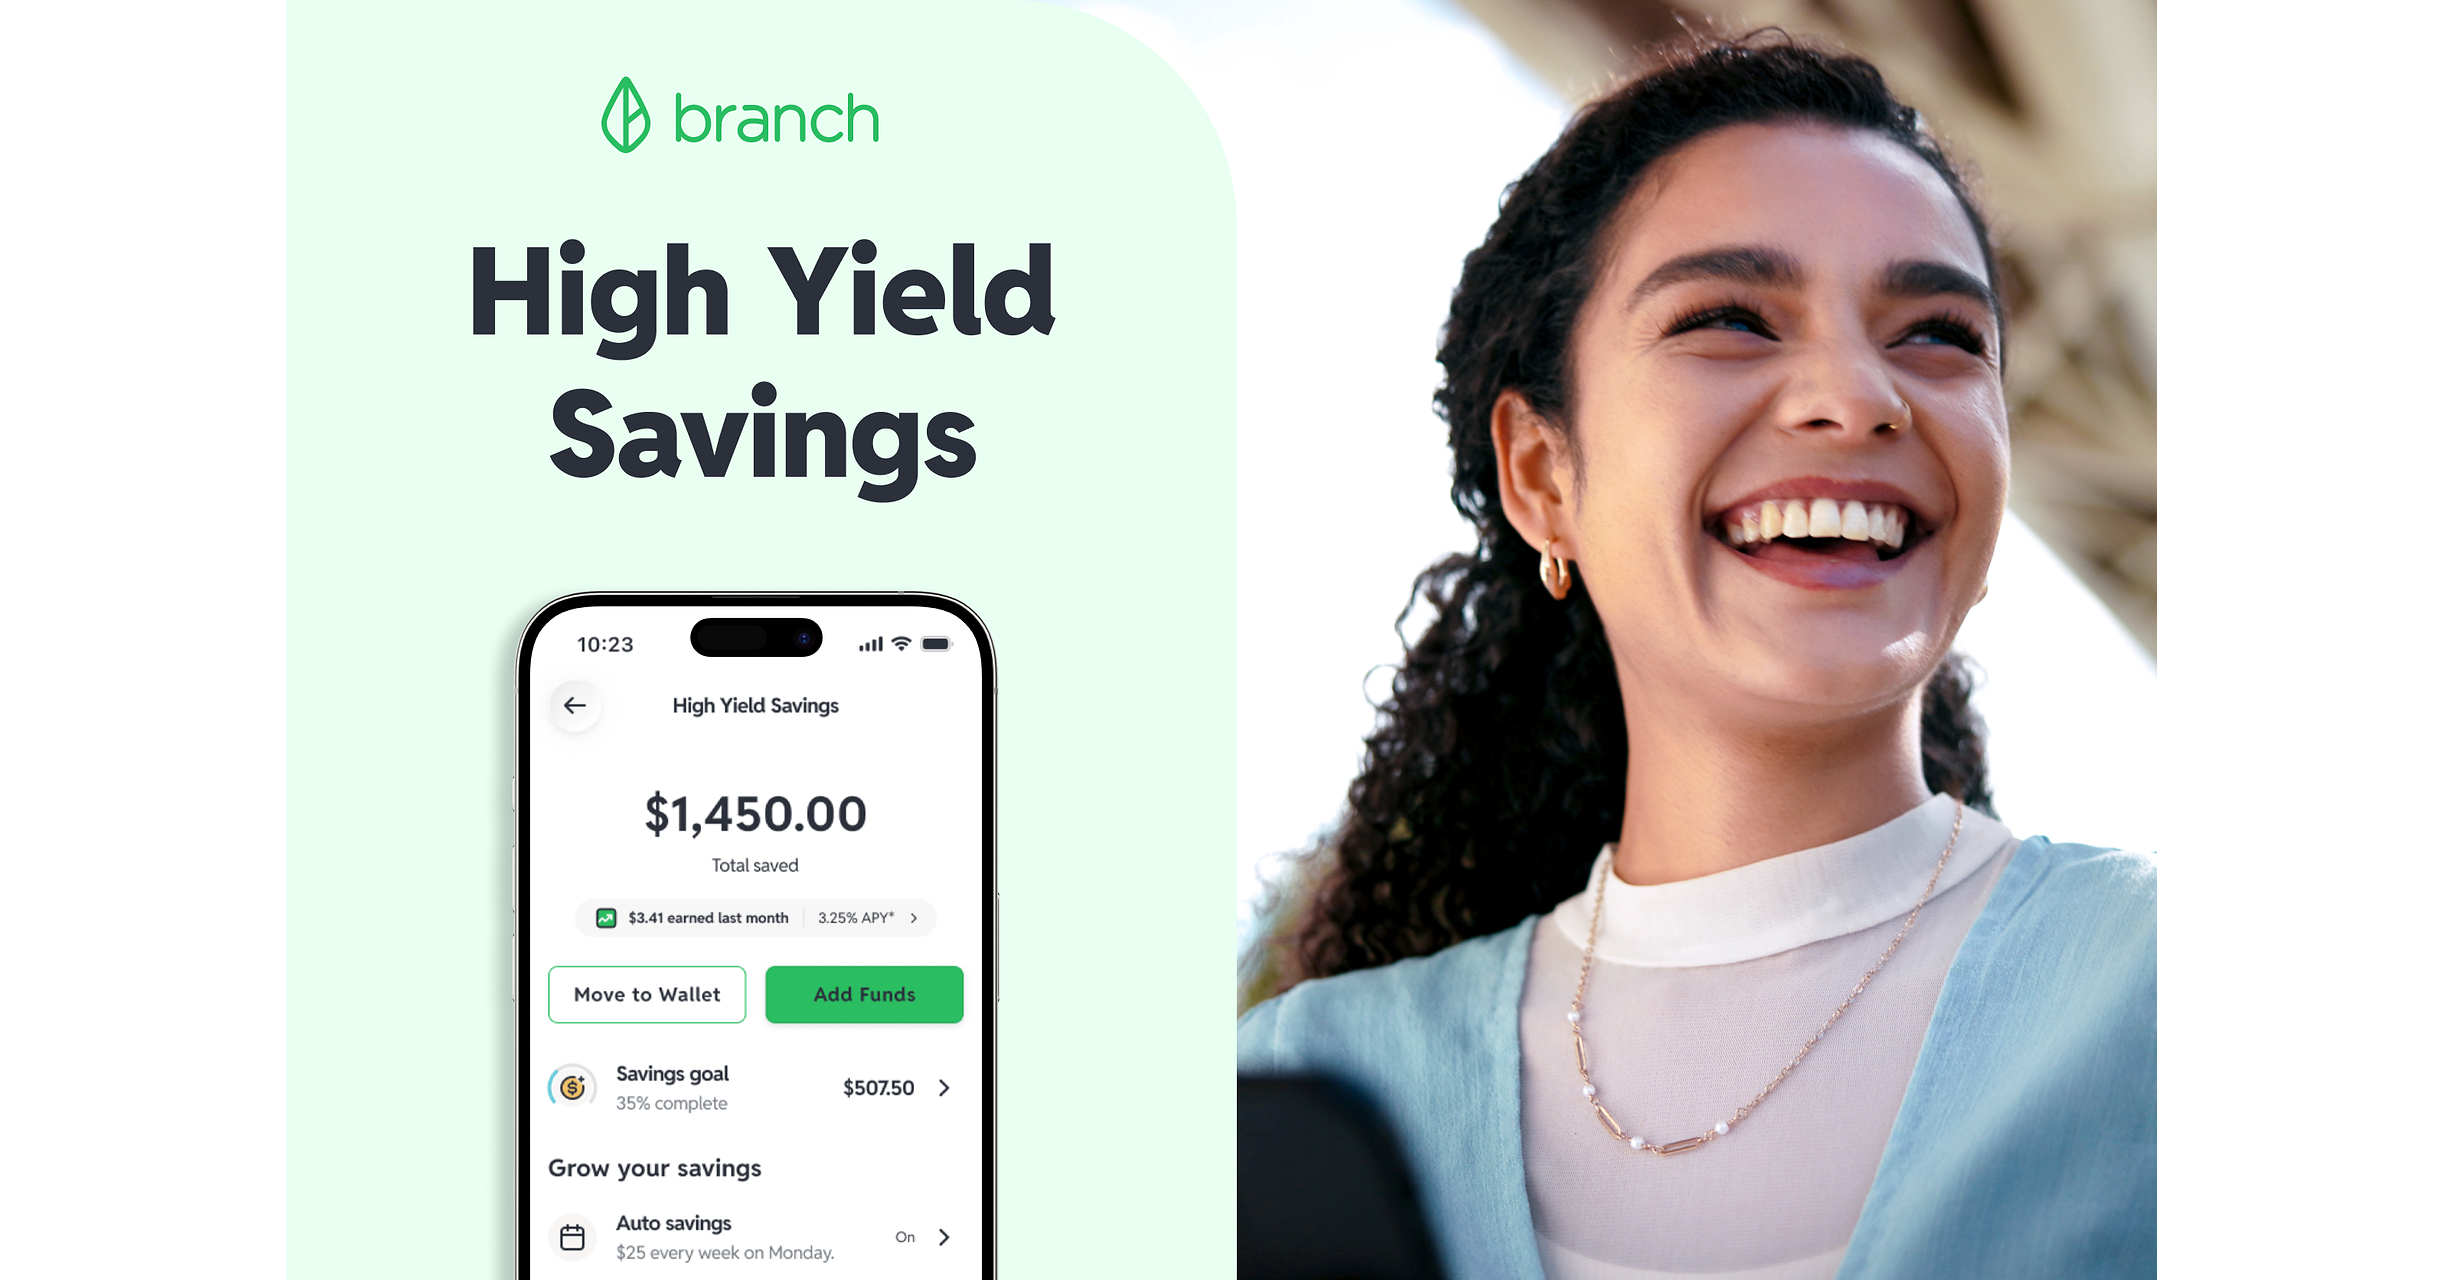
Branch launched a high-yield savings feature for Uber Pro Card holders, offering up to 3.25% variable APY for users maintaining an average daily balance of at least $500. The no-fee product supports automated contributions and flexible transfers, targeting variable-income drivers and couriers who need both liquidity and savings access. The service will initially roll out through Uber before expanding to the Branch App and other Branch-powered platforms.
Analysis
For UBER, the economic value is primarily retention and payment-wallet consolidation rather than a near-term revenue event. A driver who keeps both operating cash and savings inside the Uber-linked ecosystem is less likely to switch primary payout rails or multi-home aggressively; this can improve driver liquidity, engagement and ultimately marketplace reliability. The benefit is most relevant over 6-18 months if the product lifts card activation, direct-deposit balances and driver tenure, but it is unlikely to move consensus bookings, EBITDA or FCF estimates in the next two quarters.
The key monetization variable is deposit behavior, not the advertised yield. If balances scale, Branch and its sponsor-bank partner gain lower-cost, stickier funding while UBER gains a more defensible financial-services surface; however, the interest expense associated with the yield can exceed interchange economics unless average balances and card spend rise together. This places competitive pressure at the margin on Block's Cash App, PayPal/Venmo and gig-worker fintech offerings, but UBER's closed-loop earnings relationship provides a lower customer-acquisition-cost channel than consumer fintech peers.
MA has limited direct exposure: incremental debit transaction volume is economically immaterial at its scale, while the card network does not capture the deposit spread. The contrarian point is that investors may over-credit this type of launch as a fintech profit pool; it is better viewed as a retention feature until disclosures show adoption, average balances, payment volume, or a measurable reduction in driver churn. A falling short-term-rate environment over the next 12 months would compress product differentiation and may force higher promotional yields, reducing any embedded-finance margin pool.
Near-term catalyst risk is low, making this unsuitable as a standalone event trade. Reassess following UBER's next two earnings releases for commentary on Uber Pro Card penetration, driver incentives and engagement; evidence that financial products lower incentive spend or improve driver supply elasticity would create a more material EBITDA upside case.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone UBER trade on this launch; maintain existing core exposure only. Treat driver-card adoption, average balances and incentive-spend efficiency as a 6-12 month monitoring catalyst rather than underwriting near-term estimate revisions.
- For UBER longs, set a thesis-validation alert around the next two quarterly reports: a disclosed increase in card penetration accompanied by lower driver acquisition/incentive costs would support adding exposure; unchanged incentives and no engagement disclosure would falsify the retention-monetization premise.
- Do not add MA on this news. The relevant read-through is only cumulative incremental debit payment volume; absent evidence of broad platform expansion, the revenue contribution is below a meaningful threshold for MA's earnings.
- Watch SQ and PYPL as relative losers only if UBER demonstrates measurable wallet share capture among gig workers over 1-3 months. Without independent adoption data, a short or pair trade would be premature and vulnerable to broader consumer-fintech beta.
More News
- Airtel Money plans one of London’s largest IPOs in years (Sept 23)
- Visa and Mastercard handle nearly half of Europe’s card payments. The digital euro aims to change that
- AI is consuming human knowledge. It should learn how to pay for it
- AI’s biggest players promise to police themselves at the White House
- Lyft will pay $272.5 million to settle California driver wage theft claims
- Temasek comfortable with current AI spending levels, executive says