
Aspen Dental Opens New Practice in Merced, Bringing Comprehensive Dental Care to a Growing Corner of the San Joaquin Valley
Source: PR Newswire
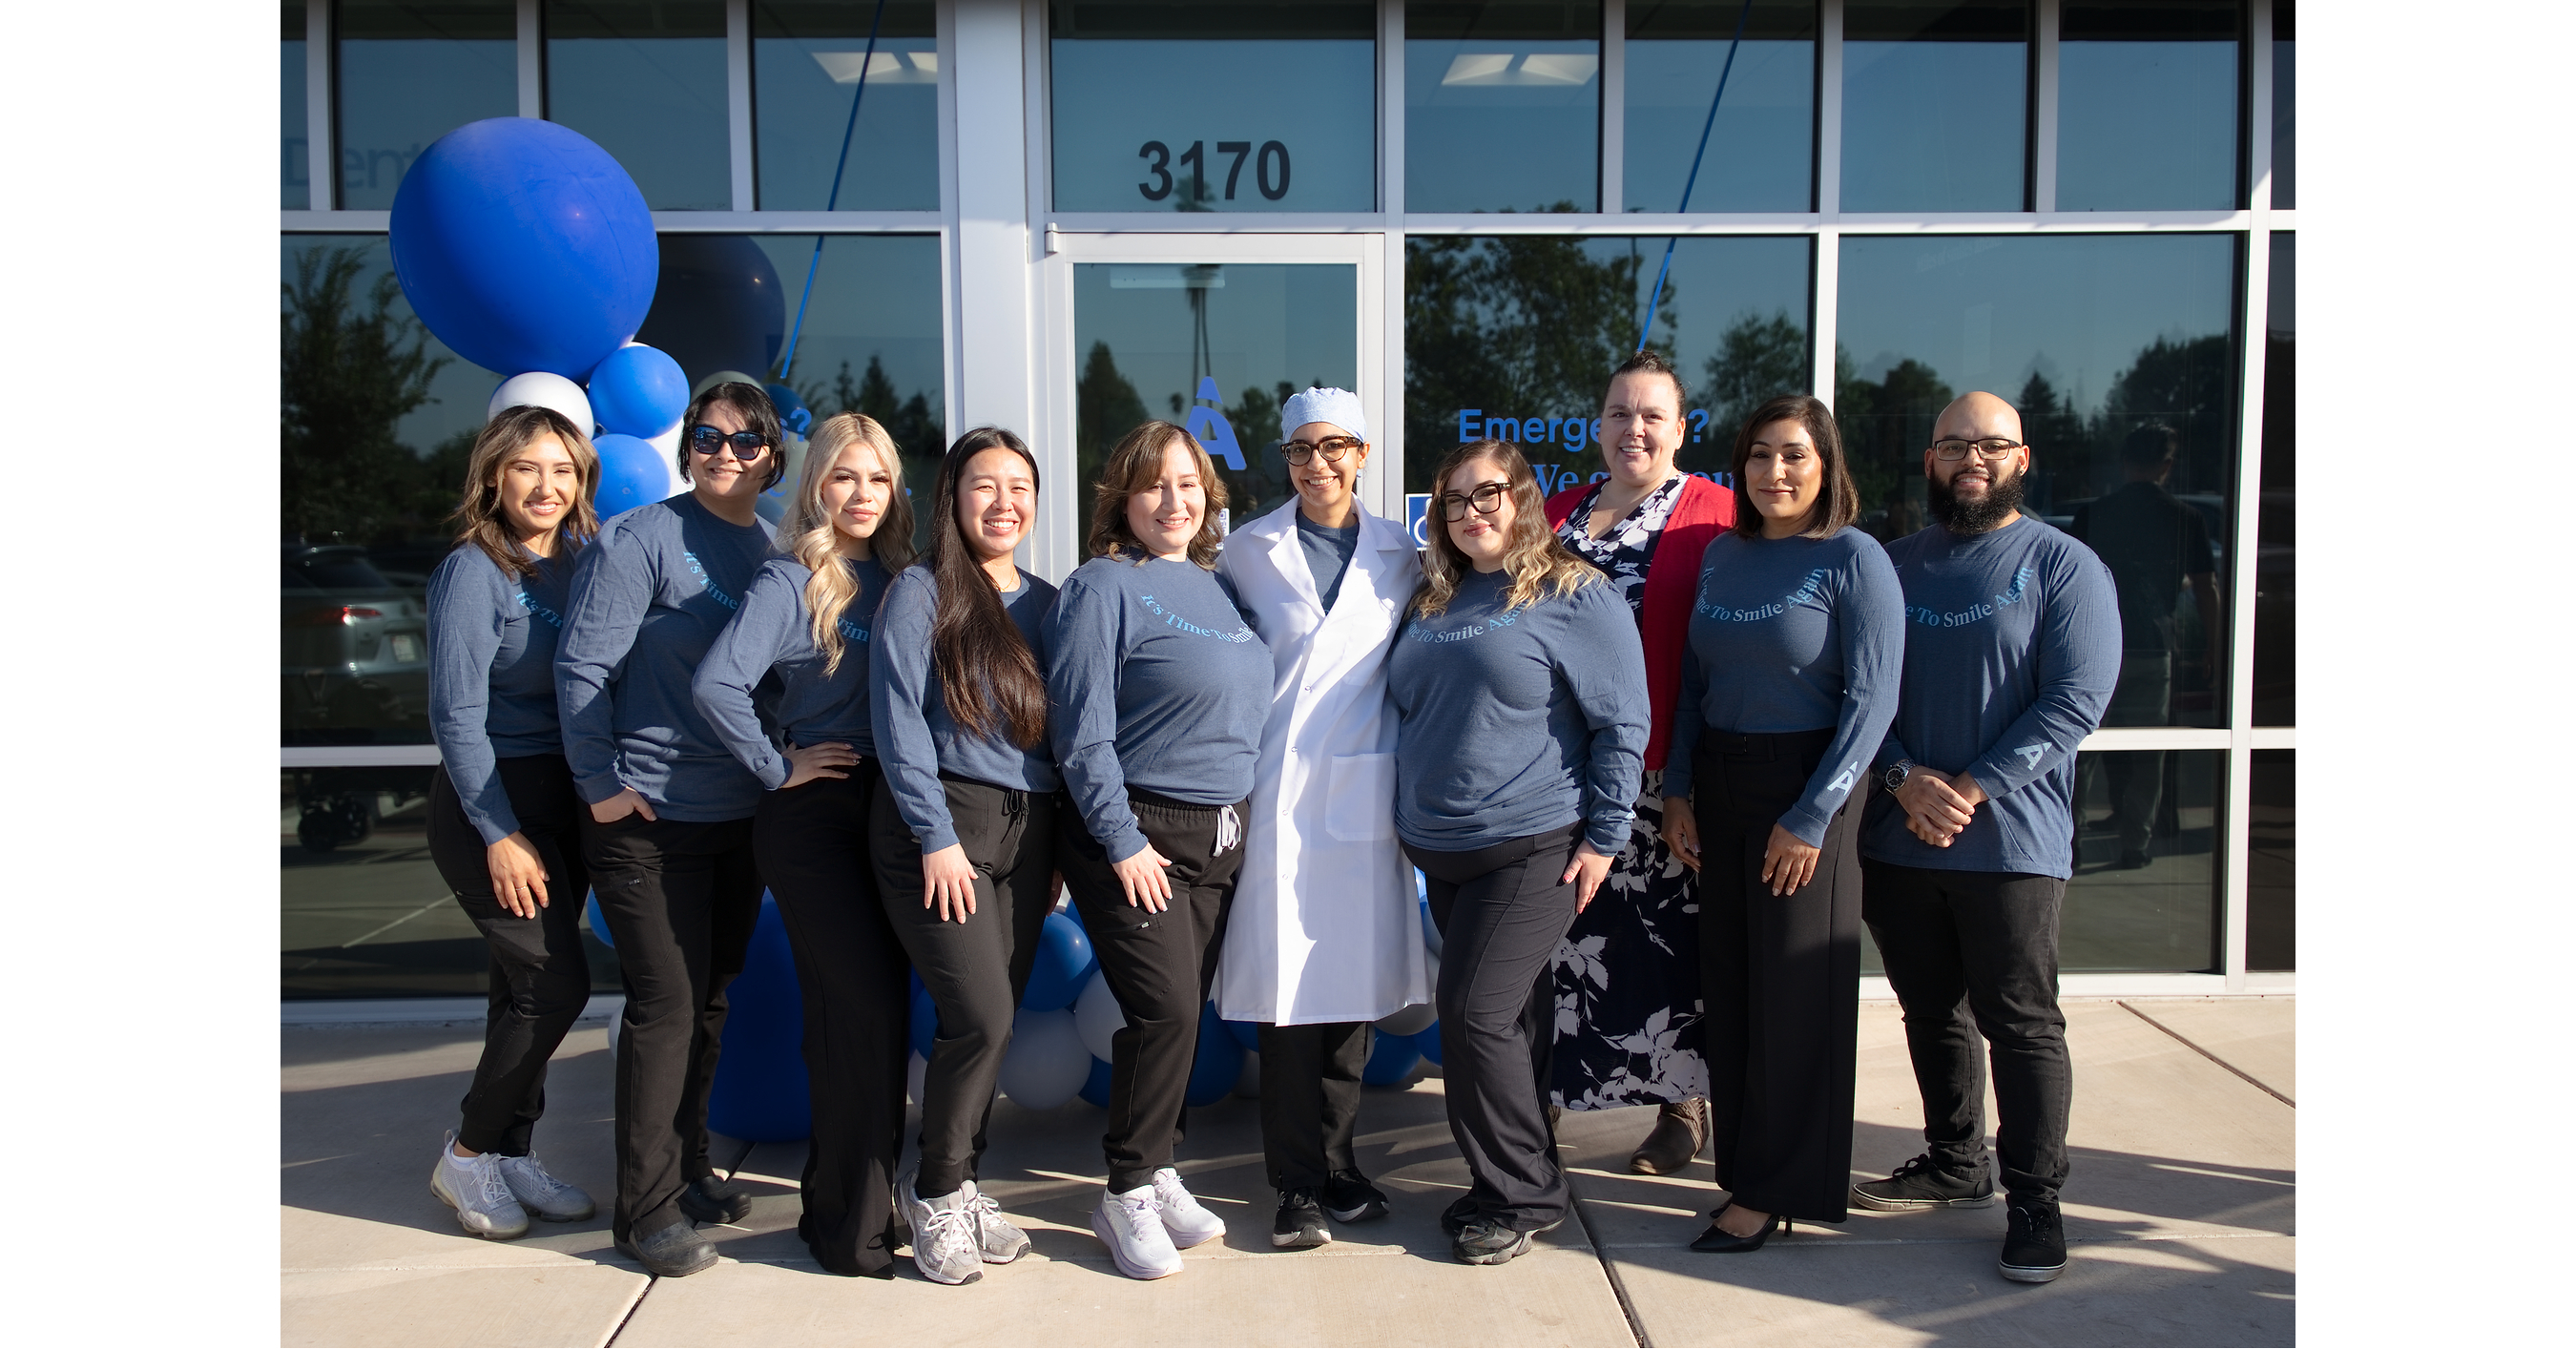
Aspen Dental opened a new supported practice in Merced, California, expanding access to preventive, emergency and restorative dental services in a region with below-state-average dental provider supply. The office offers walk-in and typically same-day urgent-care appointments, accepts many major insurance plans and provides financing options. The expansion targets a growing local market: Merced's population rose about 9% to 86,333 between the 2010 and 2020 censuses.
Analysis
This is not a material ALGN catalyst. Motto Clear Aligners may create a small incremental channel for clear-aligner adoption, but a single practice opening has no measurable effect on Align's volume, pricing, or consensus estimates. The more relevant read-through is that dental-service organizations are continuing to expand into provider-constrained, lower-income catchments, where financing approval rates, insurance mix, and clinician recruitment—not patient awareness—will determine unit economics.
For the next 1-3 months, the principal observable signal is whether broader dental chains sustain de novo openings without rising promotional intensity. If capacity additions outpace available dentists, labor costs and initial office ramp periods could pressure private operators, while independent practices may lose emergency and high-ticket restorative cases. Over 6-18 months, better local access could shift treatment mix toward preventive care and earlier intervention, limiting the severity—and revenue per patient—of delayed-care procedures; that is a modest offset to the bullish case for implant, denture, and aligner suppliers.
The consensus risk in consumer dental is assuming unmet need automatically converts into profitable demand. In Central Valley-type markets, out-of-pocket affordability is likely the binding constraint, making financed case acceptance and collections more important than appointment availability. A broader evidence base—same-store patient starts, financing delinquencies, and provider vacancy trends across Aspen's network—would be required before assigning a public-equity implication.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No directional ALGN position on this event; the estimated earnings impact is immaterial and the company-specific signal is zero.
- Monitor ALGN's next quarterly case-volume and average selling price disclosures for evidence that value-oriented DSO channels are adding incremental cases rather than cannibalizing premium Invisalign demand; consider a long only if North American volume growth accelerates without ASP deterioration.
- Use a watchlist for dental-exposure peers such as HSIC and XRAY: a sustained DSO expansion cycle could support equipment and consumables demand over 6-18 months, but wait for evidence in organic sales and management guidance before initiating exposure.
- For any future long in dental suppliers, invalidate the thesis if consumer financing delinquencies rise, same-store treatment starts weaken, or discounting drives clear-aligner ASPs lower; these variables would indicate that access expansion is producing traffic without profitable procedure conversion.
More News
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- One of our most recent defensive buys cleared a hurdle and its stock jumped
- Google unveils latest AI model, but Wall Street wants a breakout personal agent
- Most Americans say US-Israel war on Iran not worth fighting: Poll
- Wilbur Ross was Trump’s first-term tariff hawk. Now he says refunds give importers ‘an extra profit’ and pay them ‘more than the money’ they laid out
- Cullinan initiates FDA filing for lung cancer drug zipalertinib