
Společnost Pantum Technology představila na veletrhu IFA 2026 nová řešení pro tiskárny a rozšířila svou strategii pro evropský trh
Source: PR Newswire
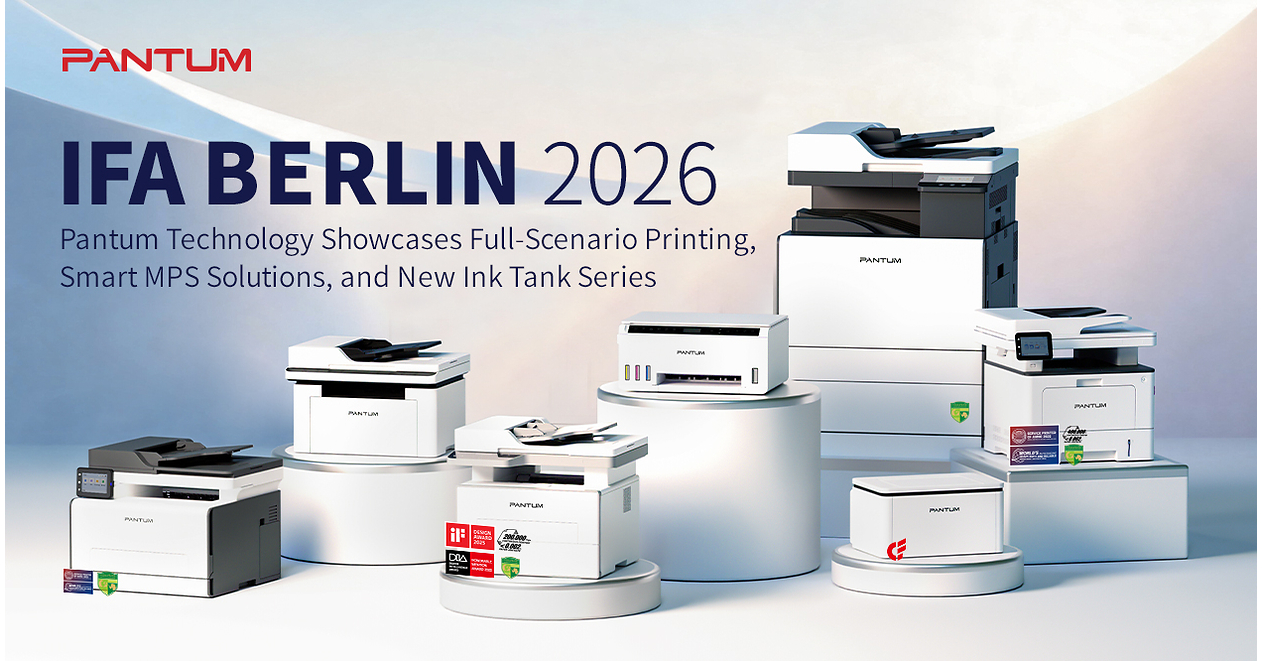
Pantum Technology unveiled new printer products at IFA 2026, including the AI-enabled BM2320NW and the MT310W ink-tank printer, which is planned for launch in 2027. The company also introduced A3 color laser models for enterprise and government users, including the CM420ADN with up to 2,096-sheet input capacity. Pantum is expanding its European strategy through local teams, warehousing, logistics and managed-print-service partnerships, building on distribution across more than 110 countries and regions.
Analysis
This is not yet a public-equity catalyst; it is a competitor-intelligence datapoint for the European print hardware and managed-print-services (MPS) market. Pantum's local warehousing, service build-out and A3 enterprise push could pressure entry-level laser pricing and channel margins, with the most exposed incumbents likely HP Inc. (HPQ), Canon (7751 JP), Brother (6448 JP) and Seiko Epson (6724 JP). The higher-risk segment is low-to-mid-volume monochrome A4, where product differentiation is limited and consumables attach rates—not hardware ASP—drive lifetime economics.
The more consequential second-order risk is enterprise MPS. If Pantum's third-party software integrations gain traction, it lowers a historical switching barrier for institutional customers and could force incumbent vendors to spend more on dealer incentives, service coverage and bundled supplies. That would be margin-negative before it becomes material to revenue; monitor European distributor inventory, tender wins, and consumables pricing over the next 6-18 months rather than treating product-show floor claims as demand evidence.
The AI labeling is unlikely to support a durable valuation rerating for listed printer OEMs: document workflow, security and fleet-management software are monetizable only when attached to recurring contracts. A near-term competitive threat is also constrained by delayed availability and unverified European certification, channel placement and service quality. Consensus may overreact to the hardware breadth while underestimating that corporate print fleets have long replacement cycles and procurement qualification processes, limiting displacement over the next 1-3 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No directional trade on this announcement alone; establish a 6-12 month competitive watch on HPQ, 7751 JP, 6448 JP and 6724 JP, focusing on European printing-segment gross margin, supplies revenue and MPS contract retention.
- For existing HPQ longs, require confirmation that Supplies revenue and Printing operating margin remain stable at the next two earnings reports; a >100 bp year-on-year printing-margin deterioration paired with weaker supplies revenue would validate a competitive-pressure short or hedge.
- Consider a conditional pair trade long 6448 JP / short HPQ only if European channel checks show Pantum taking sub-€300 laser share: Brother's comparatively stronger recurring consumables and business-device mix should be more defensible, but size only after evidence of share transfer.
- Set an alert for European public-sector or large-enterprise Pantum MPS awards, especially where PiPME or partner software is specified. Repeated wins would be a more actionable 6-18 month signal than retail product launches and would raise downside risk to incumbent service margins.
More News
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- China's Xi urges U.S. to cooperate on AI
- Trump Hosts China’s Xi With Trade, AI, Taiwan in Focus
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Automating Financial Model Updates: A Source-Controlled Workflow
- Weekly Update: Live Event Center, In-App Documents, and Faster Transcripts