
Lockheed Martin Ventures and Sumitomo's Presidio Ventures Back Diffraqtion
Source: PR Newswire
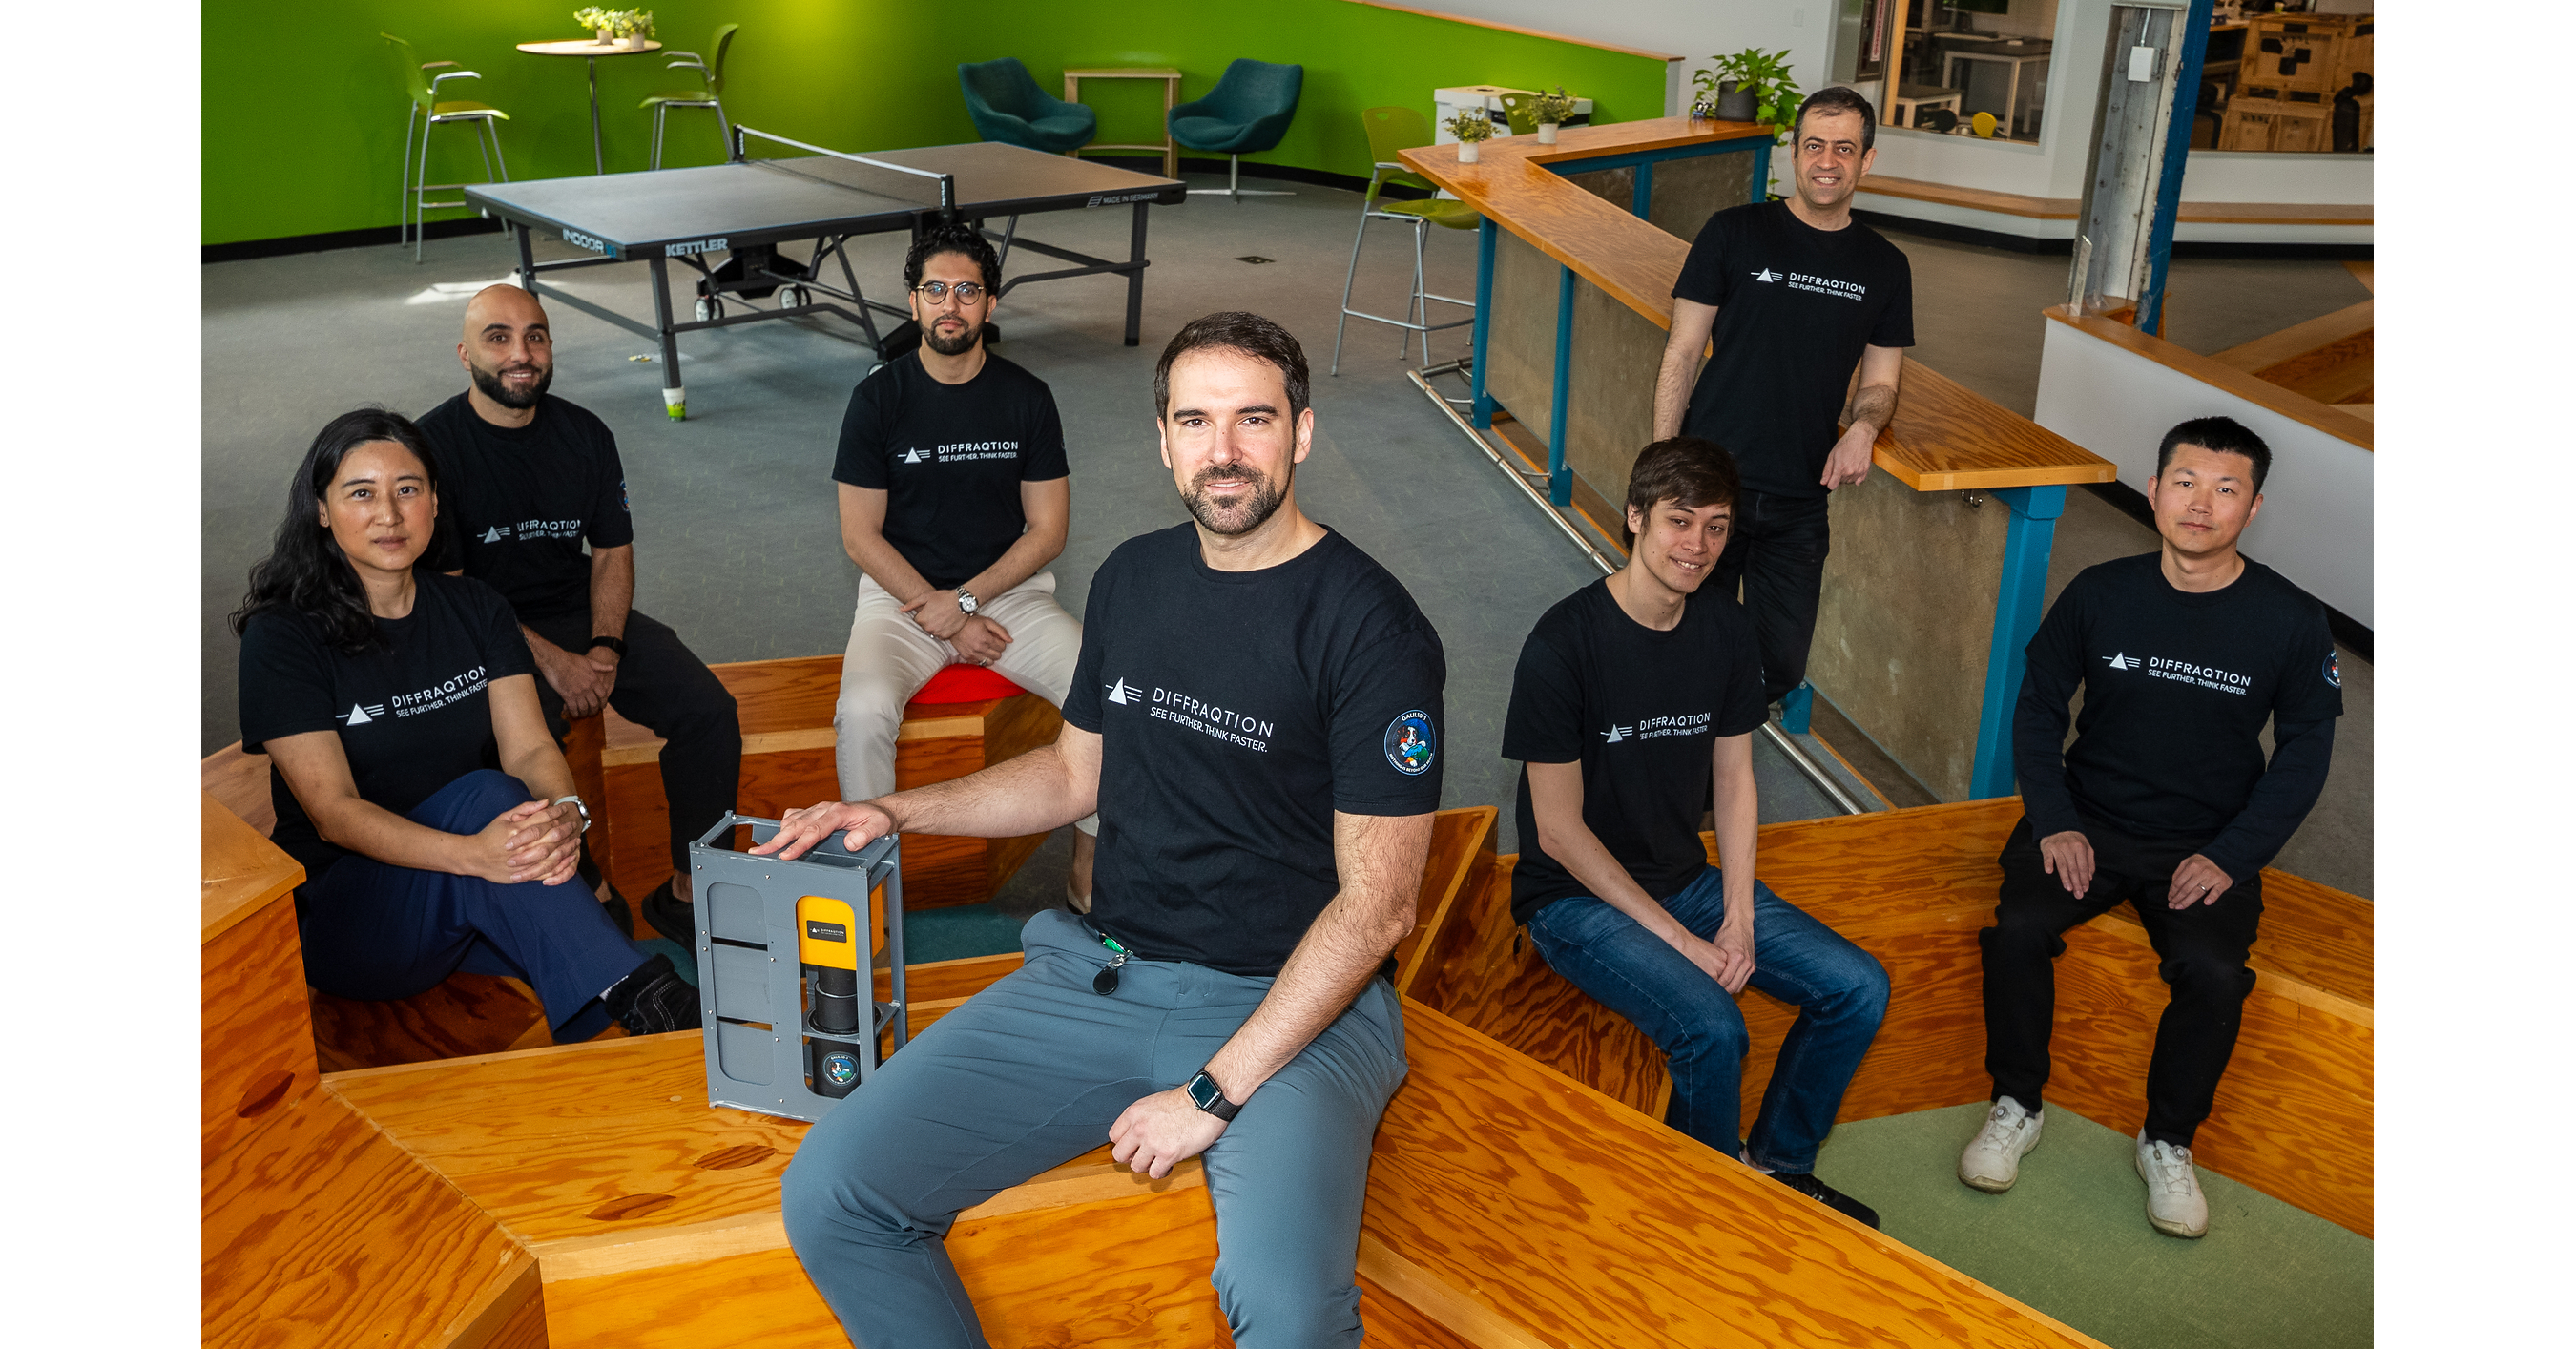
Diffraqtion raised $10M+ total in a capped pre-seed after strategic investments from Lockheed Martin Ventures and Presidio Ventures, alongside existing backers including SBI US Gateway Fund/Plug and Play and Collaborative Fund. The funding follows 7 months of rapid progress: on-sky demonstrations, DARPA Direct-to-Phase-II advancing into its second option period, and a NASA SBIR Phase I plus a $100,000 Space to Soil Challenge win. The company says simulations show resolution of features up to 20x smaller with much faster onboard classification, as it prepares its first fielded quantum camera via a hosted payload.
Analysis
This is more of a validation event than a revenue event. For LMT, the value is in option value: strategic exposure to a sensing stack that could compress aperture, power, and onboard compute requirements in future ISR/space-domain programs, but that only matters if it survives flight qualification and turns into a procurement line item. Near term, it is not a material P&L driver; the more important mechanism is improved positioning for future sole-source or capture wins against peers that still sell bigger-aperture, compute-heavy payload architectures.
The second-order effect is on the vendor chain, not the prime. If the platform works in orbit, it threatens smaller optical payload suppliers and edge-processing stacks more than it helps the headline investors. The commercialization path is still the choke point: hosted payload success, radiation/thermal robustness, and repeatable calibration are the real catalysts, likely 6-18 months out. A failed demo would push the story back by at least a year and re-rate this as science-project capital rather than defense IP.
Consensus may be overreading the word "quantum." This looks closer to a photonics and embedded-ML story than a quantum-computing story, so any sympathy bid in QUBT would be concept confusion, not fundamental read-through. The more likely winning framework is incremental adoption in niche defense and inspection use cases first, with broad commercial penetration much later; until then, the market should treat this as a strategic hedge, not a growth inflection.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Small tactical long LMT for 1-3 months as a strategic-optionality trade; risk/reward is favorable only if the market starts pricing a larger future capture pool, but the position should stay light because near-term EPS impact is negligible.
- Buy SSUMY on weakness as a long-dated venture-optionality name; treat this as a low-conviction 6-18 month hold tied to industrial distribution of emerging sensing tech, not an earnings trade.
- Fade any sympathy rally in QUBT over the next 1-2 weeks; this is not a direct beneficiary, and a headline-driven move above the peer group would likely revert once the market separates photonics from quantum-computing exposure.
- Set a catalyst alert on the first hosted-payload/flight-heritage update; if that milestone is confirmed, add to LMT, but if qualification slips or payload results are soft, cut the thesis and avoid paying up for the story.
More News
- What is the ‘Mother of All Bombs’ US could use in Iran?
- Trump ballroom's biggest donors were overwelmingly tech and telecom companies
- Lockheed Martin Unveils New Patriot for Army Air Defense Contest
- Brian Sullivan: Why the 'real' price of oil is likely $30-$40 higher than where it is now
- Treasuries Soar as Tech Slump Threatens Growth
- Latest Oil Market News and Analysis for Oct. 16
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital IQ Alternatives for Research and Deal Work
- Research Workflows, Report Format Selection, and Interactive Synthesis