
World’s Largest Retirement Community Set to Borrow $180 Million
Source: Bloomberg
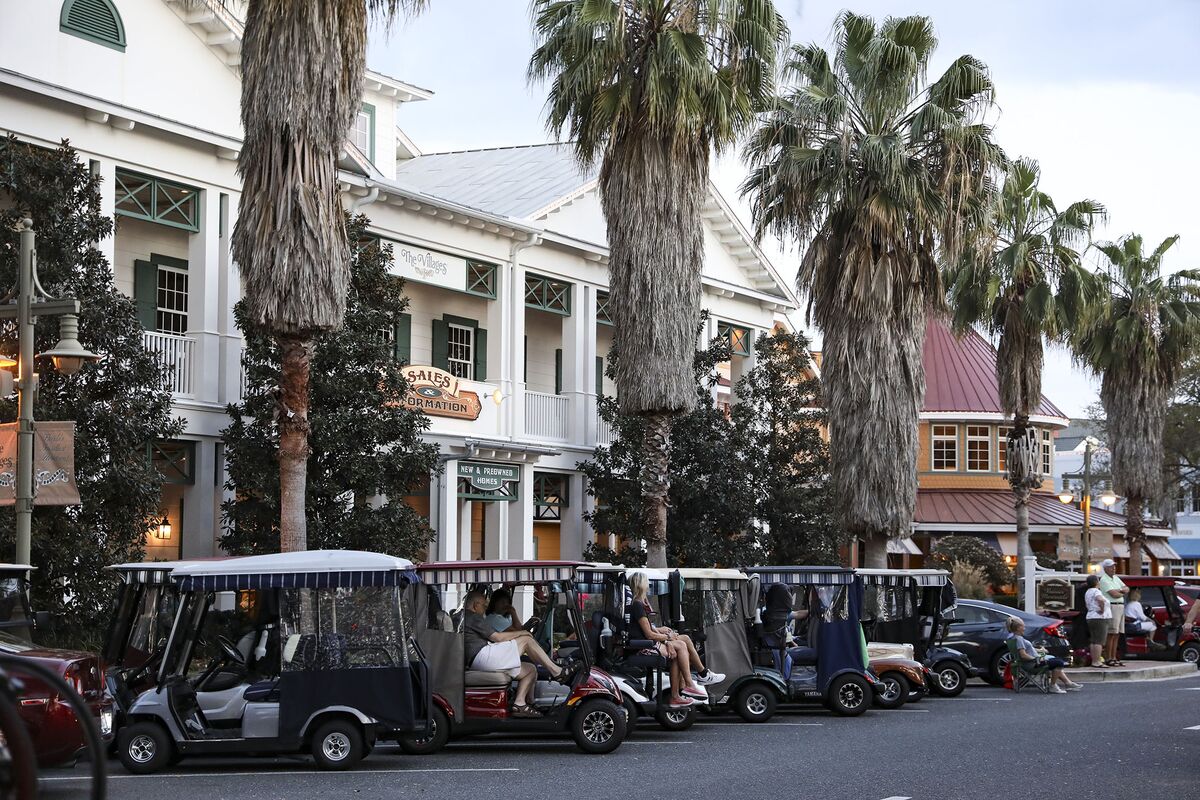
The Villages, a 57,000-acre Florida retirement community with about 170,000 residents, is looking to issue almost $180 million in high-yield debt to finance additional homes. The article provides no borrowing terms or indication that the debt has been issued.
Analysis
The key underwriting question is not the community’s growth story but who legally owes the debt and what cash flows secure it. If repayment depends on lot or home sales, slower absorption, construction costs, and Florida insurance availability could weaken coverage just as borrowing costs rise. If it is backed by assessments or other community revenues, the burden may instead shift toward residents and could affect affordability, resale demand, and future development pace. Those are distinct credit cases; the article does not identify the issuer, lien, or repayment source.
Near term, a $180 million placement is unlikely to move broad housing or high-yield benchmarks, but a thinly traded local issue could carry meaningful liquidity and disclosure risk. Over 1–3 months, the offering documents and pricing should reveal whether investors are being paid for project, weather, insurance, and concentration risks. Over 6–18 months, the more important signal is whether new-home absorption and infrastructure costs support continued expansion without rising resident charges.
Contrarian angle: population growth alone is not credit enhancement. It can attract capital while also increasing infrastructure needs and exposure to Florida property-insurance constraints. No directional trade is justified from the article alone; treat this as a deal-level diligence opportunity, not a broad housing signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- Do not trade broad homebuilder or high-yield exposure on this announcement alone; the issue is small and its economic linkage to listed peers is unestablished.
- If evaluating the bonds, wait for the offering documents and verify the legal obligor, pledged revenues, lien seniority, debt-service coverage, covenants, maturity schedule, and use of proceeds before comparing yield with similarly rated local or infrastructure debt.
- Set a diligence alert for home-sale absorption, construction and infrastructure costs, resident assessments, and Florida insurance availability; deterioration in these measures would challenge the expansion-credit thesis.
- Avoid treating population growth as a substitute for repayment capacity. Reassess only if disclosed cash flows and protections justify the spread after accounting for concentration and secondary-market liquidity.
More News
- Japan’s 20-Year Bond Sale Sees Strongest Demand on Record
- Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line
- What Neoclouds Like CoreWeave Reveal About the Fragile AI Economy: Big Take Podc
- The U.S. national debt is approaching the point where bond traders see ‘mounting risk’ of a ‘vicious cycle,’ Moody’s top economist says
- MTR Bets $5 Billion on a Hong Kong City That Doesn’t Exist Yet
- The French are rioting as inflation hits 3.4% while wage growth and GDP remain stagnant. It’s higher in Trump’s America