
Generac's stock soars more than 30% after Amazon deal cements its status as AI power player
Source: marketwatch.com
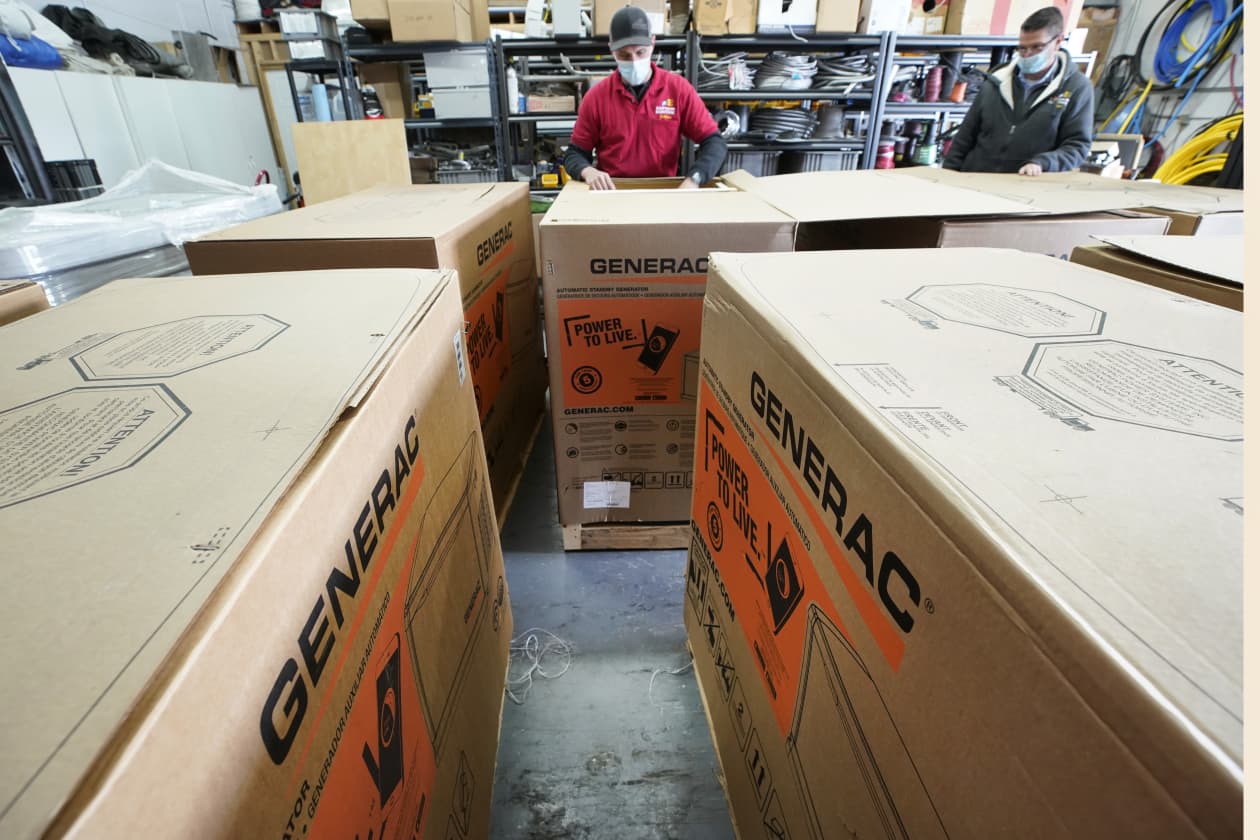
Generac signed an Amazon deal worth up to $8 billion to supply backup-power generators for data centers, including $2.4 billion of initial deliveries in 2027-2028. The agreement cements Generac's exposure to AI data-center power demand and includes warrants allowing an Amazon subsidiary to acquire Generac shares through 2033. Generac shares surged more than 30% following the announcement.
Analysis
The economic value is less about a one-time backlog mark and more about whether GNRC can convert hyperscaler qualification into a repeatable data-center platform. If production capacity is reserved through 2028, the company gains materially better demand visibility than its historically weather-sensitive residential business, supporting a higher industrial/mission-critical earnings multiple. The key unknown is gross-margin quality: Amazon's warrant structure likely exchanges demand certainty for pricing leverage and potential dilution, so the market should not capitalize the full headline value until unit economics, warrant strike/vesting terms, and capacity investment are disclosed.
Second-order beneficiaries include engine, alternator, switchgear, and controls suppliers, while CAT and CMI face a more nuanced outcome: sector demand expands, but GNRC has gained a powerful reference customer in a market where reliability certifications and field-service records create high switching costs. Amazon's commitment can also pull forward GNRC working-capital needs and plant capex well before revenue recognition, making free-cash-flow conversion—not reported backlog—the central 2027-28 debate. Over the next 1-3 months, supplier lead times, incremental hiring/capex, and management's margin commentary should determine whether the post-announcement rerating holds.
Contrarian risk is that investors treat the agreement as fully firm and immediately accretive despite a long delivery runway and likely conditional volume profile. A broader hyperscaler capex slowdown, permitting/grid-connection delays, or an Amazon decision to dual-source aggressively would reduce the implied terminal value well before shipments begin. Conversely, additional named-hyperscaler awards would validate GNRC's data-center position and make current consensus estimates structurally too low for 2028.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.82
Ticker Sentiment
Key Decisions for Investors
- Do not chase GNRC in the opening volatility; establish a starter long only after warrant dilution, manufacturing-capex requirements, and expected gross-margin range are disclosed. Target a 6-18 month position, adding on a 10-15% retracement if management confirms that incremental program margins are at least in line with the industrial segment; exit if required capex/working capital materially erodes expected free-cash-flow conversion.
- Use a GNRC long versus a short XLI basket only as a tactical 1-3 month relative-value expression if GNRC's premium remains driven by contract-specific evidence rather than a broad AI-infrastructure beta move. The risk is that power equipment scarcity lifts the entire industrial complex; cover the hedge if CAT/CMI announce comparable hyperscaler awards or broad generator lead times extend.
- Monitor CMI, CAT, and electrical-power suppliers for read-through rather than shorting them: a capacity-constrained backup-power market can allow incumbents to raise pricing even if GNRC wins share. A disclosed multiyear capacity expansion by GNRC without matching supplier commitments would instead be a warning of margin dilution and execution risk.
- Set an event alert for the next GNRC earnings call: guidance for 2027-28 revenue, incremental gross margin, capex, and warrant accounting are the decisive catalysts. If management cannot quantify these items, treat the move as sentiment-driven and reduce exposure rather than underwriting the full contract value.
More News
- Companies promised AI gains— here's how the payoff showed up in earnings
- AWS grows 39% and Amazon will spend even more on AI in 2027
- Stocks started the week with promise but ended in despair. Our take on the big reversal
- Fears over $828 billion AI capex spending spree help erase $1 trillion in market value
- AI boom hits a wall on Wall Street as OpenAI cuts fundraising target while Meta gets a credit warning over its cash flow, spending and monetization
- OpenAI pares fundraising goal, now seeking up to $20 billion in latest round