
Petrobras' P-80 Platform Begins Journey to Buzios Field
Source: zacks.com
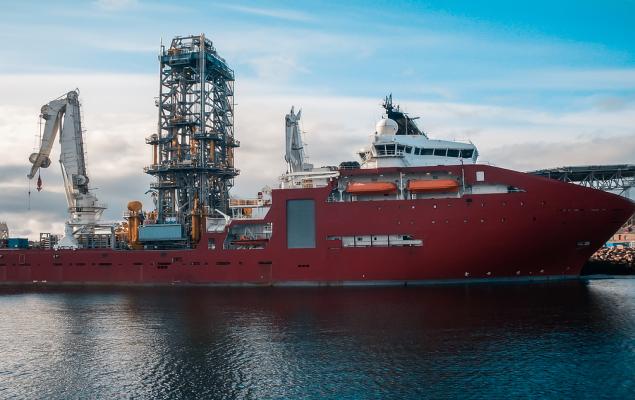
Petrobras' P-80 offshore platform has departed Singapore for Brazil's Búzios field and is scheduled to start production in 2027, with capacity of up to 225,000 barrels of oil and 12 million cubic meters of gas per day. The unit is the first of six standardized platforms intended to lower construction costs, improve reliability and accelerate development of Brazil's largest producing field. Búzios recently exceeded 10 million cubic meters per day in monthly gas exports and reached a daily record of 14.1 million cubic meters.
Analysis
The investable read-through is not near-term production but execution de-risking of Petrobras' multi-unit offshore development program. If standardized FPSO construction translates into shorter commissioning and flatter unit costs, PBR can convert a larger share of its pre-salt resource base into free cash flow without proportionate exploration spend; that supports a lower sustaining-capex profile and potentially narrows part of its persistent emerging-market/governance valuation discount over the next 6-18 months. The critical confirmation is whether successive units meet first-oil dates and ramp curves, not engineering claims made before handover.
A less obvious effect is incremental Brazilian associated-gas availability. Sustained growth in domestic gas supply could pressure regional industrial gas prices and improve feedstock economics for Brazilian power-intensive and petrochemical users, while limiting upside for LNG-import infrastructure. Globally, the eventual liquids contribution is material for a single asset but too delayed and phased to change the 2026 oil balance; it is therefore not a reason to alter Brent exposure today.
PBR's risk is asymmetric: project execution success is largely embedded in its long-dated development narrative, whereas a 2027 slippage, contractor claim, or weaker-than-expected gas evacuation capability would raise capex and defer cash generation. Political risk remains the more immediate multiple constraint: any change in fuel-pricing discipline, dividend framework, or domestic-investment mandate can overwhelm operational progress. The article's favorable implications for DK, E and PSX are non-causal; their earnings are driven predominantly by refining margins, European gas/LNG conditions, and capital-return execution rather than this offshore project.
Contrarian view: do not chase PBR on vessel-mobilization milestones. The better signal is a repeatable pattern of ramp-up days, unit operating cost, and capex-per-flowing-barrel across P-78/P-79 and later deliveries; evidence of that pattern would justify adding before 2027 volumes enter consensus estimates.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest 6-18 month PBR.A overweight versus XLE, sized for political-event volatility rather than project news. Add only after the next quarterly disclosure confirms ramp-up performance and upstream capex remains within plan; target 15-20% upside from multiple normalization and cash-flow revisions, with thesis invalidated by a material 2027 start-up delay, capex guidance increase, or adverse fuel-pricing/dividend-policy change.
- Use a PBR.A / COP pair rather than an outright oil-beta position: long PBR.A, short COP in equal energy-beta terms over 6-12 months. This isolates potential pre-salt execution and valuation catch-up from Brent direction; exit if PBR's unit lifting-cost or commissioning metrics deteriorate relative to plan, or if Brazilian policy uncertainty intensifies.
- Do not buy DK, PSX, or E on this development. Reassess DK/PSX on US crack spreads and E on European gas/LNG balances; none has a sufficiently direct earnings sensitivity to justify a trade from this catalyst.
- Set an event-driven alert for Petrobras' next results: require evidence of stable production efficiency, no upward revision to development capex, and a credible gas-offtake path before increasing exposure. Until then, this is a watch-item rather than a days-to-weeks catalyst.
More News
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Markets slip on dollar pressure, but this IT stock is up 10% today
- Venture Global signs 20-year LNG supply deal with ConocoPhillips
- Up 10%+ since July - an alternative asset manager on our AI list keeps climbing
- Goldman Sachs adds Amazon stock and four others to Director’s Cut list for October
- Dollar at 17-month high as global bond rout hits euro
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper
- Run Cost-Controlled Financial Research in AllMind Agent Studio