
ASUS Expands AI Infrastructure Ecosystem from Cloud to Edge
Source: PR Newswire
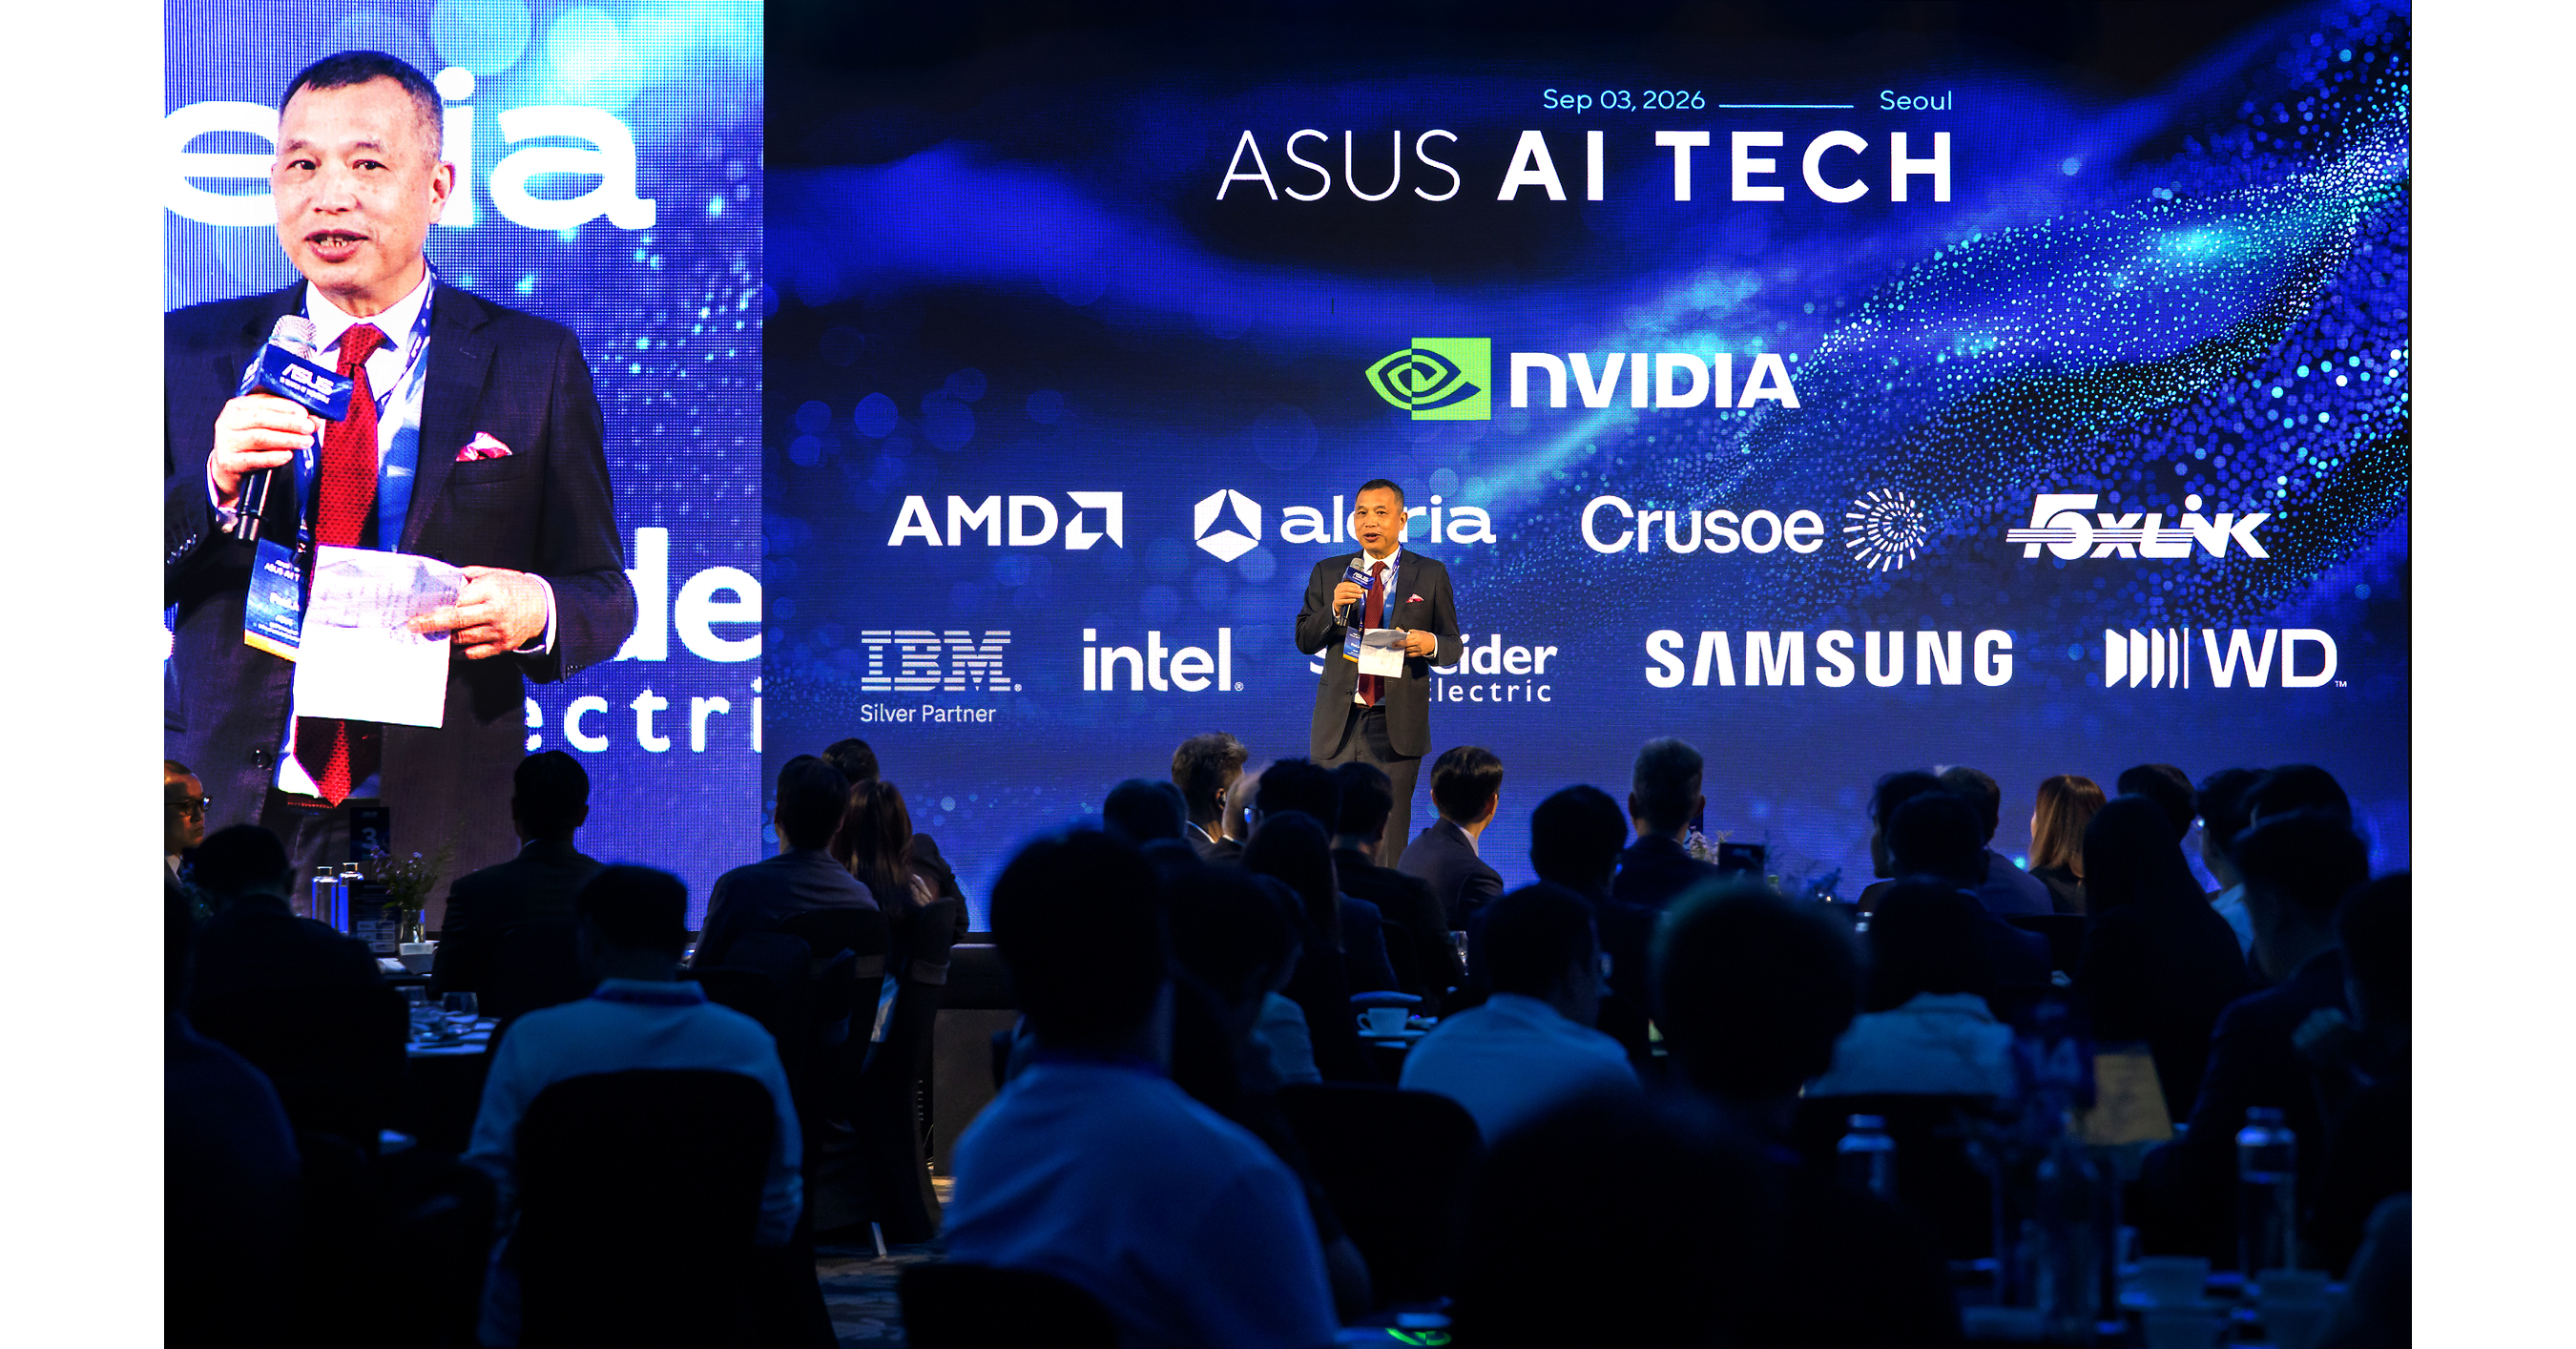
ASUS announced an expansion of its AI infrastructure ecosystem, partnering with Intel and AMD and unveiling new server and edge systems for AI/HPC workloads. Highlights include Intel Xeon 6-based RS700-E12-RS4U and RS720-E12-RS12U, plus AMD EPYC 9006 Series platforms such as RS720A-E14B-R32U and RS500A-E14B-R12U, and AMD Instinct MI350P-accelerated ESC8000A-E13P. ASUS also introduced edge-focused hardware like the Intel Core Ultra Series 3-powered RUC-2000 series with up to 180 AI TOPS, positioning the company to scale AI deployments from cloud to industrial edge.
Analysis
This reads more like channel validation than a demand event. The important mechanism is not the product launch itself, but whether a broad OEM partner list lowers switching friction for next-gen server and edge designs; that can modestly improve share retention for AMD and Intel without moving near-term revenue. The chips mentioned are still subject to long qualification cycles, so any stock reaction should fade unless it is followed by order commentary from integrators or a meaningful revision in server capex plans.
Competitive dynamics are mixed: AMD has the cleaner upside because any incremental AI infrastructure mix tends to carry better margin and can support further socket gains if performance-per-watt remains competitive. Intel’s edge positioning is defensible, but it is more about preventing share loss than taking share; that matters for downside protection, not acceleration. IBM is mostly a services pull-through story here, and the hardware announcement alone is not enough to change the earnings math.
The contrarian risk is that the market overestimates this as an AI spending inflection when it may just be ecosystem theater. The next 1-3 month catalyst is channel checks and enterprise capex commentary; the 6-18 month risk is that rugged edge AI remains niche while hyperscaler and inference spend stays concentrated elsewhere. What would falsify the bullish read is any evidence of price discounting, delayed deployments, or flat/declining data-center guidance on the next earnings prints.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No immediate outright trade; treat this as a watch item until the next AMD/INTC earnings cycle or channel checks confirm actual design wins. If bookings do not re-accelerate, the announcement should be faded rather than chased.
- Relative value: long AMD / short INTC over 1-3 months on any post-news weakness. Rationale: AMD has more operating leverage to incremental AI/server mix; target 8-12% relative outperformance, invalidated if Intel stabilizes server share and AMD guidance softens.
- If already long either name, use the event to tighten stops rather than add aggressively. The news is supportive but low-conviction; upside should be capped absent a capex upgrade from OEMs.
- Do not express this through IBM as a hardware proxy; only consider IBM if subsequent disclosures show services backlog tied to AI infrastructure deployments.
- Set an alert on next quarter server/edge commentary from OEMs and integrators; if discounting or lead times weaken, reduce AMD exposure first and cover INTC shorts.
More News
- Nasdaq Index: AI Selloff Deepens as Chips and CoreWeave Break
- Chip Stocks Just Fell 8 Days in a Row, Their Longest Losing Streak Since 2008
- How Nvidia Could Make $150 Billion Look Small
- The Nasdaq-100's 6 Best Stocks This Year, and Whether They Can Keep Going
- 1 Red Flag That AMD Investors Should Be Aware Of Now
- Tech Stock Sell-Off: 1 Unstoppable ETF to Buy on the Dip in 2026