
Pulsenmore Expands Its Fertility Platform into the UK
Source: PR Newswire
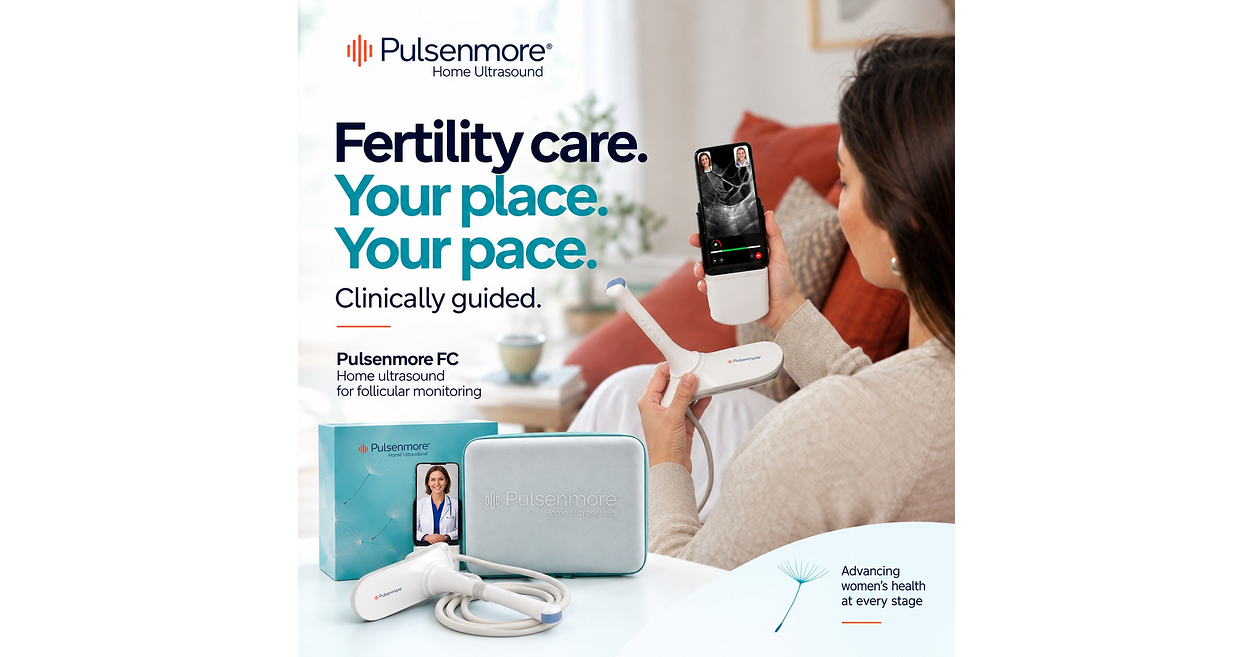
Pulsenmore completed MHRA registration for its Pulsenmore FC home ultrasound system, enabling commercialization in the UK and Northern Ireland fertility market after obtaining EU MDR registration. The addressable UK market included roughly 53,000 IVF patients and more than 100,000 fertility-treatment and storage cycles in 2024, with IVF accounting for 21,400 births, or 3.2% of UK births. The approval expands Pulsenmore beyond pregnancy monitoring into fertility care and supports planned expansion into additional international markets.
Analysis
This is a commercialization permission, not evidence of demand, reimbursement, or unit economics; the equity read-through should therefore be limited until Pulsenmore identifies contracted UK clinic partners and paid deployments. The critical adoption constraint is not device clearance but whether clinics can redesign monitoring workflows without increasing clinician review time or assuming medico-legal liability. A direct-sales model would likely produce slow, lumpy revenue and high customer-acquisition expense; an agreement with a fertility-clinic network or software/workflow partner would materially improve the revenue-quality signal.
Near term (days to 1 month), any rally in PLSM is vulnerable to micro-cap liquidity and promotional extrapolation from addressable-cycle figures. Over 1-3 months, catalysts are first named UK customers, reimbursement/private-pay pricing, utilization per enrolled patient, gross margin, and evidence that at-home scans replace rather than merely supplement clinic visits. The key falsifiers are no commercial contract by the next results update, cash runway falling below 12 months, or disclosed implementation costs that make clinic savings uneconomic.
The 6-18 month upside is broader than a single fertility product: successful remote-image review could create recurring software/clinical-service revenue and validate adjacent women's-health applications. Conversely, incumbents in fertility EMR and ultrasound workflow—such as Vitrolife (VITR.ST) and CooperCompanies (COO)—have clinic relationships and could bundle comparable monitoring capabilities, limiting Pulsenmore's pricing power. The contrarian view is that fertility patients may value convenience, but clinics capture most of the economic benefit; absent shared-savings reimbursement or demonstrable capacity expansion, patient enthusiasm alone will not drive procurement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.52
Key Decisions for Investors
- No immediate directional position in PLSM solely on the registration; treat as a watchlist catalyst because revenue, pricing, clinic conversion, share liquidity, and current valuation are missing.
- Set an event-driven long trigger for PLSM only after disclosure of a named UK clinic/network contract plus pricing or minimum-volume economics; size modestly and reassess after the first two quarterly utilization disclosures. Upside requires recurring revenue evidence, while a missed commercialization milestone is the stop condition.
- Monitor COO and VITR.ST for evidence of remote-monitoring product partnerships or acquisitions over the next 6-18 months; their installed-base advantage makes them more investable beneficiaries if at-home fertility monitoring proves clinically economic.
- For existing PLSM holders, reduce into an approval-driven liquidity spike unless accompanied by contracted revenue guidance; retain exposure only if management demonstrates that home monitoring substitutes for clinic scans and improves clinic throughput rather than adding a parallel workflow.
More News
- UN mission finds evidence of U.S. war crimes in Iran; Washington rejects report
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus
- California AG Bonta on Paramount-Warner Bros., Meta and AI
- Microsoft exec called AI scraping the “largest theft of labor in human history”
- Jensen Huang says Nvidia will sell twice as many chips next year
- Generac shares surge on big Amazon deal. Wall Street thinks the generator stock has more to go
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Investment Research Platform?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?