
Brandywine Realty Trust: This 10.6% REIT Has Many Problems
Source: seekingalpha.com
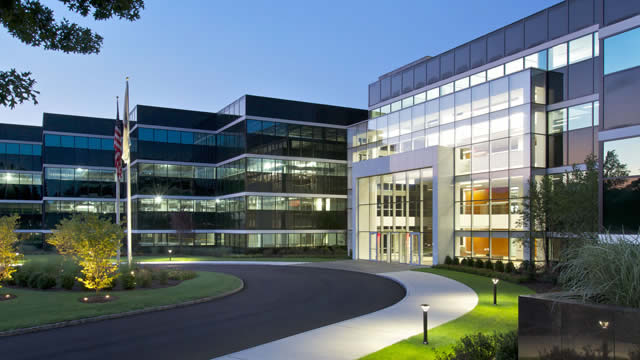
Brandywine Realty Trust (BDN) screens as cheap at a 5.5x P/FFO discount, but leverage and refinancing risk dominate the story: net debt/EBITDA is ~9.0x with ~$700M of maturities due in 2027 and a stated need for asset sales to delever. The 10.6% dividend yield looks pressured, with a Q2 payout ratio of 102.9% and two dividend cuts over the past three years. Overall, balance-sheet concerns likely outweigh valuation support, potentially pressuring equity and credit sentiment.
Analysis
BDN is behaving less like a valuation story and more like a financing optionality trade: equity holders are effectively subordinated to the capital structure until the 2027 wall is visibly de-risked. In this setup, any incremental asset sale at a discount helps creditors more than common equity because it reduces leverage while also shrinking the earnings base that supports the dividend and multiple. That means headline NAV discounts can persist much longer than they look "cheap" on paper, especially in an office market where buyers demand deep underwriting haircuts.
The immediate market risk is not bankruptcy, but a slow bleed from dividend credibility. Once income funds and REIT ETFs stop viewing the yield as bond-like, the stock can de-rate further even without a fresh negative headline; that is the second-order effect that matters over the next 1-3 months. The real winners are higher-quality office names with lower leverage and better access to unsecured capital, especially BXP and, to a lesser extent, HIW/KRC, because capital tends to rotate toward balance-sheet resilience when refinancing risk becomes the dominant factor.
The contrarian case is that the move may be somewhat crowded after repeated cuts and a high nominal yield, so a near-term rally is possible if rates fall and the company announces a clean asset sale. But the thesis is only invalidated if BDN executes non-dilutive deleveraging fast enough to push leverage meaningfully below ~8x and refinance terms stop widening; absent that, the equity remains a residual claim with poor risk/reward versus stronger peers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately negative
Sentiment Score
-0.55
Ticker Sentiment
Key Decisions for Investors
- Short BDN common on any 5-10% relief rally; use a 3-6 month horizon and treat a move back above recent highs as a signal the market is ignoring the balance-sheet overhang.
- Pair trade: long BXP / short BDN for 6-12 months. Thesis is that the market will continue to reward balance-sheet quality within office as refinancing becomes the key differentiator; downside if office cap rates compress broadly on falling rates.
- Buy BDN 6-12 month put spreads only if options liquidity is acceptable; this is a cleaner expression than outright shorting if the stock is volatile around asset-sale headlines.
- Watch for a falsifier: announced asset sales that reduce leverage meaningfully without punitive pricing, or a debt transaction that tightens spreads and preserves the dividend. That would warrant covering the short.
- Avoid owning BDN for yield in dividend-focused baskets; if you need office exposure, prefer peers with lower refinancing risk rather than reaching for the highest nominal yield.
More News
- ‘France, truly, is on the brink’ and just days away from a make-or-break moment in its debt crisis, analyst warns, as protests turn into riots
- AI stocks plunge. Inflation heats up. Where we're still finding opportunities
- Bending Spoons wants to revive software castoffs. Berkshire is backing the plan
- ‘How many canaries have we killed in the coal mine?’ — Wall Street debates if the latest AI bubble warnings are another head fake or the real thing
- Nasdaq Index: AI Selloff Deepens as Chips and CoreWeave Break
- ECB's Lagarde says bond selloff will slow inflation
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Family Offices: A Stack by Decision Type
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs