
KT&G Begins Full-Scale Operations at New Indonesia Plant, Completing Five-Country Global Production System
Source: PR Newswire
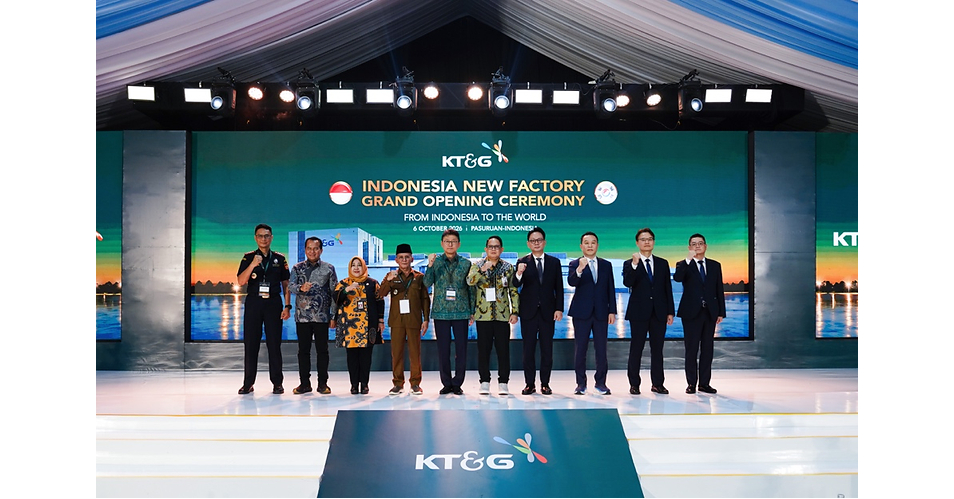
KT&G began full-scale operations at its new Indonesia plant, which will add up to 21 billion sticks of annual capacity once all nine lines are installed. Combined with its existing 14-billion-stick facility, Indonesia capacity is expected to reach 35 billion sticks, making it KT&G’s largest overseas production base and supporting exports to markets including Taiwan, Mongolia, Nigeria and India. The plant advances the final stage of the company’s KRW 2.4 trillion overseas CAPEX program; KT&G also plans to raise overseas production to more than 60% of total output by 2028 and cites buybacks, share cancellations and higher dividends as ways to enhance shareholder value.
Analysis
Capacity is an option, not earnings: the key swing factors are how quickly the additional lines are installed and utilized, and whether exports add profitable volume rather than shift production between plants. If localization lowers freight and improves service, KT&G could gain resilience and cost leverage; if regional demand or export access disappoints, the enlarged footprint risks underutilization and price competition. Indonesian incumbents may face tougher competition if KT&G scales share, but the release provides no destination-level volumes or evidence of displacement from Philip Morris International, BAT, or Japan Tobacco.
Near term, the more investable change is the potential transition from heavy overseas investment toward cash returns. Treat buybacks and dividends as management intent, not a quantified cash-flow commitment: completion of the investment cycle could support free cash flow, but only if remaining capex, ramp costs, and working capital do not absorb the savings. In 1–3 months, verify line commissioning, utilization, export volumes, and actual repurchase/cancellation and dividend disclosures. Over 6–18 months, monitor whether overseas production exceeds 60% as planned and whether margins and cash conversion improve. Indonesia, destination-market regulation, excise changes, and currency moves can all erode the expected logistics benefit. The contrarian point: headline capacity may invite a growth re-rating before demand and returns on capital are demonstrated. Falsify the constructive view with delayed ramp-up, weak export growth, deteriorating margins/FCF, or reduced capital-return execution.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- Do not chase the capacity headline alone. Consider a staged long in KT&G only after evidence of utilization and export growth, alongside improving free-cash-flow conversion; the release does not provide enough data to size an earnings uplift or set a valuation target.
- Track quarterly overseas production mix, plant utilization, export volumes by destination, capex and working-capital outlays, and realized buybacks/dividend changes. These are the confirmation signals for a post-capex cash-return thesis.
- Keep a watch—not a short—on tobacco peers including Philip Morris International, BAT, and Japan Tobacco until product and destination overlap establishes which competitors are actually exposed to KT&G's added supply.
- Reassess the constructive view if line installation slips, exports fail to ramp, margins or free cash flow weaken, or announced shareholder returns do not materialize; monitor excise and market-access changes across Indonesia and export destinations.
More News
- Tanker hit by multiple projectiles off north coast of Qatar, UKMTO says
- Why is SK Hynix stock gaining today?
- Elon Musk blames Indian 'oligarchs' for stalling Starlink launch
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Yemeni government forces claim 1,860 Houthis ‘neutralised’