
Meshy Surpasses $100 Million in Annual Recurring Revenue, Growing 100x in Under Two Years
Source: PR Newswire
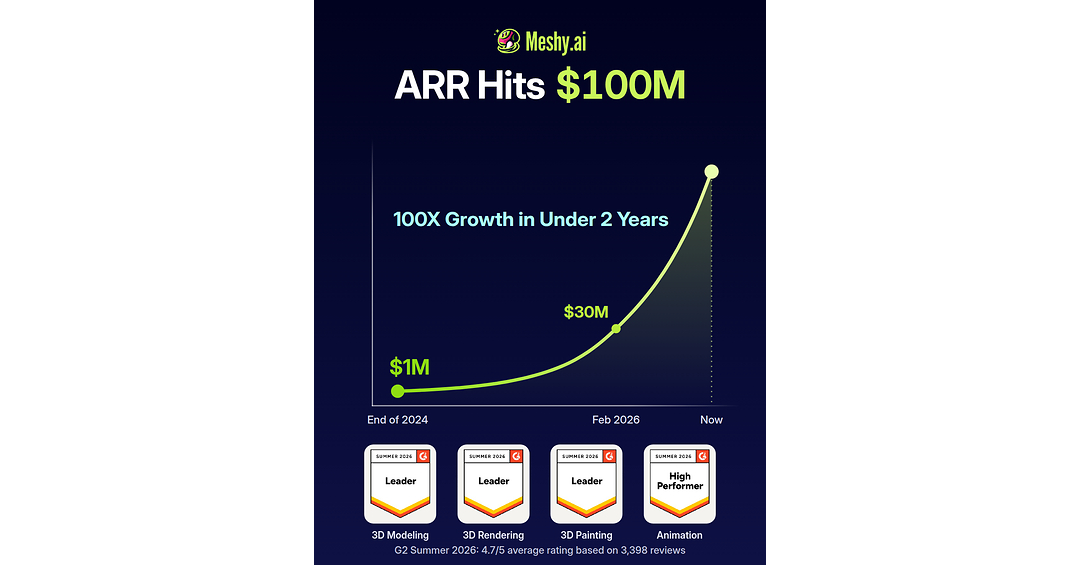
Meshy said ARR surpassed $100 million, up 100x from $1 million in under two years, supported by more than 15 million registered users, 3,000-plus organizational customers and 100 million generated 3D models. The company also highlighted its nearly $400 million July 2026 Series B at a $1.5 billion valuation and launched iOS and Android apps for mobile AI-powered 3D creation. Meshy 7.1 adds Ultra 4K geometry generation, while the company is expanding into real-time interactive worlds and AI-native gaming.
Analysis
The relevant signal is not a public-equity revenue read-through but evidence that 3D asset generation is moving from experimentation into a potentially budgeted software category. If the claimed recurring-revenue scale and enterprise penetration are validated, the near-term pressure falls on labor-intensive game-art outsourcing and lower-end 3D content vendors; the longer-term beneficiary is the game-engine ecosystem, where cheaper asset creation expands the number of economically viable titles and live-service content updates. Unity (U) has the clearest indirect upside through higher creator activity, although it faces a countervailing risk that AI-native workflow layers capture a greater share of creator monetization than the engine itself.
The private valuation implied by the stated financing and ARR is already roughly 15x revenue before accounting for likely elevated inference, compute, and customer-acquisition costs. That makes this a validation event for private AI-creation multiples, not proof of durable free-cash-flow economics; churn, gross margin after GPU expense, and the mix between consumer subscriptions and enterprise API revenue are the critical missing variables. Over 1-3 months, Steam Next Fest engagement and third-party game-studio adoption are the cleaner catalysts; over 6-18 months, the key structural issue is whether frontier-model vendors commoditize image-to-3D capabilities, compressing standalone model pricing and shifting value to proprietary asset libraries, distribution, and workflow integration.
Consensus may overstate the threat to established design software. Adobe (ADBE) and Autodesk (ADSK) retain workflow, collaboration, file-management, and professional compliance moats, while generated geometry still requires editing and production validation in higher-value use cases. The more acute disruption is to undifferentiated asset production, but investors should demand independent evidence of customer spend displacement before extrapolating this into broad multiple compression for ADBE, ADSK, or U.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.82
Key Decisions for Investors
- No direct position: Meshy is private, and the announcement is company-supplied. Add an alert for a secondary-market indication above 20x ARR or below 10x ARR; either would materially reset private-market marks for adjacent generative-media companies.
- Maintain U as a 6-12 month watch-long rather than buying on this news. Enter only after evidence that AI-enabled creation improves paid-seat, runtime, or services guidance; thesis is invalidated by another downward revision to revenue growth or a failure of creator activity to monetize.
- Avoid a blanket short in ADBE or ADSK. Consider a small 6-12 month relative-value expression long ADBE / short U only if U rerates sharply on AI-asset enthusiasm without corresponding bookings acceleration; Adobe's distribution and creative-workflow integration should be more defensible against standalone generation tools.
- Monitor PRLB, SSYS, and VLD for consumer-printing demand evidence rather than treating mobile creation as an immediate revenue catalyst. A sustained increase in paid-materials, printer-unit, or service-bureau volumes over two reporting periods would be needed to justify a long; absent that, the app-driven print thesis is speculative.
More News
- South Korea’s exports hit record high on AI boom
- Asian stocks dip, bonds in focus after torrid September
- US judge approves settlement allowing Paramount to acquire Warner Bros
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Paramount Skydance prices $42 billion debt for Warner Bros deal