
EFC Gases & Advanced Materials Breaks Ground on New Advanced Manufacturing Facility in McGregor, Texas
Source: PR Newswire
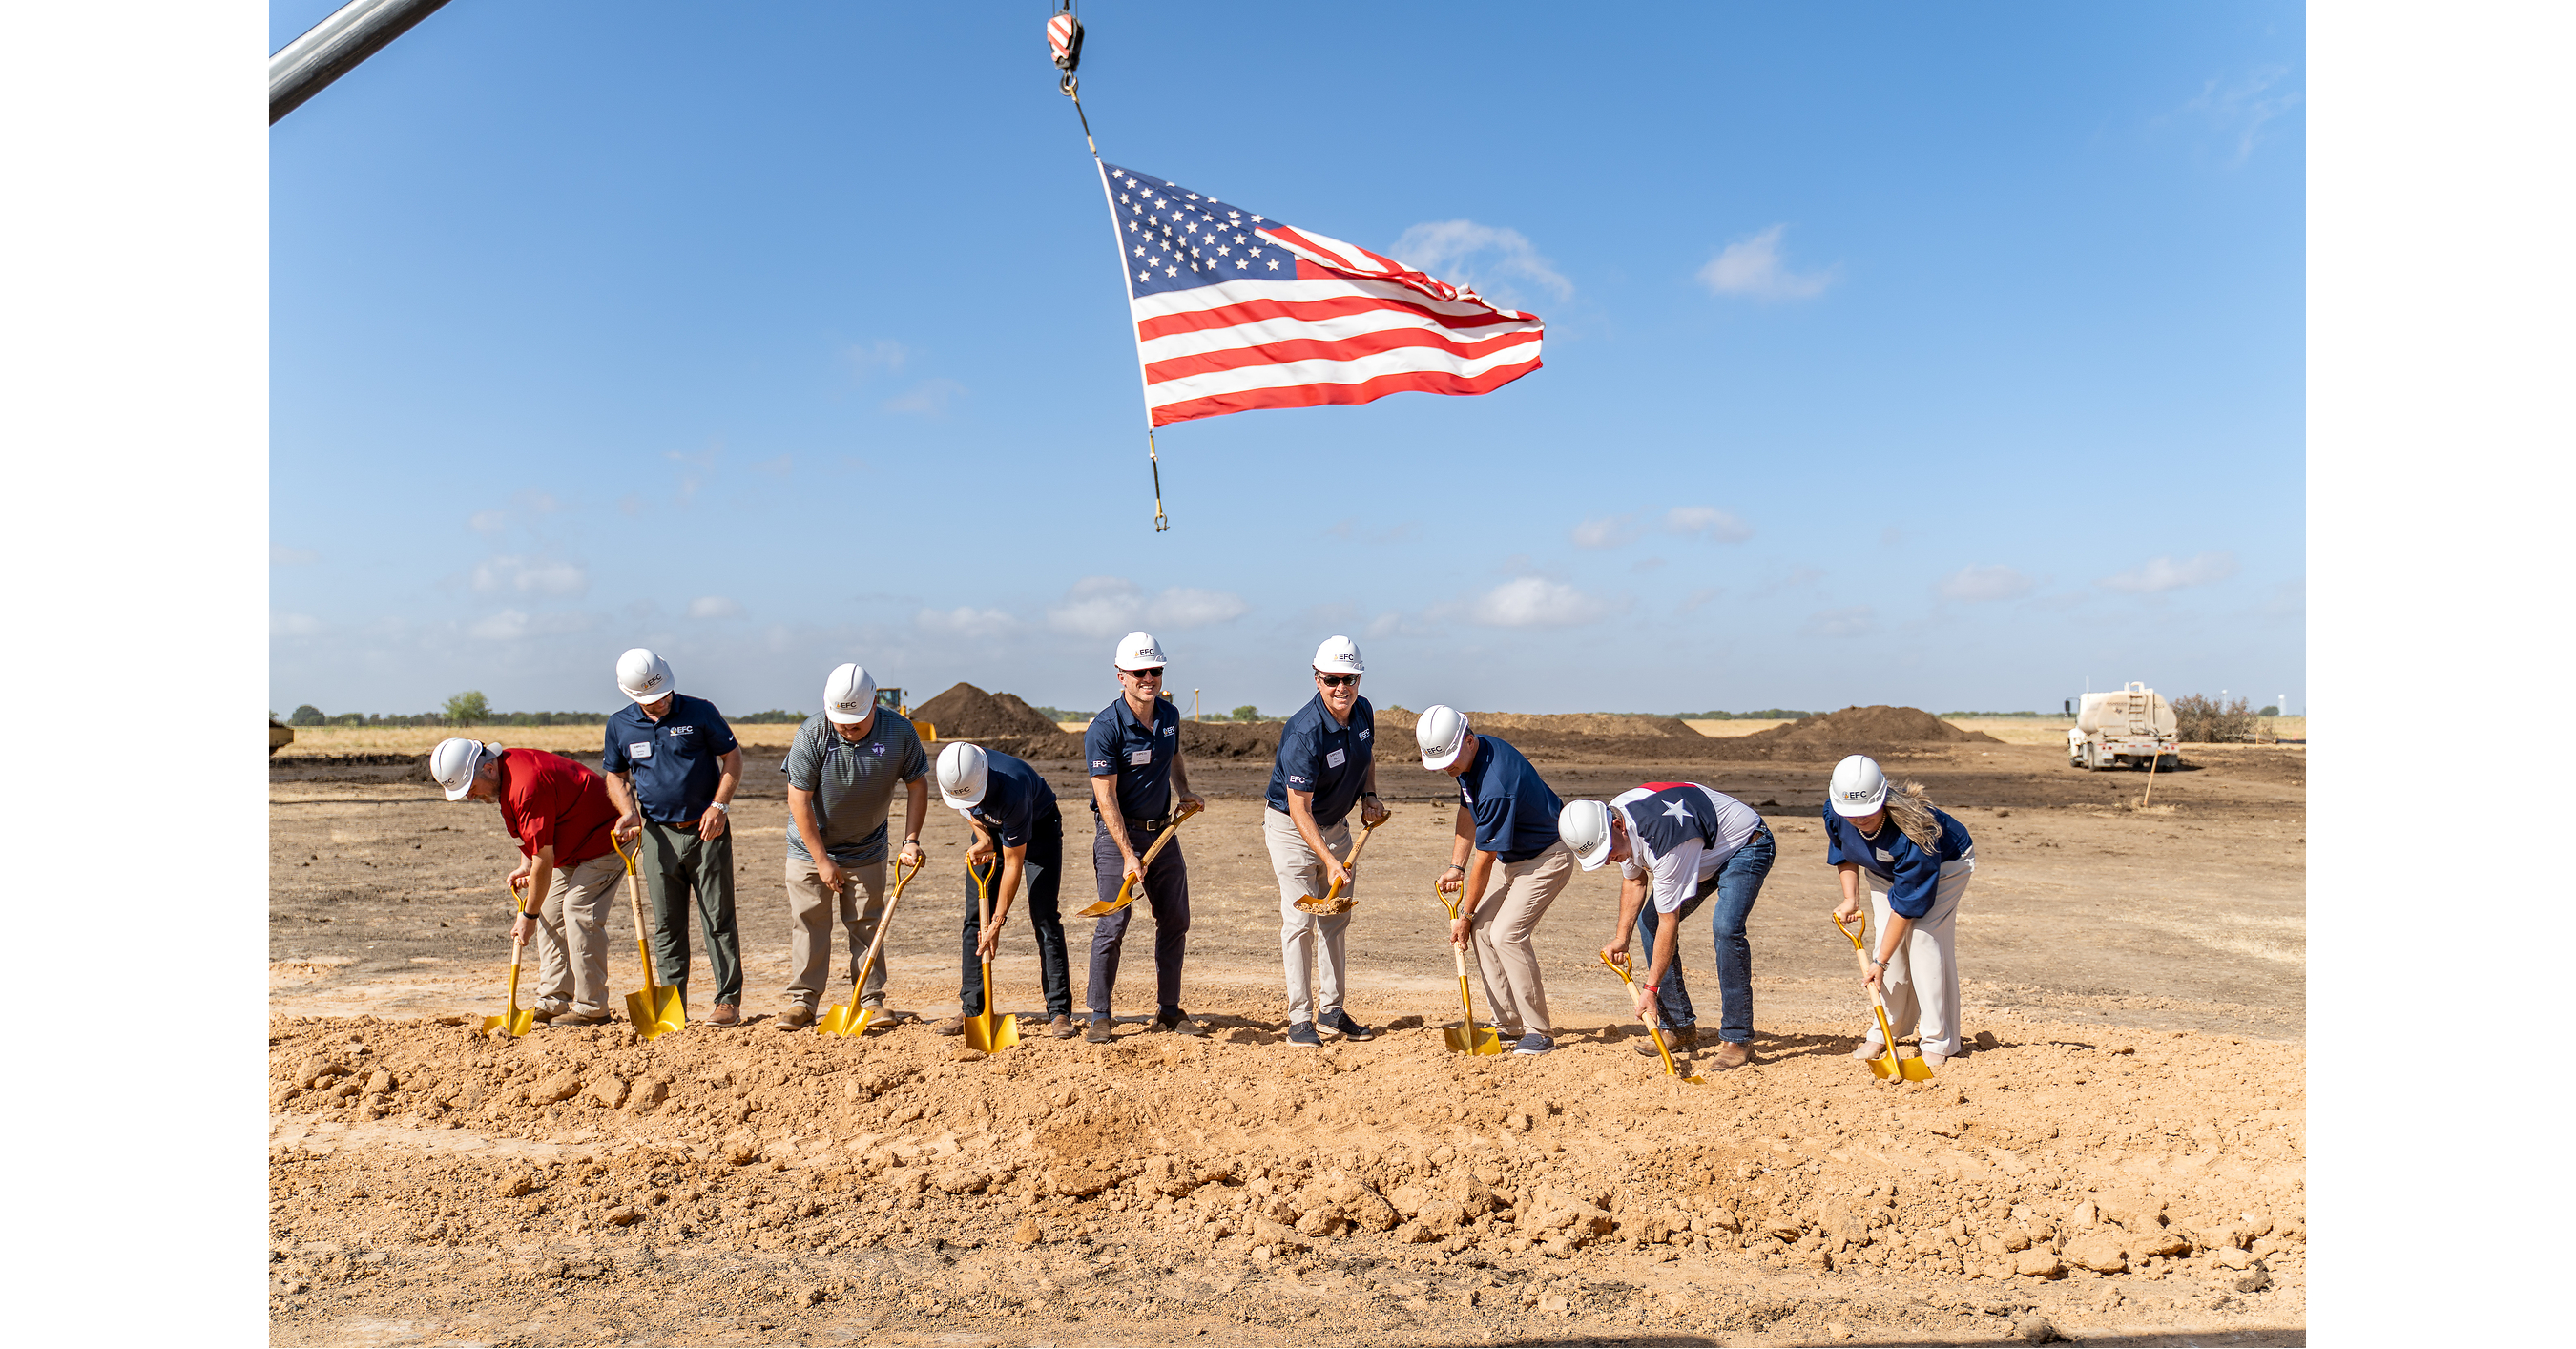
EFC Gases & Advanced Materials broke ground on a 195-acre advanced-manufacturing and distribution campus in McGregor, Texas, intended to expand U.S. production of high-purity materials for semiconductor fabrication. The initial phase is expected to create at least 65 full-time jobs, with further capacity and workforce growth planned as the campus expands. Following Element Solutions' acquisition of EFC earlier in 2026, the facility is positioned to incorporate additional advanced-materials capabilities and support domestic semiconductor supply-chain resilience.
Analysis
This is strategically positive for ESI’s semiconductor-materials platform, but the disclosed operating footprint is too small to support a near-term earnings re-rate without capex, commissioning date, customer qualification, or contracted-volume disclosure. The economic value lies in local bulk-gas availability, faster cylinder/distribution response, and recycling services that can deepen switching costs after a fab qualifies a supplier. That makes the acquisition’s returns more likely to emerge through cross-selling and retention than through an immediately visible standalone revenue contribution.
The more relevant 6-18 month signal is whether ESI converts the site into a broader materials node serving Samsung’s Taylor expansion, Texas Instruments’ Sherman build-out, and ancillary semiconductor supply-chain projects. If customer qualification is secured before those fabs ramp, ESI can gain share from diversified incumbents LIN and AI, while ENTG faces a modestly stronger domestic competitor in adjacent high-purity-material workflows. Conversely, a delayed fab-construction cycle would leave ESI carrying underutilized fixed costs and expose the acquisition to lower-than-expected returns on invested capital.
Consensus may overvalue the domestic-supply-chain narrative relative to the qualification bottleneck: semiconductor customers generally prioritize purity consistency, safety systems, and redundant supply over geographic proximity alone. The actionable catalyst is not the facility opening; it is evidence of multi-year supply awards, incremental semiconductor segment growth above ESI’s baseline, or margin resilience despite start-up costs. Absent those disclosures, this is a watch item rather than a reason to chase ESI on a press-release move.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain ESI as a watch-list long rather than initiating on this announcement; reassess after the next two earnings calls for disclosed project capex, commissioning timing, customer awards, and semiconductor-materials organic growth. Upgrade only if management demonstrates that incremental revenue is contracted or qualified rather than merely capacity-led.
- Use any ESI outperformance versus LIN and AI following supply-chain headlines to consider a relative-value short-term pair: long LIN or AI / short ESI, sized modestly, if ESI’s valuation expansion is unsupported by raised guidance. Cover if ESI discloses a named fab supply agreement or lifts medium-term margin/ROIC targets tied to the acquired business.
- Set an alert around Samsung Taylor and TI Sherman construction/ramp milestones over the next 12-24 months. A material acceleration in either program would improve ESI’s local-utilization outlook; further delays would be a negative read-through for ESI’s new fixed-cost base and a reason to avoid adding exposure.
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Factbox-Key issues for this week’s Trump-Xi summit in Washington
- Brazil election: Lula and Flavio Bolsonaro tied in latest polls