
PETER PIPER PIZZA ANUNCIA UNA INVERSIÓN DE 1 MILLÓN DE DÓLARES EN NUEVOS JUEGOS Y APERITIVOS DE EDICIÓN LIMITADA PARA DISFRUTAR DE UNA NOCHE FAMILIAR INOLVIDABLE
Source: PR Newswire
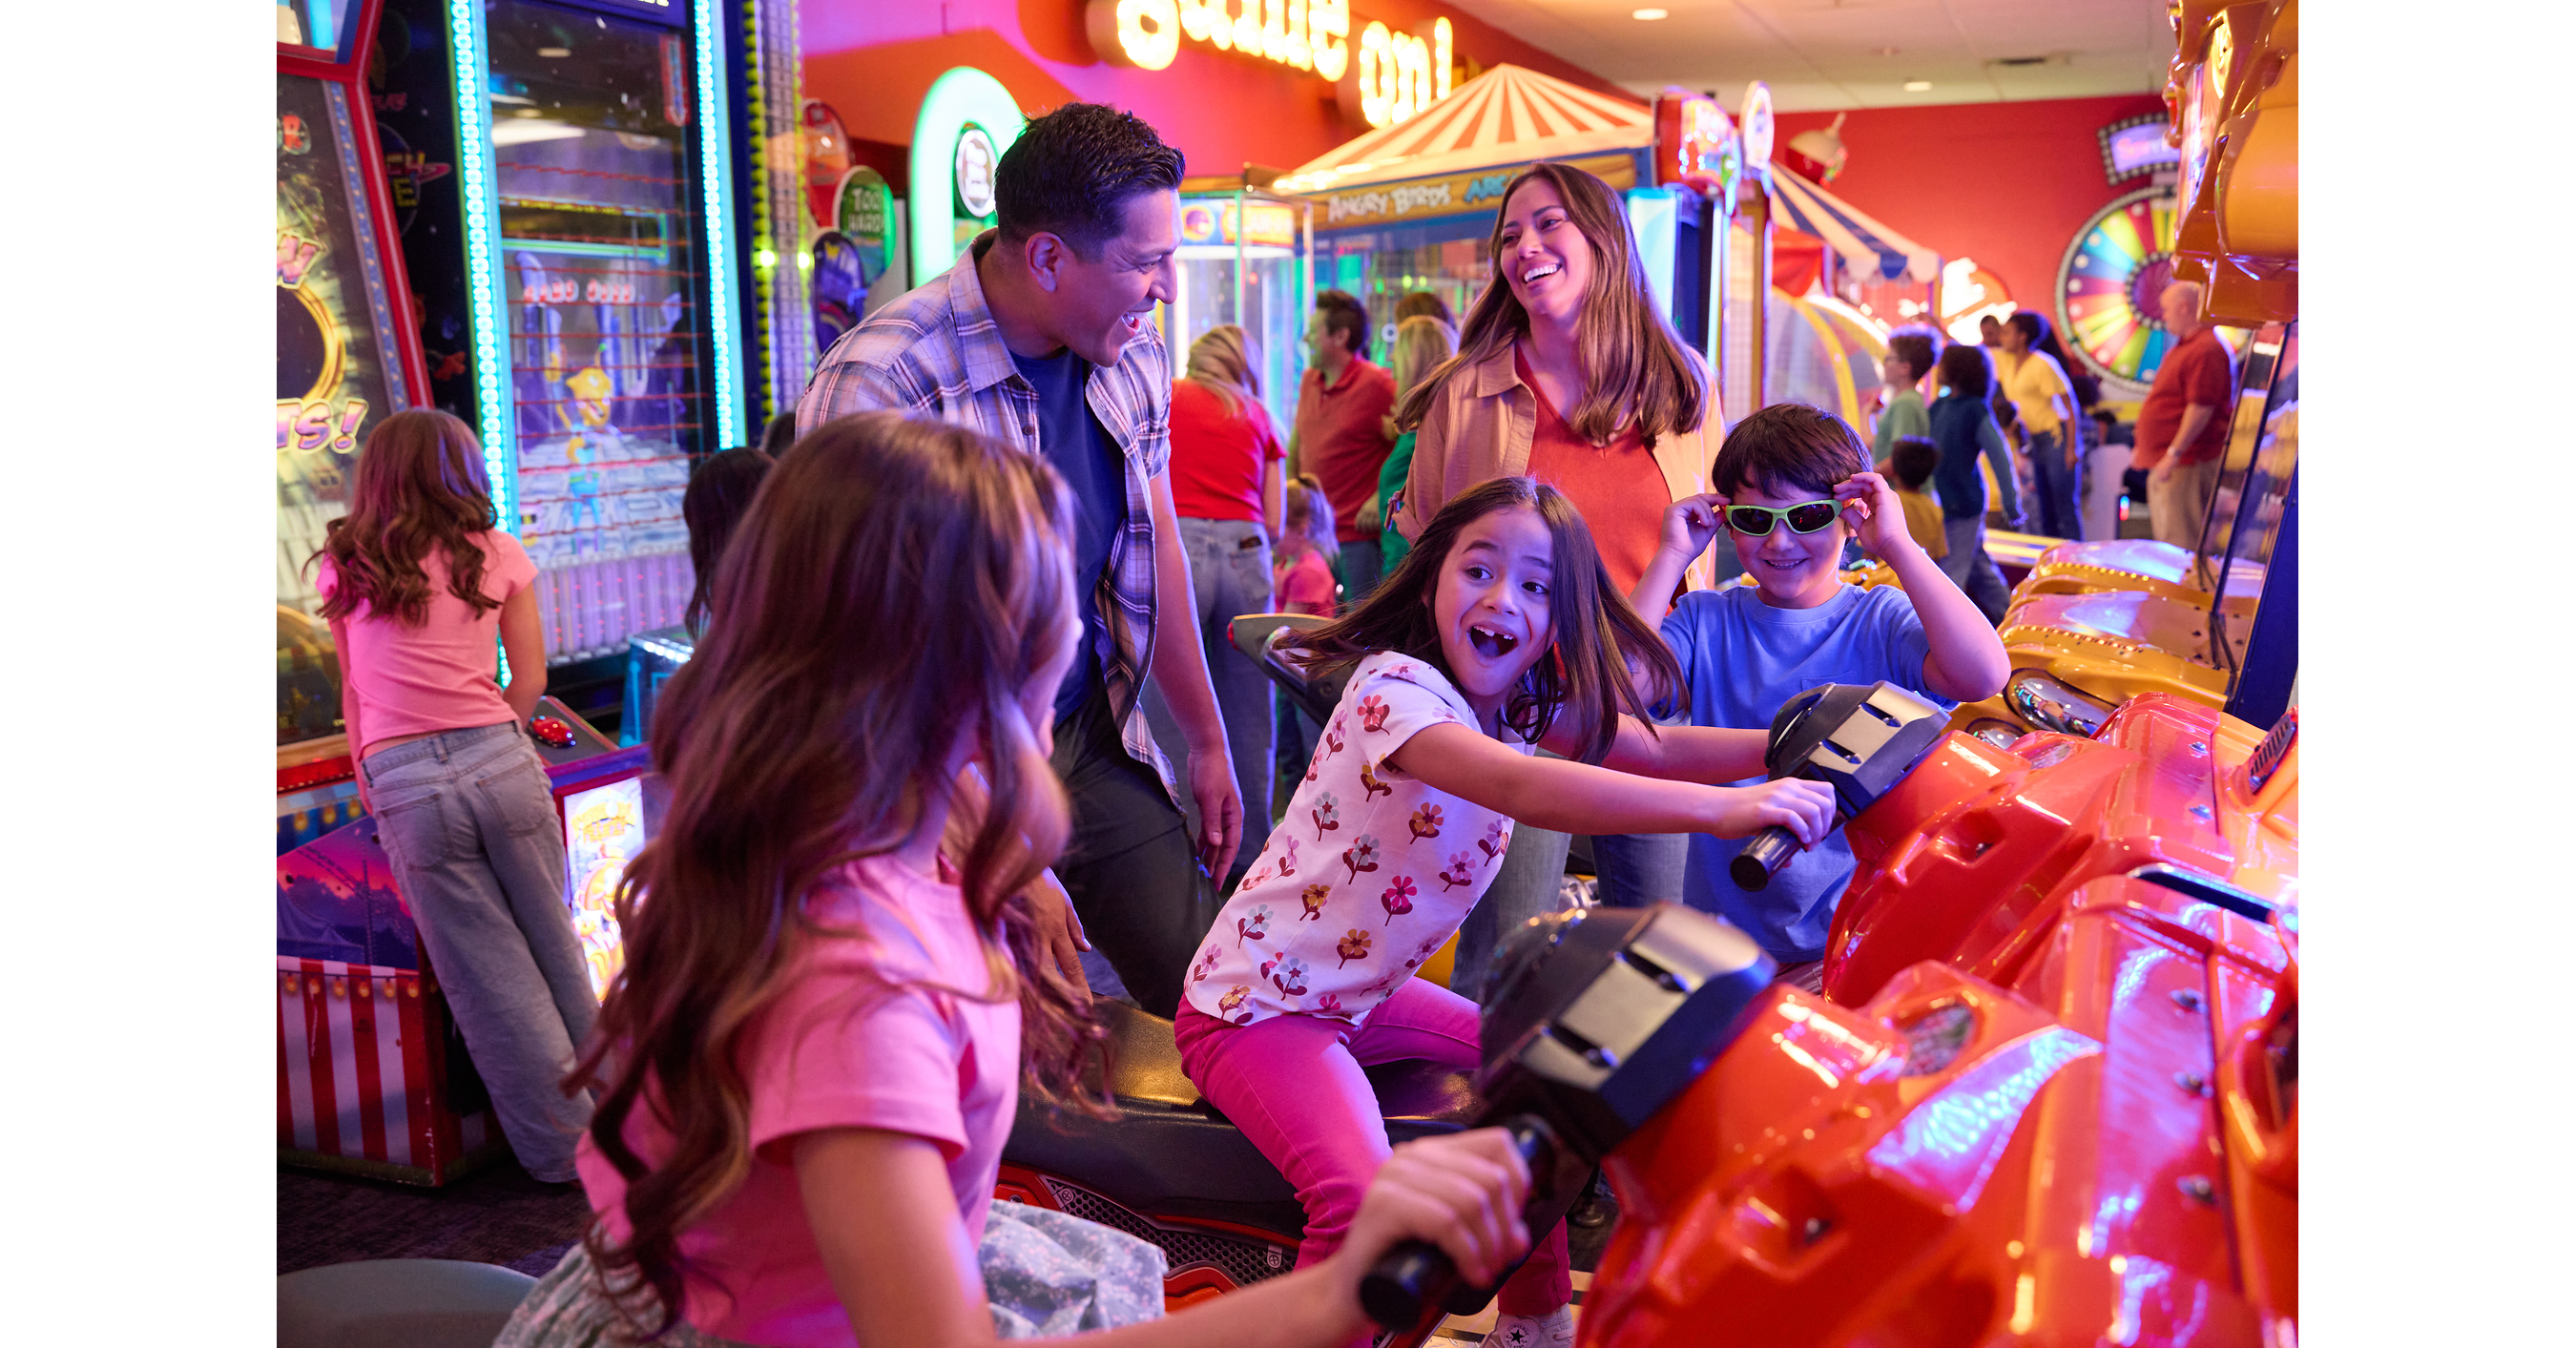
Peter Piper Pizza anunció una inversión de 1 millón de dólares para renovar sus juegos de arcade en más de 40 locales de Arizona y Nuevo México, con +100 nuevos juegos y máquinas de garra antes de fin de mes. Además, lanzó 3 platos premium por tiempo limitado (incl. palitos de queso cheddar, ensalada de mandarina y arándanos, y crujiente de fresa) en establecimientos participantes. También destacó la oferta Double Up XL: dos pizzas extragrandes con un ingrediente por $29.99. En conjunto, es una actualización promocional/operativa de bajo impacto potencial en mercado.
Analysis
This reads as defensive traffic retention, not a meaningful growth step-up. The spend is small enough to be absorbed at the store level, but the real question is whether it raises visit frequency and arcade attachment enough to offset promo dilution; if not, it is just a margin drag dressed up as reinvestment. The best-case outcome is a modest lift in birthday/party mix and off-peak utilization, which matters more than headline menu innovation.
The second-order winners are arcade hardware, redemption, and licensed-content vendors, plus any suppliers tied to premium toppings/desserts that carry better gross margin than the bundled core product. The likely losers are local family pizza/entertainment operators that cannot match the experience layer, but the broader public-equity read-through is limited: the cleanest proxy is PLAY, where this reinforces the need to keep spending to defend share in experiential dining rather than signaling a new demand cycle.
The catalyst path is 1-2 quarters, not days: we need traffic, check growth, and margin data to see if this is incremental or merely a substitution of discounted visits for full-price ones. The contrarian view is that management is likely reacting to soft wallet-share competition, so the market may be overinterpreting a routine refresh as evidence of durable brand strength. Falsifiers are straightforward: flat/negative guest counts, lower average ticket, or no operating margin improvement by the next reporting cycle would make this thesis look promotional rather than accretive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No standalone listed-equity trade from this release; treat it as a watch item until the next same-store sales and margin print confirms whether arcade reinvestment is actually lifting traffic.
- If PLAY rallies on perceived read-through, consider fading strength over a 1-3 month horizon; this is more likely a defensive capex signal for the category than a clean demand inflection.
- Set an alert for >2% traffic improvement or >100 bps margin expansion at CEC/Peter Piper comps; only then does the reinvestment justify a bullish re-rating of experiential dining exposure.
- Avoid extrapolating this into a broader consumer-demand signal for XLY or restaurant baskets; if the next comp data is weak, the more likely outcome is promotional pressure rather than sector-wide demand improvement.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.