
Latham Adds Experienced Partner to Highly Regarded Fund Finance Practice
Source: PR Newswire
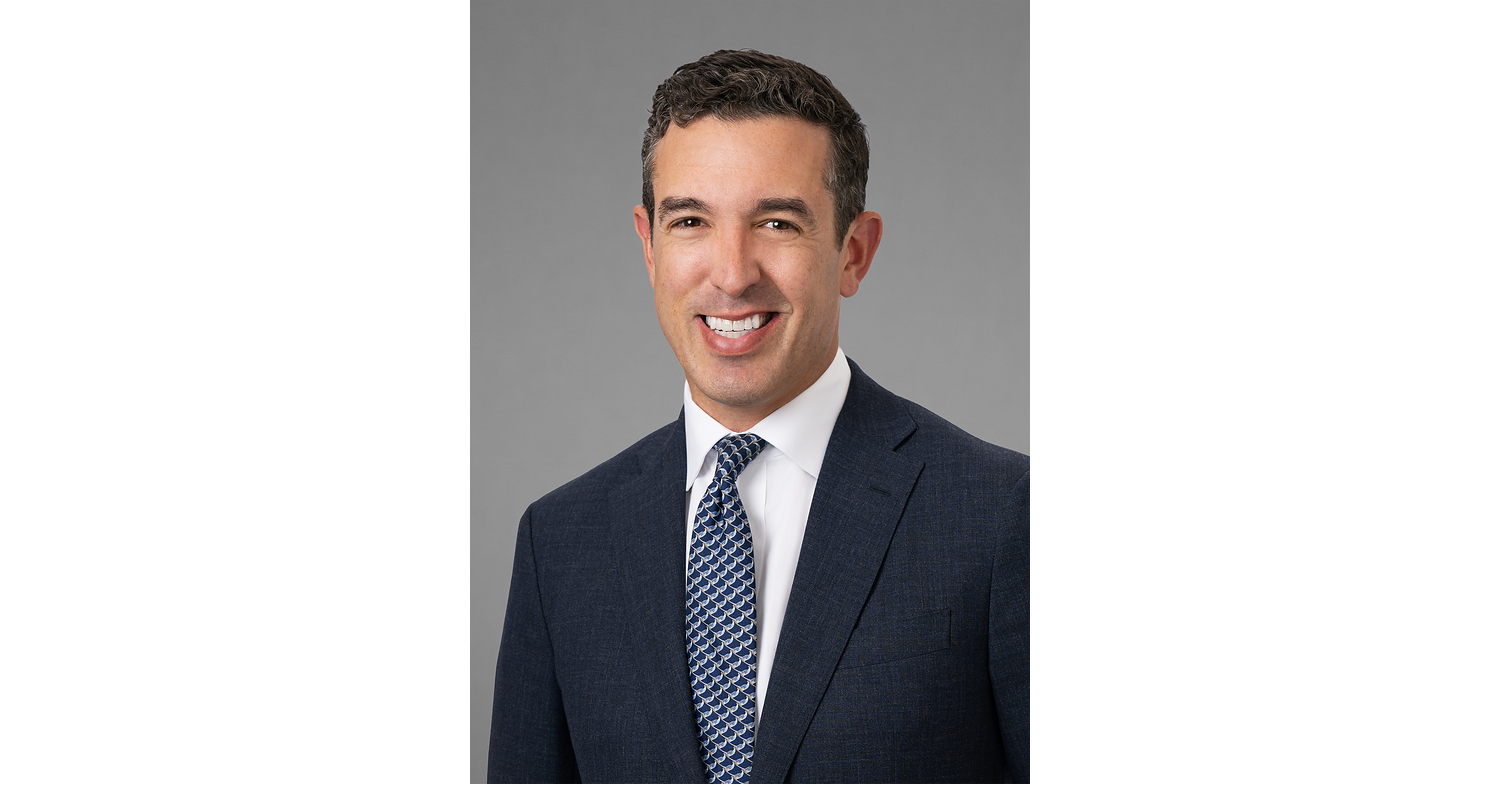
Latham & Watkins hired Ryan Plasky from Fried Frank as a Washington, D.C.-based partner in its Banking & Private Credit Practice, strengthening its fund-finance capabilities. Plasky advises on subscription, NAV and hybrid facilities, rated-note feeders, and real-estate fund financings. The move reflects Latham's continued investment in private-capital financing, but is unlikely to have material public-market impact.
Analysis
This is not a public-markets catalyst and does not justify a directional trade in listed asset managers, banks, or law-firm-adjacent names. The only investable read-through is incremental evidence that NAV, subscription, and hybrid fund-finance structures remain strategically important as private-market sponsors seek liquidity without realizing assets at impaired valuations.
The second-order implication is constructive for scaled alternative managers with large, seasoned portfolios and diversified lender relationships—BX, APO, KKR and ARES—because they can access portfolio-level financing more efficiently than smaller GPs. That advantage can extend fund duration and preserve fee-paying AUM, but it also raises embedded leverage and valuation-opacity risk; markets are likely to reward disclosed, conservatively structured facilities and penalize managers whose distributable earnings depend on repeated balance-sheet solutions.
Over the next 6-18 months, the relevant catalyst is not legal-market hiring but whether private-credit spreads, bank balance-sheet capacity, and sponsor exit activity improve simultaneously. A reopening of M&A and IPO exits would reduce demand for NAV borrowing and be a cleaner positive for realizations; a renewed risk-off episode could expose covenant, collateral-mark and refinancing sensitivity in highly levered fund structures. Monitor quarterly disclosures on financing against fund assets, realizations versus deployment, and insurance/fund-finance lending exposure rather than treating industry promotional language as evidence of volume growth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate trade: classify as low-impact industry color; do not initiate positions based on this announcement.
- Maintain a 6-12 month quality tilt within alternatives: long BX or ARES versus a basket of smaller, less-liquid alternative managers if quarterly reporting shows superior realization rates and stable fee-related earnings. Falsify if fundraising slows materially or realizations fail to recover despite increased financing activity.
- Use APO as a watch item rather than a direct fund-finance proxy: assess Athene credit-spread exposure and private-credit origination margins before adding. A meaningful widening in investment-grade spreads or deteriorating private-credit marks would outweigh any benefit from greater structured-finance demand.
- For credit books, monitor listed BDCs with meaningful sponsor-finance and asset-based lending exposure, including ARCC and OBDC, for unusually rapid portfolio growth or declining interest coverage. Avoid adding risk if NAV marks weaken while leverage rises; that combination signals financing is substituting for exits rather than bridging to them.
More News
- FedEx beats expectations, raises outlook in first report since calendar adjustment
- Samsung Electronics third-quarter profit in line with estimates amid rising demand for AI memory chips
- Fed leaves rates unchanged: What it means for credit cards, mortgages, auto loans and savings accounts
- Japan’s Two-Year Bond Sale Demand Stronger Than 12-Month Average
- Warsh says politics played no role in Fed’s rate decision by group he is ’honored’ to lead
- Microsoft reveals strong cloud growth amid financial reporting overhaul
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper
- Quartr Alternatives for Institutional Research Teams