
Lightstone DIRECT Surpasses $225 Million in Total Investment Volume Less Than a Year After Launch
Source: PR Newswire
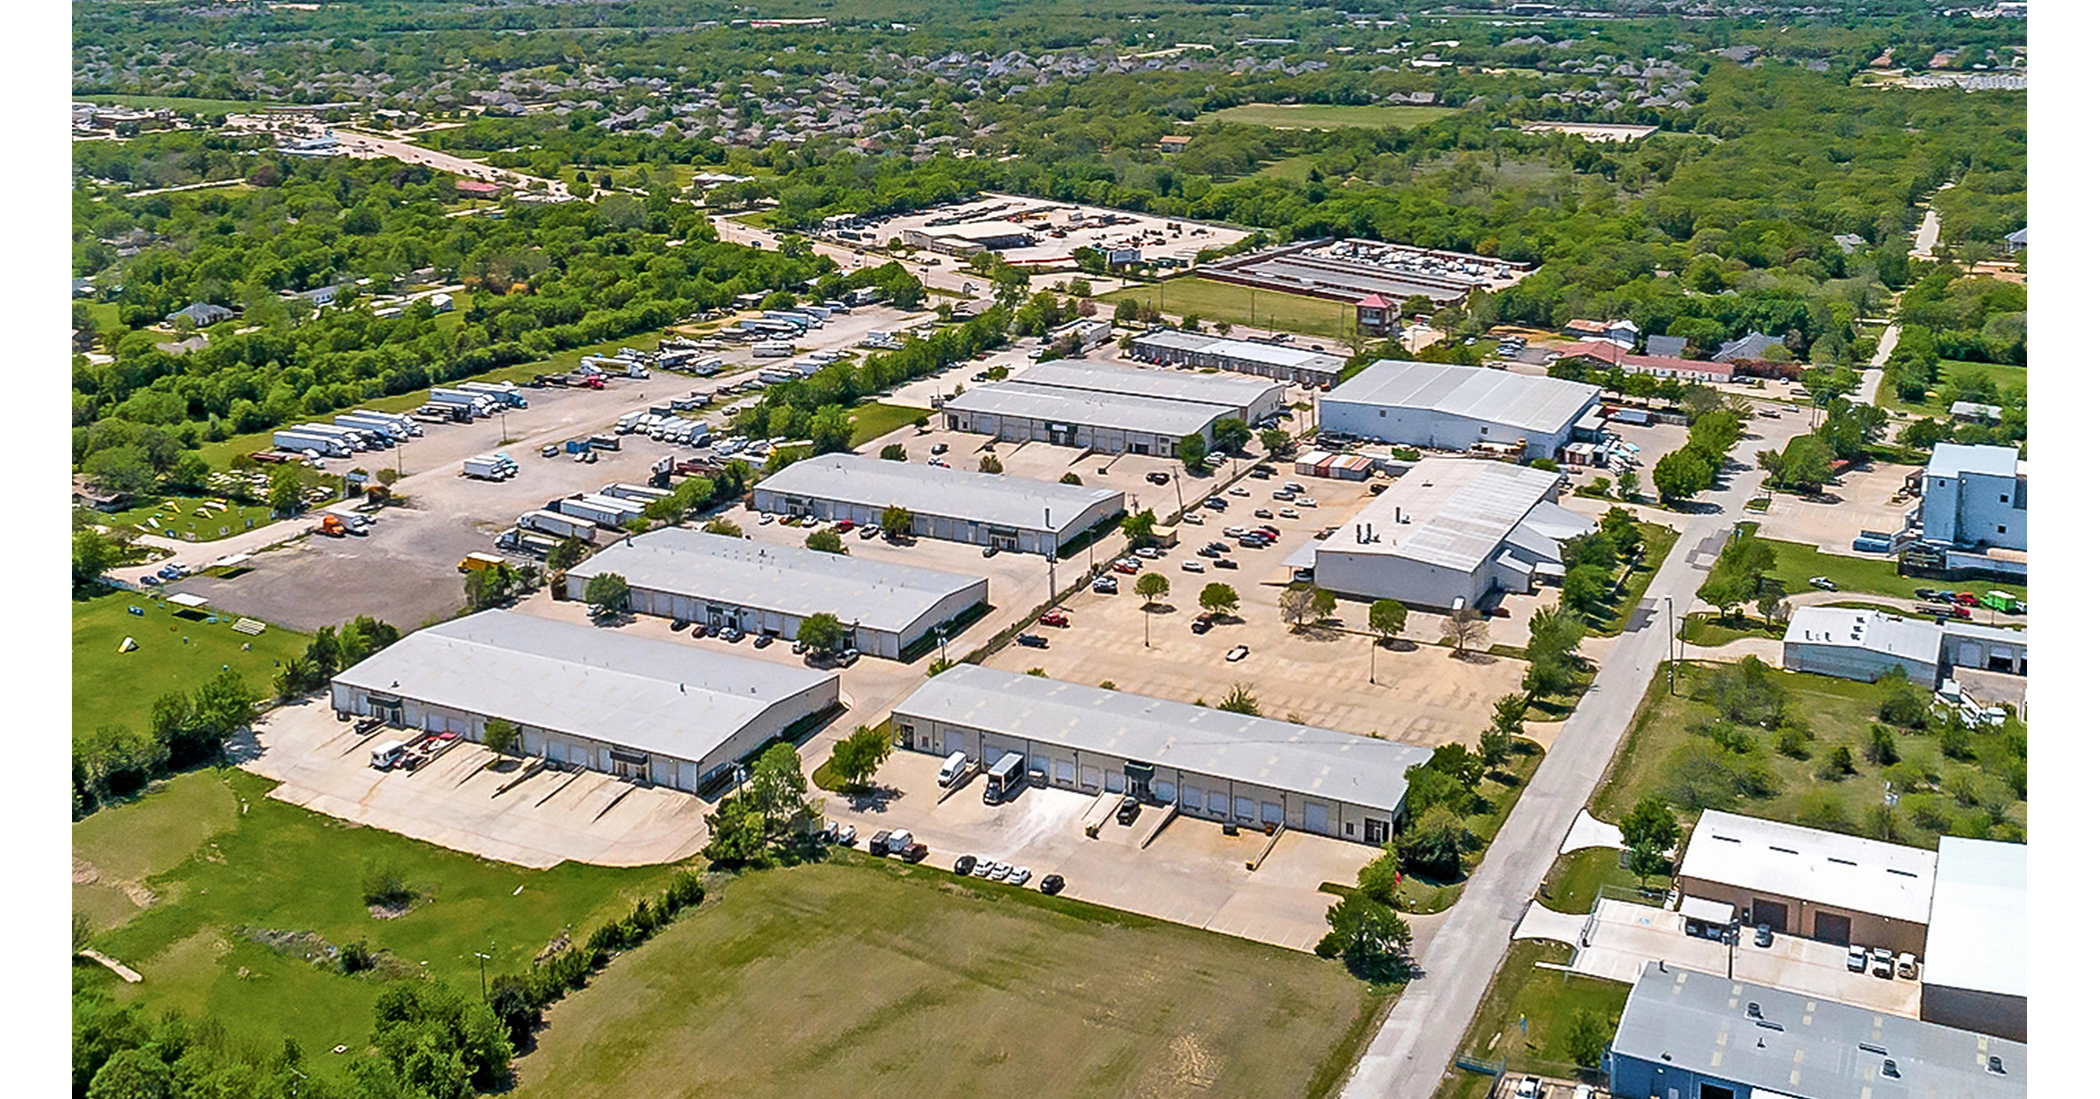
Lightstone DIRECT opened its fourth offering, Arlington Industrial, bringing total platform investment volume to approximately $225 million less than a year after launch. The 170,390-square-foot Dallas-Fort Worth shallow-bay industrial asset is 95% leased to 24 tenants and was acquired at roughly a 45% discount to estimated replacement cost. The platform has met every targeted monthly distribution since beginning distributions in April, while DFW led U.S. industrial net absorption in the first half of 2026.
Analysis
This is not a direct earnings catalyst for NMRK, JLL, or SPG. The more relevant signal is incremental high-net-worth capital being routed into single-asset private real estate rather than listed REITs: if replicated broadly, that marginally supports transaction liquidity and asset-price discovery while competing with public REITs for yield-oriented investor capital. The reported basis discount is not independently verifiable and should not be extrapolated to broader Dallas-Fort Worth industrial valuations without comparable sale, debt-cost, and in-place-versus-market rent data.
The potentially investable second-order effect is in shallow-bay industrial: fragmented tenant rosters generally create higher leasing and operating intensity, but can produce superior mark-to-market rent capture when supply is constrained. That exposure is largely inaccessible through the named public tickers; broad industrial REIT proxies such as PLD and EGP have different large-box and coastal-market sensitivities. Over the next 6-18 months, sustained small-business formation and falling financing costs would support this niche, while a regional slowdown would expose rollover risk faster than headline occupancy implies.
For brokers, a revival in private-market equity availability can improve 2027 transaction pipelines, but NMRK and JLL only benefit when capital converts into completed acquisitions, financings, and dispositions. The near-term market implication is therefore modest: private placements may be absorbing assets that otherwise would remain illiquid, yet the disclosed scale is too small to alter brokerage revenue estimates or public REIT valuation multiples. Consensus should resist treating sponsor monthly distributions as evidence of durable asset-level cash-flow coverage until leverage, debt maturity, tenant concentration, and distribution sources are disclosed.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No directional trade in NMRK, JLL, or SPG on this announcement; the financial linkage is immaterial. Reassess JLL/NMRK only if quarterly capital-markets backlog, U.S. industrial transaction volumes, and debt-placement revenue accelerate for two consecutive quarters.
- Maintain any industrial-real-estate exposure through liquid listed vehicles rather than attempting to infer a public-market read-through from one private transaction. For PLD/EGP, use DFW rent-growth and lease-renewal spreads as confirmation; reduce exposure if industrial same-store NOI guidance turns negative or financing spreads widen materially.
- Create a private-credit watch item: obtain property-level leverage, floating-rate hedging, tenant rollover schedule, and distribution coverage before assigning value to the reported yield. A debt maturity inside 24 months or distributions exceeding recurring FFO would invalidate a bullish cash-flow interpretation.
More News
- Commerce Secretary Howard Lutnick reports more than $250 million in income last year
- China’s Property Crisis: From Evergrande Collapse to Beijing’s Latest Measures
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Why is Nidec stock plunging today?
- Why is Kioxia stock rallying today?