
JAMS Software Launches JAMS Incident Management for On-Call Alerting and Escalation
Source: PR Newswire
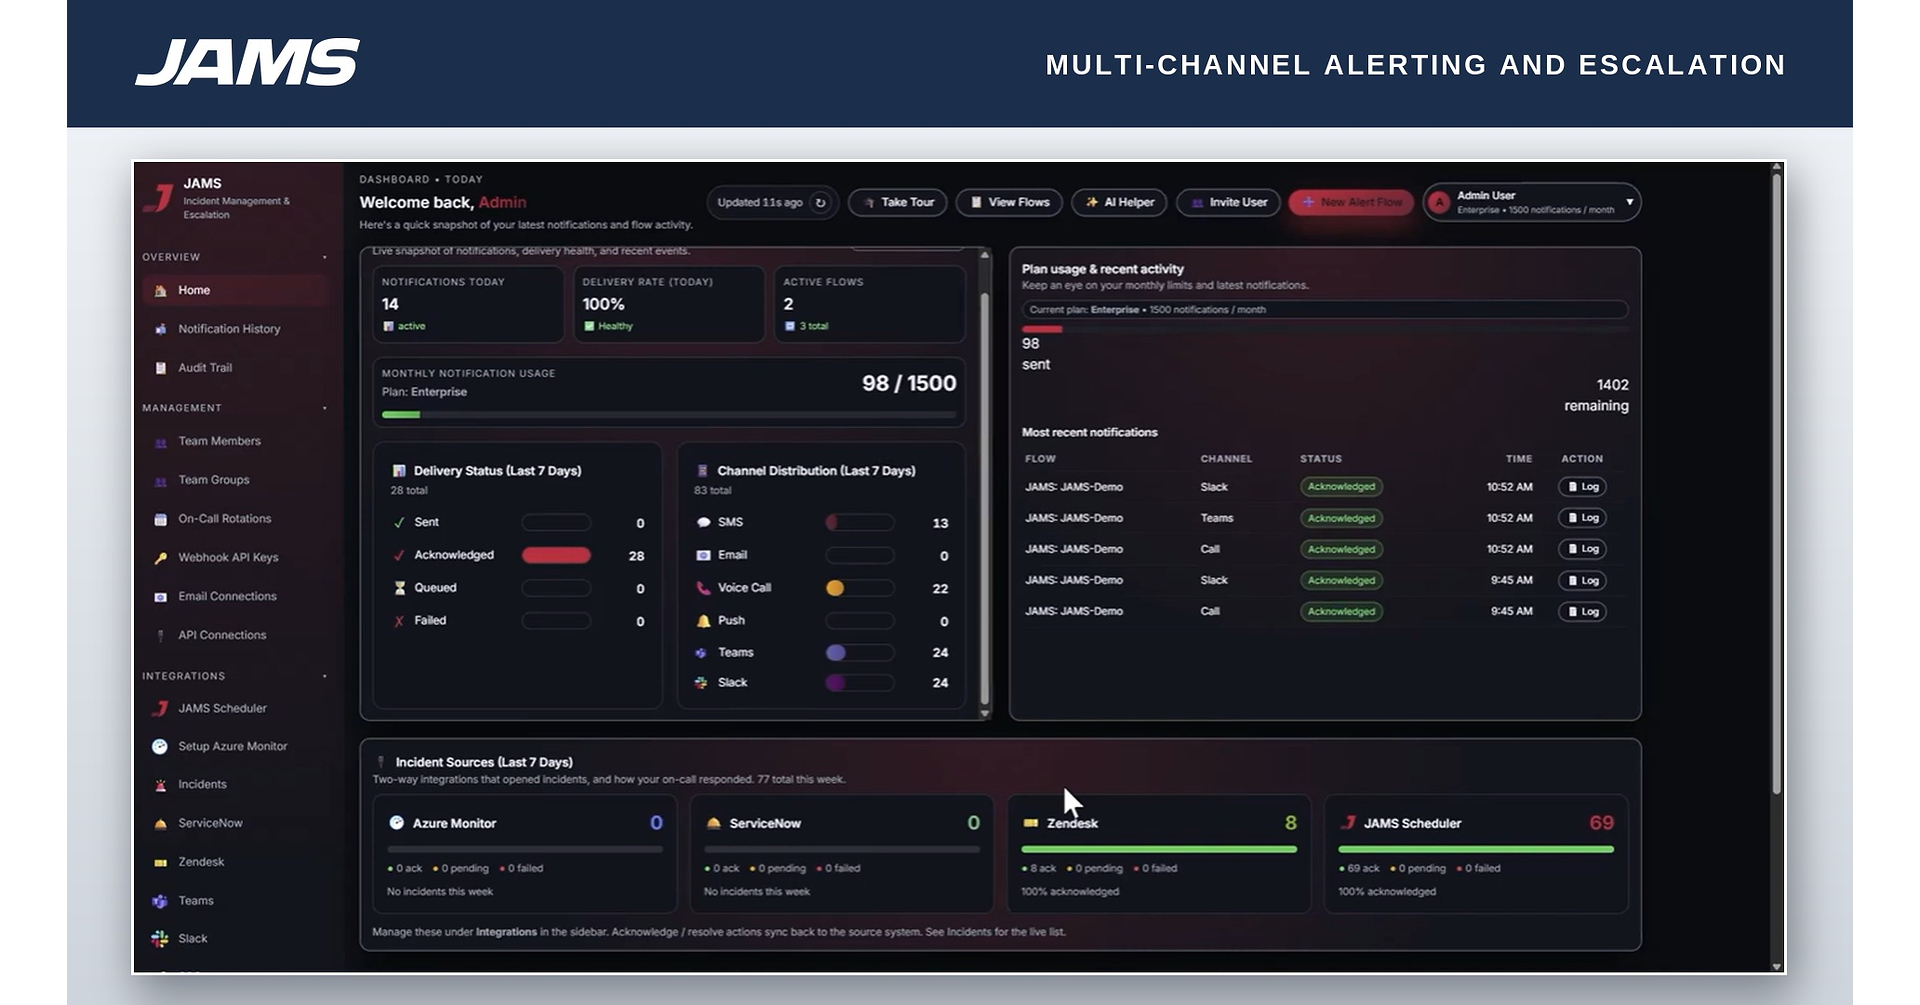
JAMS Software launched JAMS Incident Management, an on-call alerting and incident escalation product generally available on Sept. 1, 2026, after early access starting Aug. 1. Pricing is $6/user/month (Starter, up to 25 users) and $16/user/month (Professional, up to 50 users) billed annually, with on-call scheduling/escalation included rather than add-on modules. The software accepts alerts via email/webhook/API and escalates across voice, SMS, push, email, Microsoft Teams, and Slack, with native integration to JAMS Scheduler for automated incident creation and job restarts.
Analysis
This is more a pricing-and-distribution event than a true product-cycle shock. A low-friction, sub-$10 seat entry point pushes incident response toward commodity status at the bottom end of the market, which can compress ACVs for point vendors but does little to the economics of enterprise workflow platforms. The real moat in this category is not the alert itself; it is the surrounding governance, auditability, and cross-system workflow, so incumbents with broader suites should retain pricing power unless buyers start ripping out adjacent modules.
The clearest named beneficiary is MSFT. Native alignment with Azure Monitor, Teams, and Entra makes Microsoft the default control plane for organizations already standardized on its stack, and this kind of tool tends to increase surface area rather than displace it. The incremental revenue impact is not in software list price; it is in stickier Azure consumption and higher switching costs around the Microsoft identity/collaboration layer. NOW is the only named ticker with any plausible negative read-through, but the risk is mostly seat-level and tactical unless this category starts cannibalizing broader ITSM workflows.
Contrarian view: the market may overestimate the competitive threat because self-serve pricing can expand the funnel without taking meaningful share from premium enterprise vendors. Over 1-3 months, the right question is conversion, not launch quality: does the free tier create paid expansion, or just a cheap alternative for small teams? Falsifier for the bearish NOW read would be no slowdown in enterprise ITSM retention or attach rates on the next earnings cycle; if those metrics hold, this remains a niche commoditization story, not a platform disruption.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- Modest long MSFT / short NOW pair for 4-8 weeks on any market overreaction to the launch; thesis is that Microsoft captures ecosystem stickiness while NOW faces at most marginal price pressure. Risk/reward: ~2:1 if NOW de-rates on mix concerns, stop if NOW guidance or net retention improves.
- Do not short NOW outright here; instead set an alert for the next two earnings prints on enterprise workflow/ITSM attach rates and billings commentary. If those deteriorate, the competitive read-through becomes actionable; absent that, the launch is noise.
- No trade in GOOGL or IBM for now. Their mention here is plumbing-level integration, not meaningful revenue exposure; only revisit if the product expands materially into Google Workspace or IBM-managed legacy operations.
- If MSFT weakens on a broad software selloff, use it to add exposure rather than fade it: the launch slightly reinforces Azure/Teams/Entra lock-in, which should matter more over 6-18 months than the launch itself.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- TSMC chip capacity is ‘fierce’ battleground for AI customers, amid record quarter
- Factbox-CoreWeave’s AI contracts and the lenders financing its build-out
- Nvidia CEO Downplays CoreWeave Concerns After Risk Gauge Soars
- Nvidia’s European spending spree is about much more than Europe
- Here's our monthly update on our 32 stocks, including 2 more names to buy