
Unisound 2026 Interim Results: Revenue Up 38.7% YoY, Token Business Surges 760%, Large-Model Commercialization Accelerates Across the Board
Source: PR Newswire
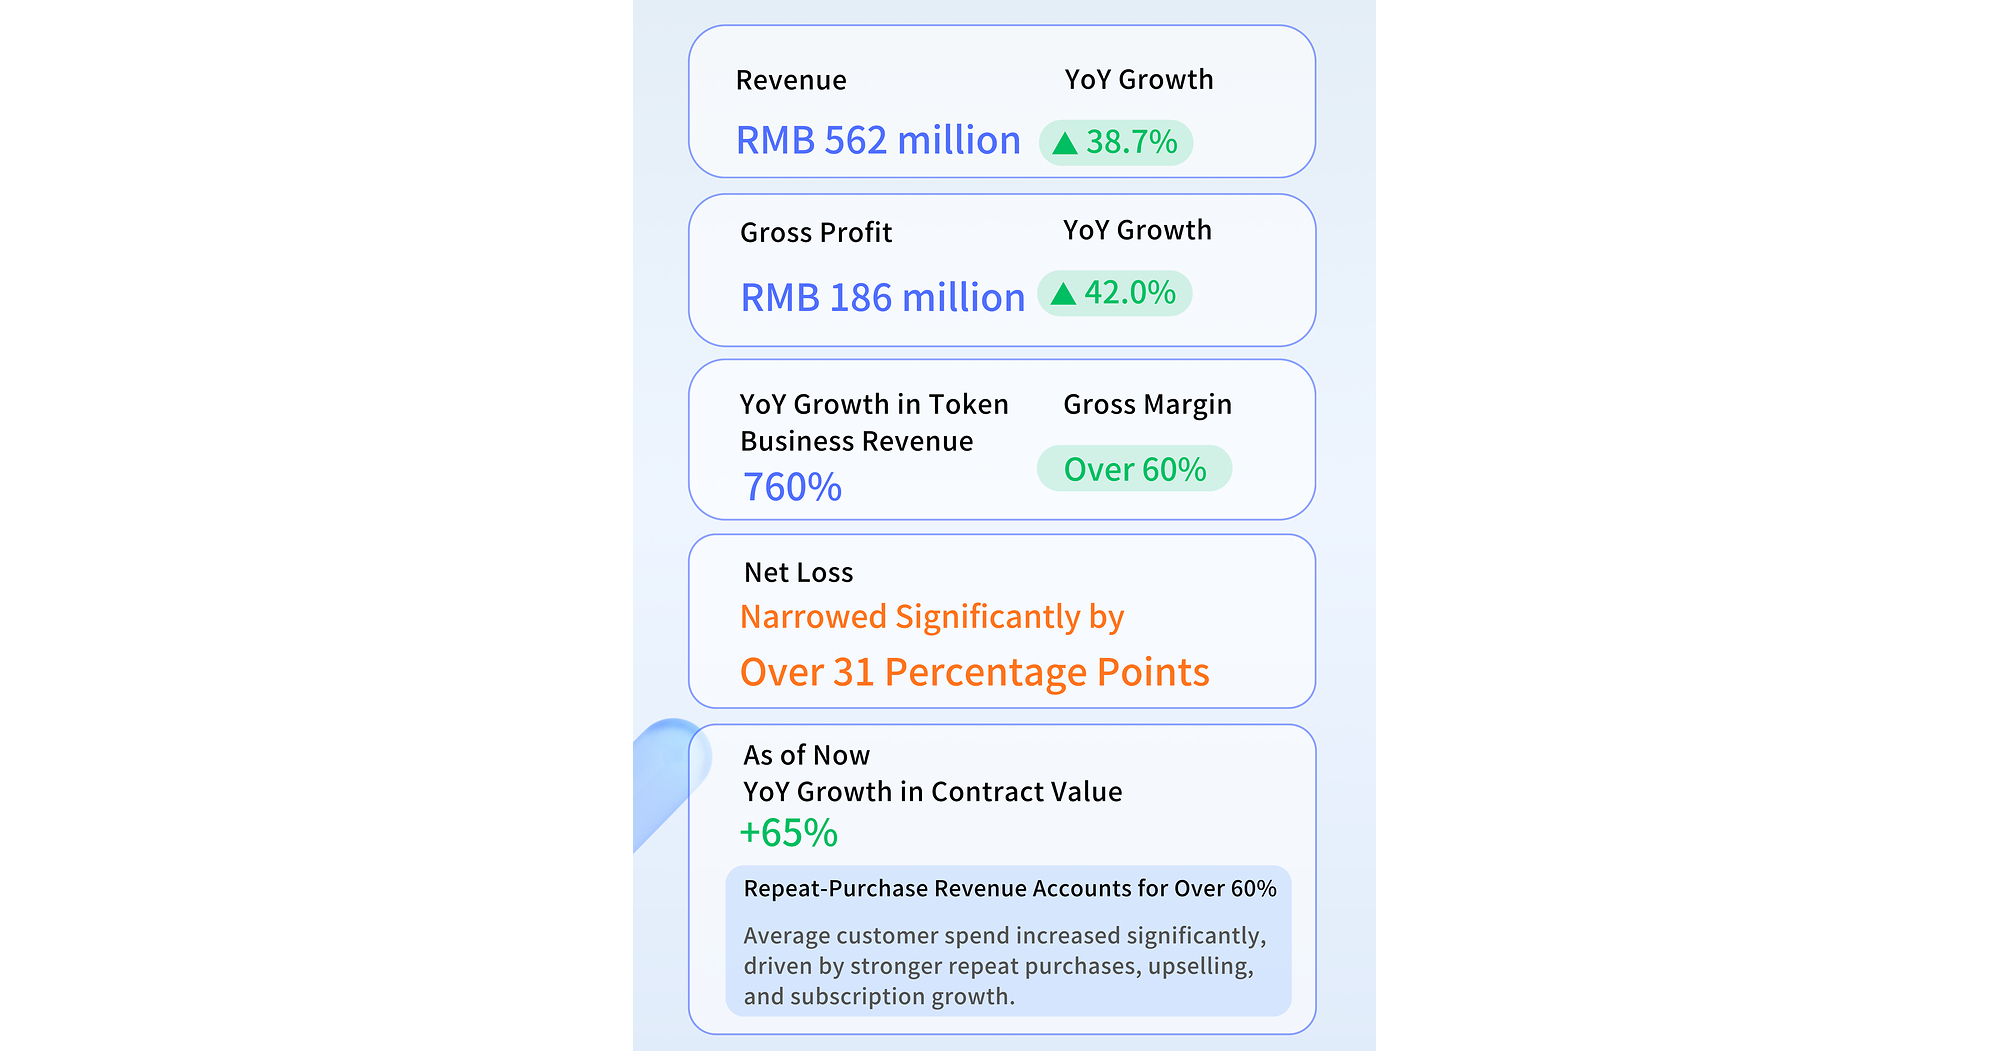
Unisound reported 1H26 revenue of RMB 562 million, up 38.7% YoY, alongside a ~760% YoY jump in token business revenue and >60% gross margin. The company shifted toward an AI platform model with 3 core segments (Enterprise AI Services revenue RMB 478 million, +35.7% YoY; Edge AI RMB 53.8 million, +9.2% YoY) and improved operating efficiency, with admin expenses down 37.8% and net loss margin narrowing by 31pp YoY. Contract value rose 65% YoY to support a >RMB 1.5 billion order backlog and cash reserves approaching RMB 1.0 billion, while U2 strengthened performance across top-tier LLM benchmarks.
Analysis
The key mechanism is not “AI growth” in the abstract, but the migration from one-off implementation economics to a reusable software stack. If Unisound can keep module reuse rising, incremental revenue should carry materially higher gross margin and lower delivery cost, which is exactly what the market will pay up for in a China software name. That said, the absolute token revenue base is still small enough that the rerating case depends more on sustained bookings and collection quality than on any single quarter’s growth rate.
Second-order effects: this is negative for smaller AI integrators that still rely on bespoke projects and low reuse, because enterprise buyers will benchmark against a platform model with recurring usage fees. It is potentially positive for cloud/compute and edge hardware partners if usage truly scales, but it also raises the bar for Chinese model vendors broadly — peers will need to show similar conversion from benchmark performance to monetizable workflows, or investors will start stripping out “research prestige” from valuation.
The contrarian risk is that the market may be extrapolating a classic China AI playbook: rapid headline growth, then slower cash conversion and longer sales cycles once the easy pilots are done. The falsifier over the next 1-3 months is weak H2 contract conversion or any sign the backlog is less cash-generative than implied; over 6-18 months, the bigger risk is that enterprise demand stays concentrated in a few verticals and the platform thesis remains a narrow services business wearing AI language. Regulatory and data-compliance friction is the other tail risk, especially if cross-border edge shipments face scrutiny.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Key Decisions for Investors
- Long 09678.HK only on post-earnings weakness, not strength: use a 5-10% pullback as entry if volume remains supportive. Target a 3-6 month re-rating if repeat purchases and backlog conversion hold; stop out if next update shows revenue growth decelerating below 25% YoY or gross margin slipping.
- Pair trade: long 09678.HK / short 0020.HK (SenseTime) as a relative-value expression on monetization quality. The long leg wins if platform subscriptions and token usage keep converting to cash; the short leg is the cleaner hedge if the market revalues AI narrative names away from model prestige toward actual recurring economics.
- If options/liquidity are available, buy 3-6 month call spreads on 09678.HK rather than stock outright. The thesis is a gradual multiple expansion, not a near-term squeeze; call spreads cap theta bleed if the market takes time to believe the platform transition.
- Set an alert for the next filing on three variables: backlog-to-revenue conversion, repeat-purchase rate, and operating cash burn. Any deterioration there would falsify the ‘value leadership’ story faster than benchmark rankings can support it.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- IIF CEO on Rising Global Debt