
Lendistry Demos OrigenLink Lending Platform Live at American Banker Conference
Source: Newswire
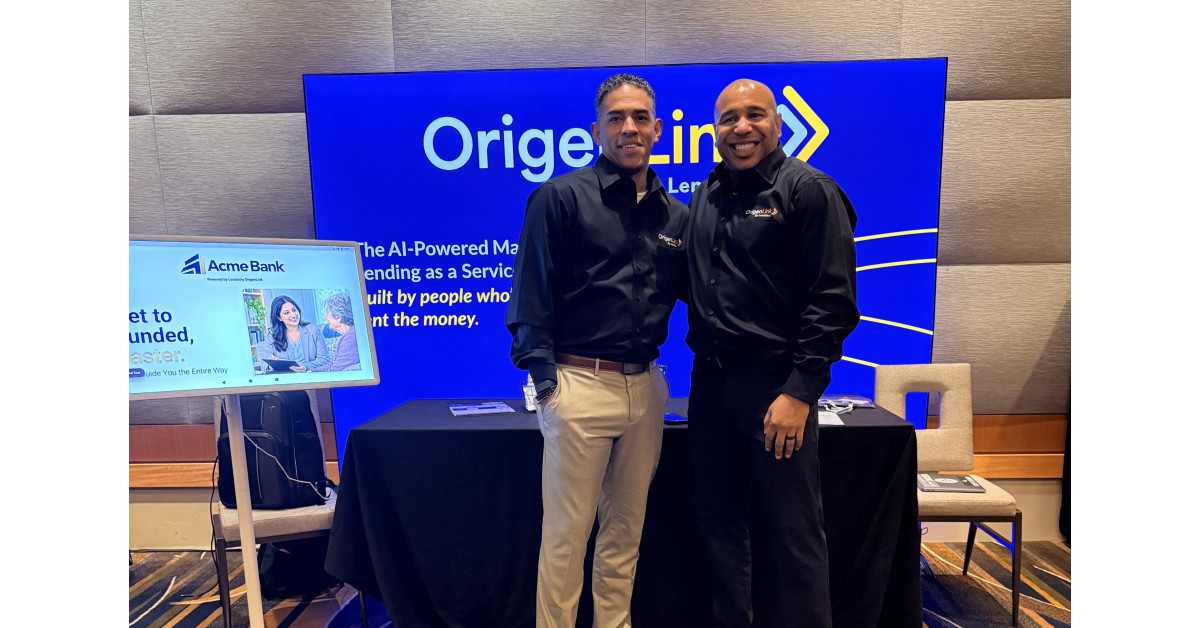
Lendistry demonstrated OrigenLink, a new managed lending-as-a-service platform, to banking leaders at the American Banker Small Business Banking Conference on October 28, 2026. The company says the platform integrates its lending options with banks’ offerings to streamline applications for small-business borrowers, using AI and automation; no launch date, financial impact, or adoption figures were provided. Lendistry says it has deployed more than $11 billion to small businesses since its 2015 founding.
Analysis
The investable question is not whether the interface is faster, but who owns the borrower relationship, underwriting decision, funding, and credit losses. If banks retain customer ownership while routing rejected applicants to Lendistry, the platform could improve conversion and reduce application abandonment—but may also concentrate adverse-selection risk in the nonbank channel. If banks retain meaningful credit exposure, model governance and fair-lending scrutiny become more consequential; if Lendistry funds or guarantees loans, funding costs and loss performance matter more than workflow claims. The announcement provides no evidence yet on signed deployments, funded volume, unit economics, or realized credit performance. Treat the AI and automation claims as unverified until supported by production data.
Over days, likely limited equity impact: no public ticker is supplied for Lendistry, and a conference demo is not a commercial milestone. Over 1–3 months, signed bank pilots and conversion into funded loans would be the relevant catalysts. Over 6–18 months, repeatable integrations could pressure legacy small-business origination workflows, but benefits depend on banks adopting the channel without sacrificing customer control or economics. A deterioration in small-business credit quality could reverse adoption by making banks more cautious and exposing weaknesses in referral underwriting. The contrarian point: a smoother application funnel can increase approvals and volume while worsening risk-adjusted returns; volume alone is not proof of value.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No directional equity trade on this announcement alone; the supplied identity data contains no listed ticker, and the release does not establish commercial uptake.
- Put Lendistry on a catalyst watch: verify signed bank partners, production launch dates, funded-loan growth, repeat usage, and who bears funding and credit losses before underwriting revenue or earnings impact.
- For any bank or fintech exposure, monitor small-business loan delinquencies, net charge-offs, approval rates, and underwriting standards alongside origination growth. Rising volume paired with worsening loss metrics would falsify the positive adoption thesis.
- Reassess in 1–3 months if named production partnerships or disclosed volumes emerge; absent those, treat the demo as product positioning rather than a sector-wide competitive inflection.
More News
- Analysts react as Binance freezes assets after $6.3 billion security breach
- Stocks slump, bonds leap as AI giants’ spending spooks investors
- Alphabet Erases $500 Billion as ChatGPT, Google AI Cut into Search
- Alphabet just had its worst day as a public company. BofA now values Google search at a lower multiple than fossil fuel stocks
- Taiwan Stocks Heads for Correction as Global AI Selloff Deepens
- Asia stocks tumble as AI spending concerns deepen; BOJ holds rates