
Electroplating Market to Reach USD 21.26 Billion by 2034, Driven by Automotive, Electronics and Sustainable Surface-Finishing Technologies, reports Maximize Market Research
Source: PR Newswire
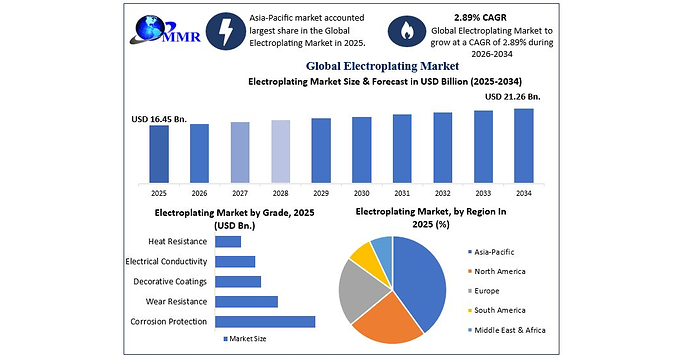
The global electroplating market is projected to grow from $16.45 billion in 2025 to $21.26 billion by 2034, a 2.89% CAGR, driven by automotive, EV, electronics, aerospace and industrial demand for corrosion-resistant and conductive components. Growth is expected to be supported by adoption of automated plating, trivalent chromium, zinc-nickel coatings, metal recovery and wastewater-treatment systems, with Asia Pacific remaining the largest regional market. Recent U.S. activity includes B & B Electroplating's acquisition of Rapid Electroplating Process and a $26,940 Navy order to Westfield Electroplating for cadmium-zinc plating services.
Analysis
This is not a demand-inflection signal: low-single-digit industry growth is unlikely to move FY26 estimates for DD, ESI, AALB, or UMI. The investable implication is mix rather than volume—environmental compliance raises switching costs and favors scaled suppliers with qualified chemistries, process-control IP, and customer-approved formulations. ESI is the cleanest public expression through MacDermid Enthone, where electronics interconnect and higher-spec automotive applications can support pricing and recurring chemical pull-through; DD has adjacent specialty-material exposure but materially less direct earnings sensitivity.
The more consequential second-order effect is a capex burden on fragmented finishing shops. Water treatment, metal recovery, and replacement of legacy chemistries can compress service-provider margins and consolidate regional capacity, improving utilization and pricing for scaled operators such as AALB. For UMI, tighter collection/recovery economics can increase availability of secondary precious metals over time, but its valuation will remain driven far more by PGM pricing, recycling spreads, and automotive catalyst demand than by plating growth.
Near term, this press-release-level forecast is not a catalyst and should not be chased. Over 6-18 months, EU REACH/PFAS-related restrictions, customer qualification cycles for hexavalent-chromium alternatives, and semiconductor packaging/connectivity demand are the variables that could create measurable upside for ESI. The thesis fails if industrial production weakens, electronics inventory correction resumes, or compliance-driven reformulation costs are absorbed without price recovery.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this report; treat it as a 6-18 month thematic watch item rather than an earnings catalyst.
- Maintain or initiate a modest long ESI versus short DD pair over 3-6 months if valuation is neutral: ESI has more direct exposure to specialty plating chemistry and qualification-driven recurring revenue, while DD dilutes the theme through larger cyclical businesses. Exit if ESI's electronics/industrial segment margins fail to improve or management cuts organic-growth guidance.
- Watch AALB for evidence that environmental-compliance capex is converting into margin-accretive pricing or bolt-on M&A; add only following a results release showing organic order growth and stable adjusted EBITA margin. The key risk is cost inflation without pass-through at decentralized finishing sites.
- Do not use UMI as a plating proxy. Any long UMI should be underwritten to PGM/recycling-spread normalization, with plating-related precious-metal recovery only a marginal upside optionality.
More News
- US to send third aircraft carrier towards Iran: US official to Al Jazeera
- Trump launches midterms campaign blitz amid record low approval ratings
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- ‘They’ll be hit very hard’: Trump sends roughly 9,000 troops and a third aircraft carrier to the Middle East after warning strikes on Iran
- Russia’s Putin rules out ceasefire with Ukraine during speech in Moscow
- ‘Playing a dangerous game’: Putin threatens using ‘all its arsenal’ if there is a ‘direct attack on the Russian Federation’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Financial Research Benchmarks: What the Scores Mean
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper