
Chevron Strengthens Namibia Position Ahead of Nabba-1X Well
Source: zacks.com
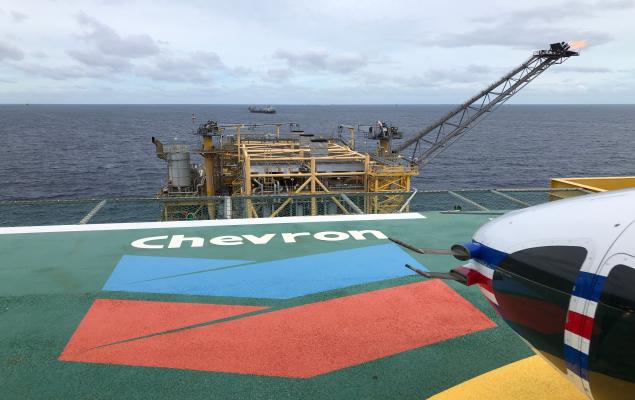
Chevron agreed to acquire Trago Energy’s 10% participating interest in Namibia’s PEL 90 for $11 million upfront, plus contingent payments, potentially lifting Chevron’s stake to 45.1% after its planned Equinor farm-out; the deal requires approvals. Chevron remains operator, and the planned Nabba-1X exploration well is scheduled for Q4 2026. The increased exposure offers upside if a commercial discovery is made, but PEL 90 remains high-risk exploration acreage; an earlier well did not find commercial hydrocarbons.
Analysis
Treat the stake increase as a small, long-dated option on acreage—not a near-term earnings revision for Chevron. Even if the transaction closes, the market should assign little value before a commercial discovery, appraisal, and a credible development path; basin proximity is not proof of comparable reservoir quality. The prior non-commercial well raises the bar for interpreting Nabba-1X, while additional ownership increases Chevron’s share of both any upside and future work-program costs. Operatorship preserves control, but can also leave Chevron accountable for schedule and execution.
The more meaningful second-order signal is basin validation: a strong result could improve sentiment toward nearby Orange Basin acreage, including TotalEnergies’ regional position, without establishing a direct read-through to its Venus discovery. Equinor’s participation spreads exposure, but its broader business mix makes it an imperfect hedge or pure-play proxy. The contingent payment structure may limit seller-buyer disagreement over uncertain value, but does not remove approval or geological risk.
With drilling scheduled for Q4 2026, operational updates may drive short-term attention; any lasting valuation effect is likely months to years away. The contrarian point is that a larger stake can be read as management conviction, but it is not independent geological confirmation—and the disclosed upfront consideration is too small to make the transaction itself a material Chevron catalyst. A delay, regulatory obstacle, or non-commercial result would likely extinguish most of the incremental optionality.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in CVX on this transaction: its potential asset-level upside is unlikely to move consolidated earnings before discovery and appraisal. Revisit only if Nabba-1X results support commercial scale and a development pathway.
- Track approval/closing and operational milestones into Q4 2026. Treat a firm spud schedule and subsequent well results as the catalyst; a postponement beyond the stated quarter weakens the near-term event thesis.
- Do not use EQNR or TTE as a direct hedge for CVX’s PEL 90 exposure: their broader portfolios dominate, and regional basin read-through is not equivalent to asset-level exposure.
- Falsification/watch item: a non-commercial Nabba-1X result, material schedule slippage, or evidence that appraisal economics cannot support development would invalidate the exploration-option thesis. Verify final working interests and cost-sharing obligations after approvals.
More News
- US forecasts hurricane later this week in Gulf of Mexico
- A 32% beat, a +6% jump: the IT solutions name our models picked in July
- The world has nearly burned through its oil stockpile buffer, executives say
- Equinor warns UK risks uninvestable label over North Sea projects
- Chevron CFO Eimear Bonner built a 20-plus-year career at the company. Now she’ll run its core business
- Unsure how long this AI bull has? Bonds now offer a cushion at the best values in years
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Hebbia Alternatives: A Workflow-Based Buyer’s Guide
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect