
NORTH CAROLINA RAILROAD COMPANY INVESTS $250,000 TO SUPPORT ATLANTIC PACKAGING EXPANSION IN TABOR CITY
Source: PR Newswire
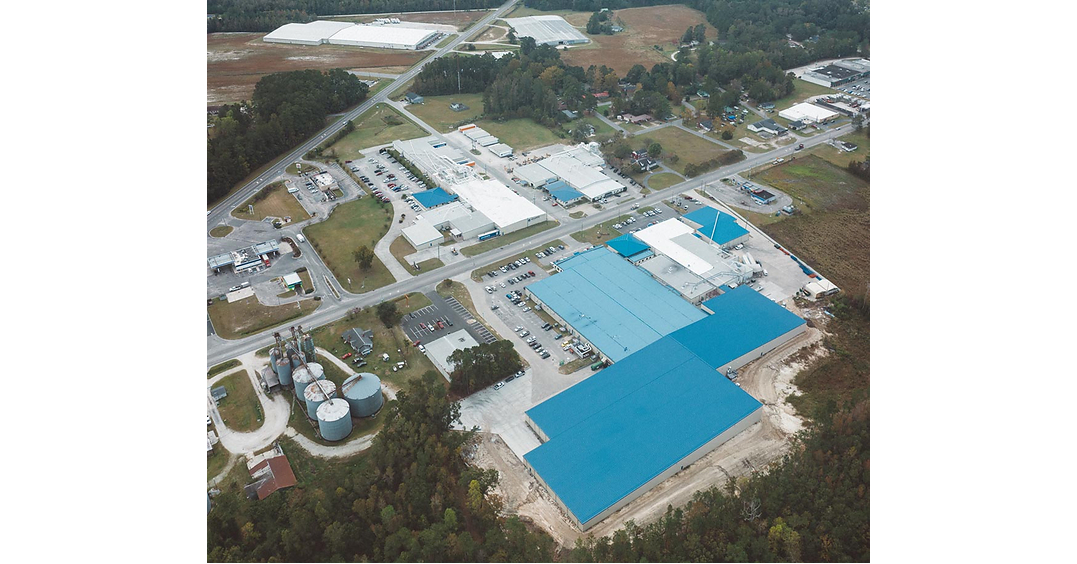
North Carolina Railroad Company will invest up to $250,000 to build a rail spur for Atlantic Packaging's Tabor City warehouse expansion, while Atlantic Packaging plans to invest more than $5 million and create 16 full-time jobs. The facility is expected to handle at least 480 rail cars annually, enabling rail delivery of paper and other raw materials and strengthening the regional freight supply chain. The project is funded through NCRR's private-revenue grant program rather than taxpayer funds.
Analysis
This is immaterial to public-equity earnings on its own, but it is a useful micro-signal that inland rail economics remain competitive for bulky packaging inputs despite trucking’s service advantage. The implied volume is too small to affect Class I railroad revenue, yet incremental carloads can improve local network density and reinforce pricing discipline in southeastern freight corridors. The more relevant read-through is for containerboard and paper converters: rail-enabled inbound sourcing lowers delivered-fiber volatility and working-capital needs, modestly protecting conversion margins when diesel or long-haul trucking rates rise.
Over the next 1-3 months, there is no standalone catalyst for NSC or CSX absent disclosure of the serving carrier, contracted volumes, or broader shipper commitments. Over 6-18 months, a cluster of similar spur investments would be constructive for CSX, whose network is the most plausible public-market exposure in the Carolinas, because local-origin/destination traffic carries better incremental economics than lower-yield intermodal. The key falsifier is not this project’s opening: it is whether eastern rail carloads and revenue-per-car continue to lag while truckload rates remain depressed, which would indicate that infrastructure additions are not translating into pricing power.
The consensus risk is to overinterpret public infrastructure announcements as near-term rail volume growth. Packaging demand remains tied to consumer staples, foodservice, e-commerce and industrial production; a soft manufacturing cycle can overwhelm any logistics-cost benefit. Privately held Atlantic Packaging also prevents investors from directly monetizing the operational improvement, making this an industry-monitoring datapoint rather than a trade trigger.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No standalone position based on this announcement; maintain as a watch item for CSX and NSC rather than treating it as an earnings catalyst.
- Monitor CSX quarterly merchandise-carload growth, yield excluding fuel, and Southeast industrial-development pipeline over the next 2-3 quarters. Consider a tactical CSX overweight only if merchandise volumes turn positive while operating-ratio guidance is maintained or raised.
- Use a long CSX / short J.B. Hunt (JBHT) relative-value screen if diesel prices and contract truckload rates begin rising: rail’s cost advantage should widen, but enter only after confirmation from freight-rate data. Exit if truckload spot rates remain weak and CSX merchandise volumes fail to improve for two consecutive monthly reports.
- For packaging exposure, watch International Paper (IP) and Packaging Corp. of America (PKG) for evidence that lower inbound logistics costs are offsetting containerboard-price pressure; absent improving box demand or margin guidance, this rail investment does not justify a long.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Iran war increasing inflation, straining US munitions: congressional report
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- State of Public Markets, June 2026: Higher for Longer Meets the AI Supercycle
- AI Research Tools With Exact Source Citations