
Before ChatGPT, PhyPal Had the Clinical Evidence but Not the AI. Now It's Back.
Source: PR Newswire
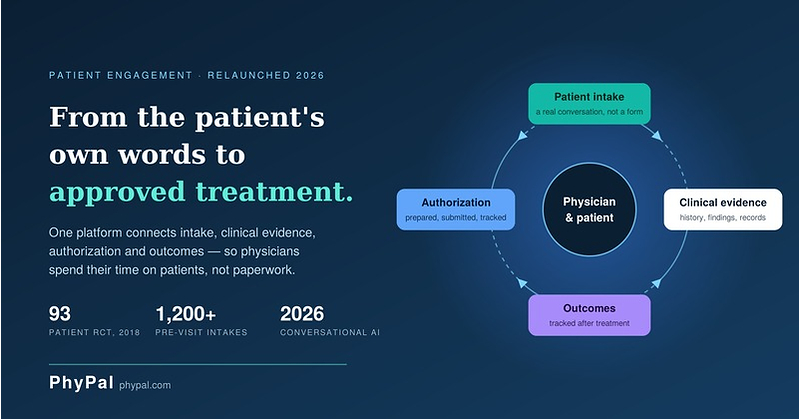
PhyPal relaunched its patient engagement platform with conversational AI layered onto its deterministic clinical workflows, connecting patient intake, documentation, outcomes tracking, and treatment authorization. The company says more than 1,200 patients have completed pre-visit intakes using its technology; its earlier Snapcare system was evaluated in a 93-patient randomized controlled trial, with greater disability reduction at 12 weeks versus conventional care (p < 0.001). A California workers’ compensation practice pilot will assess potential reductions in administrative work and improvements in treatment coordination; no financial results or market reaction were reported.
Analysis
The investable signal is not “AI in healthcare”; it is whether conversational intake can reliably feed clinical documentation and authorization workflows. If the California workers’ compensation pilot demonstrates fewer staff touches, faster authorization decisions, or lower denial rates, the value accrues to provider groups through administrative capacity and potentially faster treatment—not necessarily to the AI vendor unless it can convert pilots into repeatable, paid deployments. Incumbent EHR, revenue-cycle, and outsourced administrative vendors face a competitive threat only if PhyPal integrates into existing systems and proves measurable workflow savings; otherwise it is another point solution with integration costs.
Evidence remains early: the company cites a 93-patient trial for its earlier platform and more than 1,200 completed intakes, but neither establishes current AI performance, commercial retention, or authorization impact. Treat the clinical study and product claims as company-provided context, not proof of the relaunch’s economics. Near term, this is unlikely to move public-company earnings. Over 1–3 months, the key catalyst is pilot data and evidence of paid conversion. Over 6–18 months, payer and provider adoption, integration burden, and safe handling of sensitive data determine whether this becomes workflow infrastructure or a feature copied by larger platforms.
Contrarian angle: the defensible asset may be structured clinical workflow and outcomes data, not the conversational interface; generative AI lowers the cost of building intake tools, increasing competition and limiting pricing power. No clean public-market exposure is identified, so avoid forcing a single-name trade. The thesis weakens if the pilot cannot show reduced authorization cycle time or staff workload, or if providers report material documentation errors or integration friction.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No immediate public-equity trade: PhyPal is not mapped to a listed ticker in the supplied data, and the announcement provides no revenue, pricing, or paid-customer evidence.
- Set a 1–3 month watch item for California pilot results. Require quantified changes in authorization cycle time, denial/rework rates, staff hours per case, and conversion to a paid deployment before treating this as a commercial signal.
- For healthcare IT and revenue-cycle holdings, assess exposure to automatable intake and authorization labor, but do not short incumbents solely on this launch; integration and payer adoption are unproven, and incumbents can replicate or bundle similar capabilities.
- Falsification triggers: pilot results show no measurable workload or authorization improvement; material AI-generated documentation errors emerge; or deployment requires extensive customization that prevents repeatable rollout.
More News
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- Elon Musk intensifies attack on Ambani over Starlink India launch delay
- What's behind the recovery rally in tech stocks — plus, Elon Musk's very good week
- Wall Street Week | Michigan Manufacturing, AI Debt Investments, Baby Bonds, Canadian Coal Fight
- SpaceX’s Wireless Threat Rises With Spectrum Deal
- OpenAI's revenue scare, Delta earnings, what investors think of a Starbucks-Chipotle deal and more in Morning Squawk
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI in Asset Management: 2026 Statistics That Hold Up
- What is Broker Research and RMS Systems (And How to Actually Use Them)