
MERIWETHER COMPANIES DEBUTS MULTIMILLION-DOLLAR TRANSFORMATION OF LA VALLE COASTAL CLUB IN RANCHO SANTA FE, CALIFORNIA
Source: PR Newswire
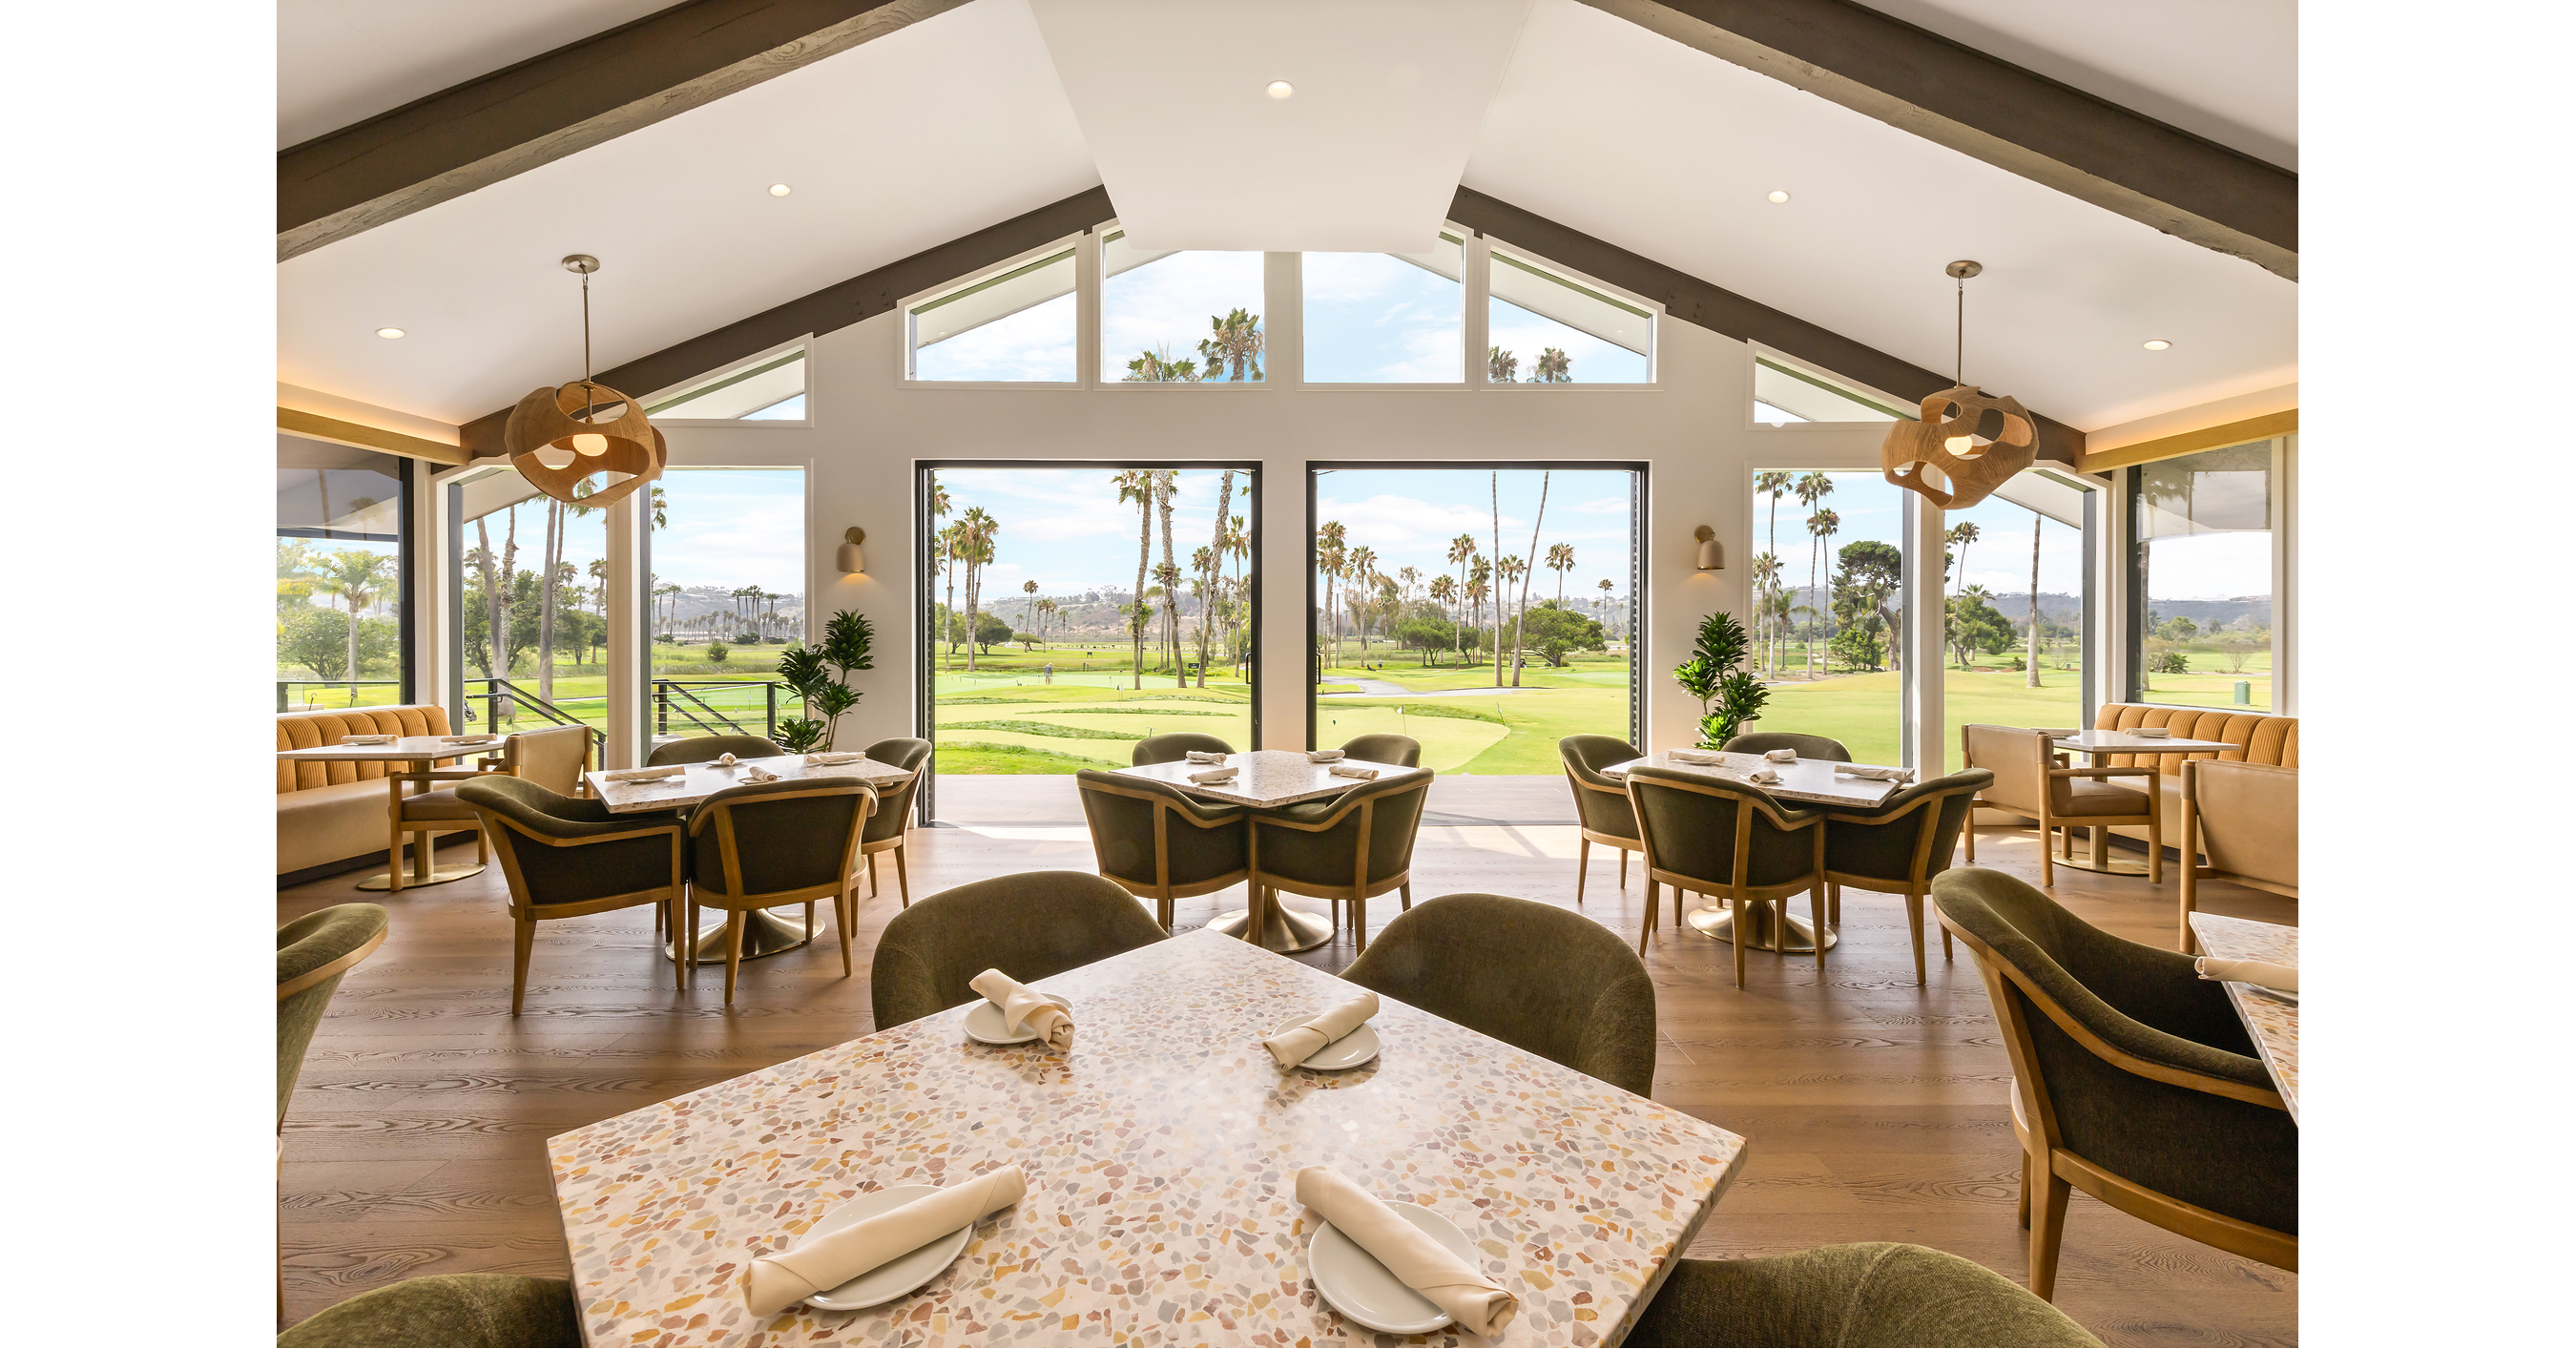
Meriwether Companies completed a $50 million renovation of the 300-acre La Valle Coastal Club in Rancho Santa Fe, repositioning the property as a casual private club and boutique hospitality destination. The upgrade includes the 77-room Guesthouse Hotel, redesigned 27-hole golf offering, expanded practice facilities, wellness center, racquet sports, new dining venues and more than 17,000 square feet of event space. The project is a positive asset-development milestone but is unlikely to have broad public-market impact.
Analysis
There is no investable read-through to the supplied tickers: CULP is a publicly traded mattress/upholstery fabric supplier, while DAVE is a fintech company; the remaining labels do not appear to be liquid public-equity exposures. Treating developer partner names or a project name as tickers is a data-quality failure, not a basis for a thematic position. The developer is privately held, so neither renovation spend nor any potential improvement in membership, hotel occupancy, food-and-beverage, or event revenue can be translated into public-company earnings sensitivity.
The useful sector signal is narrowly local: amenity-rich clubs are increasingly competing for recurring membership revenue against destination hotels, boutique fitness, wellness providers, and racquet-sport venues rather than solely against traditional golf clubs. That model can support higher ancillary spend and lower seasonal utilization volatility, but the capital intensity creates a long payback period and leaves returns highly dependent on membership initiation fees, dues pricing, and hotel RevPAR—none of which are disclosed. Over the next 6-18 months, comparable public lodging operators with meaningful Southern California exposure could benefit only if affluent leisure demand remains resilient; this single-asset announcement is not sufficient to alter estimates or multiples.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No trade in CULP, DAVE, CABO, or NOAH based on this item; the identified tickers lack an economic linkage to the underlying asset.
- Create a watch item for public lodging proxies such as MAR, HLT, and PEB: look for independently reported Southern California RevPAR, group/event demand, and luxury leisure trends over the next 1-3 quarters before assigning any regional demand read-through.
- For private-market monitoring, request membership pre-sales, initiation-fee structure, stabilized hotel occupancy/ADR, and incremental EBITDA versus the renovation budget. Without these data, underwriting a return on invested capital or a competitive-share shift is not possible.
- Falsify any broader affluent-leisure strength thesis if Southern California luxury RevPAR or resort EBITDA guidance weakens in upcoming earnings, or if consumer discretionary spending indicators deteriorate; either would imply that new amenity supply is more likely to pressure pricing than expand the market.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Why is Weichai Power stock rallying today?
- Fed hikes again - an AI-Picked insurer is still cashing in
- Fed approves interest rate hike, signals one more to come this year
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- Consumers hit by one-two punch of oil and rates from Iran war. The estimated bill is $1,700 per household