
METLEN et PETRONAS concluent un accord d'approvisionnement en GNL visant à renforcer la sécurité énergétique et la diversification énergétique en Europe du Sud-Est
Source: PR Newswire
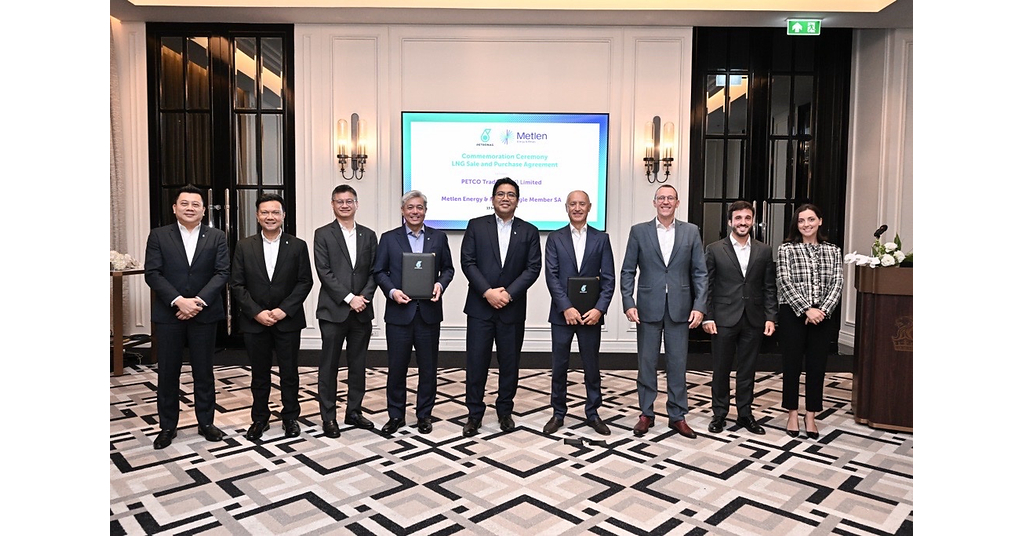
METLEN and PETRONAS signed a five-year LNG supply agreement under which PETCO Trading UK will deliver six LNG cargoes annually to Greece from 2027, totaling about 0.6 bcm per year. The deal diversifies METLEN's supply sources and is intended to improve energy-security resilience and market liquidity in Greece and southeastern Europe. It also expands PETRONAS's LNG commercial presence in Europe and the Mediterranean, though the contracted volume is modest relative to the broader European gas market.
Analysis
The contract is strategically useful but financially immaterial at group level: 0.6 bcma is roughly six LNG cargoes annually, so the market should not capitalize it as a step-change in METLEN earnings. Its value lies in lowering procurement concentration and giving METLEN optionality to optimize cargoes across Greek power generation, industrial demand and regional balancing markets. That optionality matters most during winter TTF spikes or Balkan pipeline disruptions, when secured Atlantic-basin supply can protect power-generation margins and support trading EBITDA.
The more material second-order effect is METLEN’s ability to monetize Greece’s infrastructure and location as regional gas flows increasingly bypass Russian-linked routes. A deeper contracted LNG book can improve utilization economics for downstream gas-to-power assets and make METLEN a more credible counterparty for incremental Balkan offtake; this is a 6-18 month earnings-quality rather than a 2027 volume-growth catalyst. Petronas gains portfolio placement flexibility, but as an unlisted parent the read-through is primarily for competing European LNG marketers such as Shell (SHEL), BP (BP) and TotalEnergies (TTE), whose margins depend on regional destination optionality.
Consensus risk is to treat supply diversification as a pure positive without knowing the pricing basis, destination flexibility, take-or-pay exposure, or whether cargoes are indexed to TTF, Henry Hub or oil. A sustained Europe LNG surplus would turn fixed-volume commitments into a working-capital and mark-to-market drag; conversely, a renewed supply shock makes the embedded optionality valuable. METLEN’s leverage means the relevant confirmation is not cargo volume but whether 2027 procurement costs, gas-trading contribution and net-debt/EBITDA improve without incremental collateral needs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No event-driven trade on the announcement alone; monitor MTLN for a 1-3 month entry only if management discloses pricing/indexation and destination flexibility, with a target that the agreement is margin-protective rather than merely volume-accretive.
- Maintain a constructive 6-18 month MTLN view versus European utility peers more exposed to regulated retail power margins; express via long MTLN / short a broad European utilities ETF only after confirmation that gas-trading EBITDA and net debt remain on plan. Falsifier: a material rise in collateral or working-capital requirements, or net debt/EBITDA moving above management’s deleveraging trajectory.
- Use winter 2026-27 TTF volatility as the tactical catalyst: long MTLN is most attractive if TTF volatility rises while its contracted supply economics remain undisclosed but likely flexible. Take no directional LNG-price position from this deal; the key missing variable is the SPA price formula.
- Watch SHEL, BP and TTE quarterly LNG-trading disclosures rather than assume negative read-through: a small Greek contract does not alter global portfolio balances, but repeated Petronas Atlantic-basin placements could incrementally tighten competition for Mediterranean regasification and destination-flexible cargoes.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off