
ROSEWOOD HONG KONG NAMED NO.1 IN THE 50 BEST HOTELS 2026 FOR THE SECOND CONSECUTIVE YEAR
Source: PR Newswire
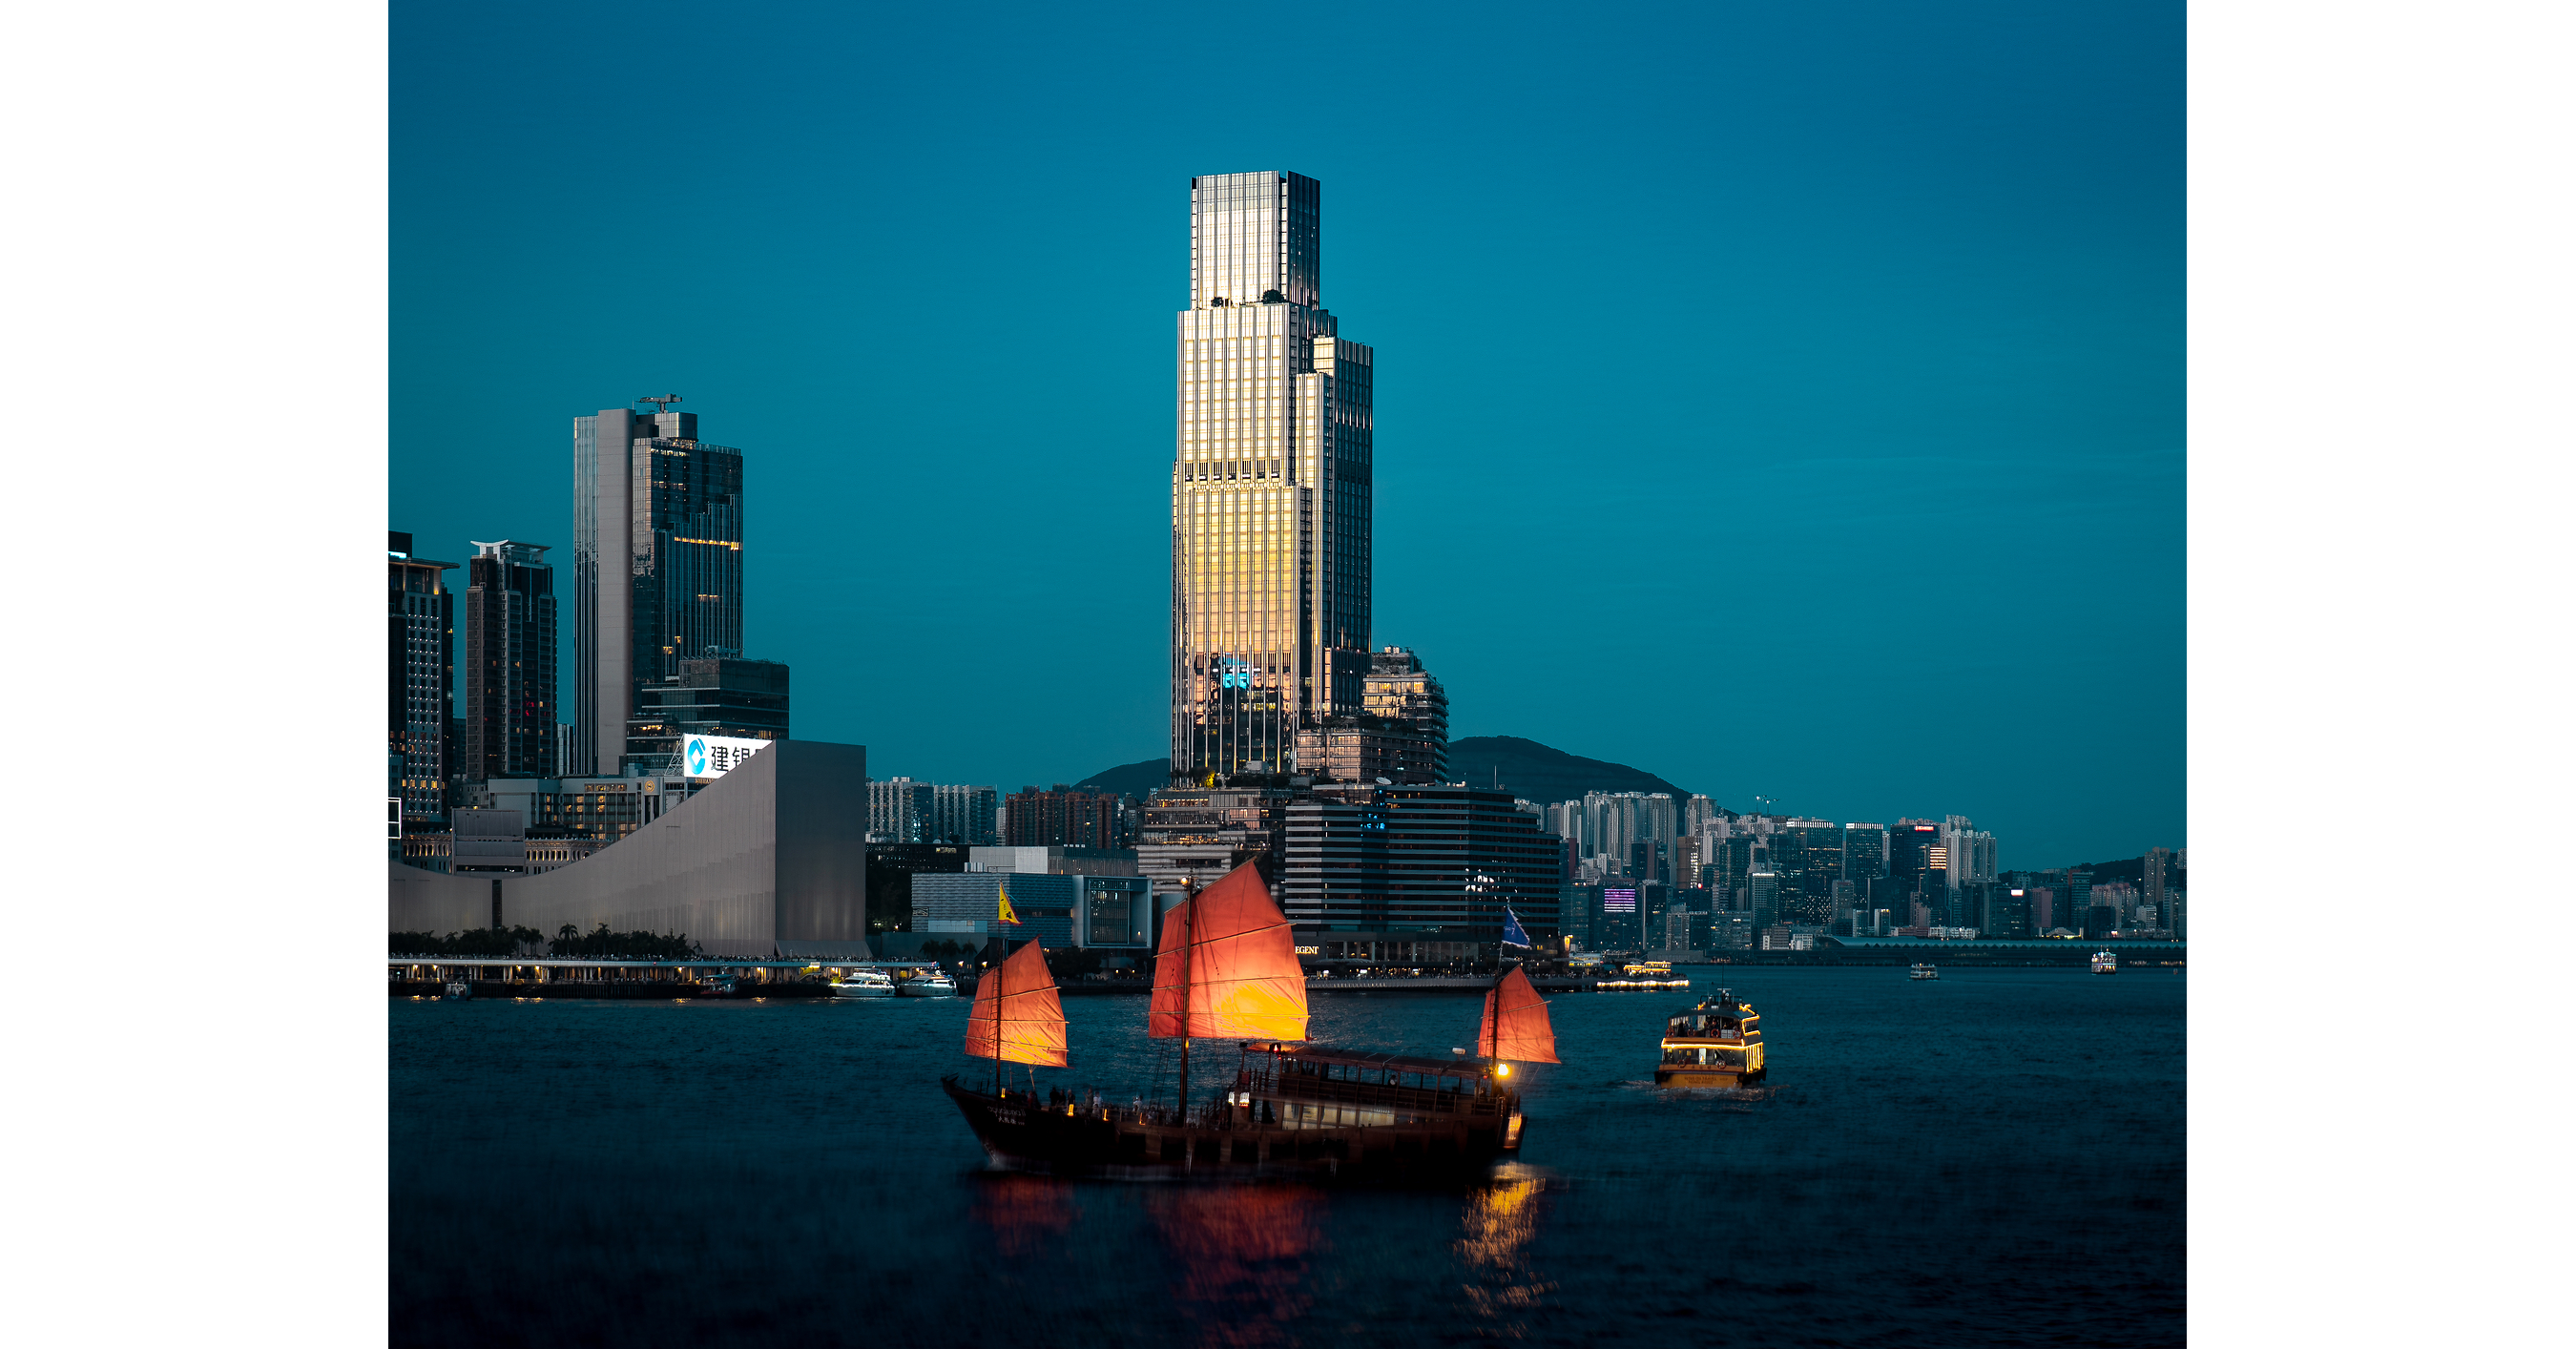
Rosewood Hong Kong retained the No.1 position in The 50 Best Hotels 2026 ranking, ahead of Capella Bangkok at No.2 and Four Seasons Bangkok at No.3. Europe led the list with 21 hotels, followed by Asia with 18, while 10 new entries across seven destinations underscored continued expansion in luxury hospitality. Rosewood also won Most Admired Hotel Group, and Chablé Yucatán received the Eco Hotel Award, with solar power supplying about 60% of its energy.
Analysis
This is primarily a brand-marketing signal rather than an earnings catalyst; the directly investable read-through is strongest for luxury travel intermediaries and card networks, not broad lodging. AXP benefits marginally from high-spend international leisure and its positioning around curated premium travel, but awards-event sponsorship is too small to alter billed-business or card-member growth expectations. Monitor whether premium travel-and-entertainment spend continues to outgrow overall billed business in the next two quarterly disclosures; that is the measurable confirmation, not social-media visibility.
The more useful second-order implication is continued pricing power bifurcation: trophy independent properties and ultra-luxury managed brands can defend ADR and ancillary spend even if upper-upscale chains face softer occupancy. Hyatt (H) has selective exposure through its luxury portfolio, but its earnings sensitivity is diluted by systemwide franchise/management fees and broad geographic mix; there is no basis to change estimates from this development. Private owners of highly ranked assets may gain leverage in management-contract negotiations, modestly pressuring branded operators' incentive-fee economics over a 6-18 month horizon.
Contrarian view: luxury-hospitality accolades can be a lagging indicator of peak capex and peak experiential-travel enthusiasm. If high-income consumer spending slows, these assets retain rate integrity but experience occupancy and food-and-beverage operating deleverage; public hotel equities would likely trade on RevPAR revisions rather than prestige. RACE has only indirect luxury-consumer affinity and no identifiable revenue linkage, making any sympathy move non-fundamental.
No standalone trade is warranted. Treat any outsized move in AXP, H, or RACE as liquidity-driven unless accompanied by revised premium-spend, RevPAR, or luxury-order guidance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Maintain neutral H: revisit only if forthcoming results show luxury/international RevPAR accelerating versus systemwide RevPAR by more than 300 bps while management raises full-year fee-growth guidance; otherwise the ranking has no valuation relevance.
- Keep AXP as a watch item, not an event trade: add only on evidence that T&E billed-business growth reaccelerates and premium-card acquisition costs remain controlled. Falsifier is decelerating spend growth or a material increase in rewards/marketing expense that limits operating leverage.
- Do not buy RACE on luxury-travel association. Require order-book, pricing, or mix evidence for any long thesis; absent that, the news has effectively zero earnings transmission.
- For a 6-18 month thematic hedge, monitor luxury lodging ADR and occupancy against broader hotel RevPAR. A sustained widening would favor asset-light luxury operators over economy lodging; a narrowing alongside weaker high-end consumer data would signal luxury-demand normalization and multiple risk.
More News
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Federal Reserve decision, retail sales, and oil inventories due Wednesday
- Saudi-led coalition intercepts drone headed for Mecca
- Why Dave & Buster's Stock Tumbled Today
- US data centers could consume more natural gas than Germany and Japan combined by 2035
- EU to Levy Fines of Up To 6% of Tech Companies’ Sales in Kids Act