
NOVVA Group secures landmark 3.17 GW renewable energy portfolio from ABO Energy to power global AI infrastructure
Source: PR Newswire
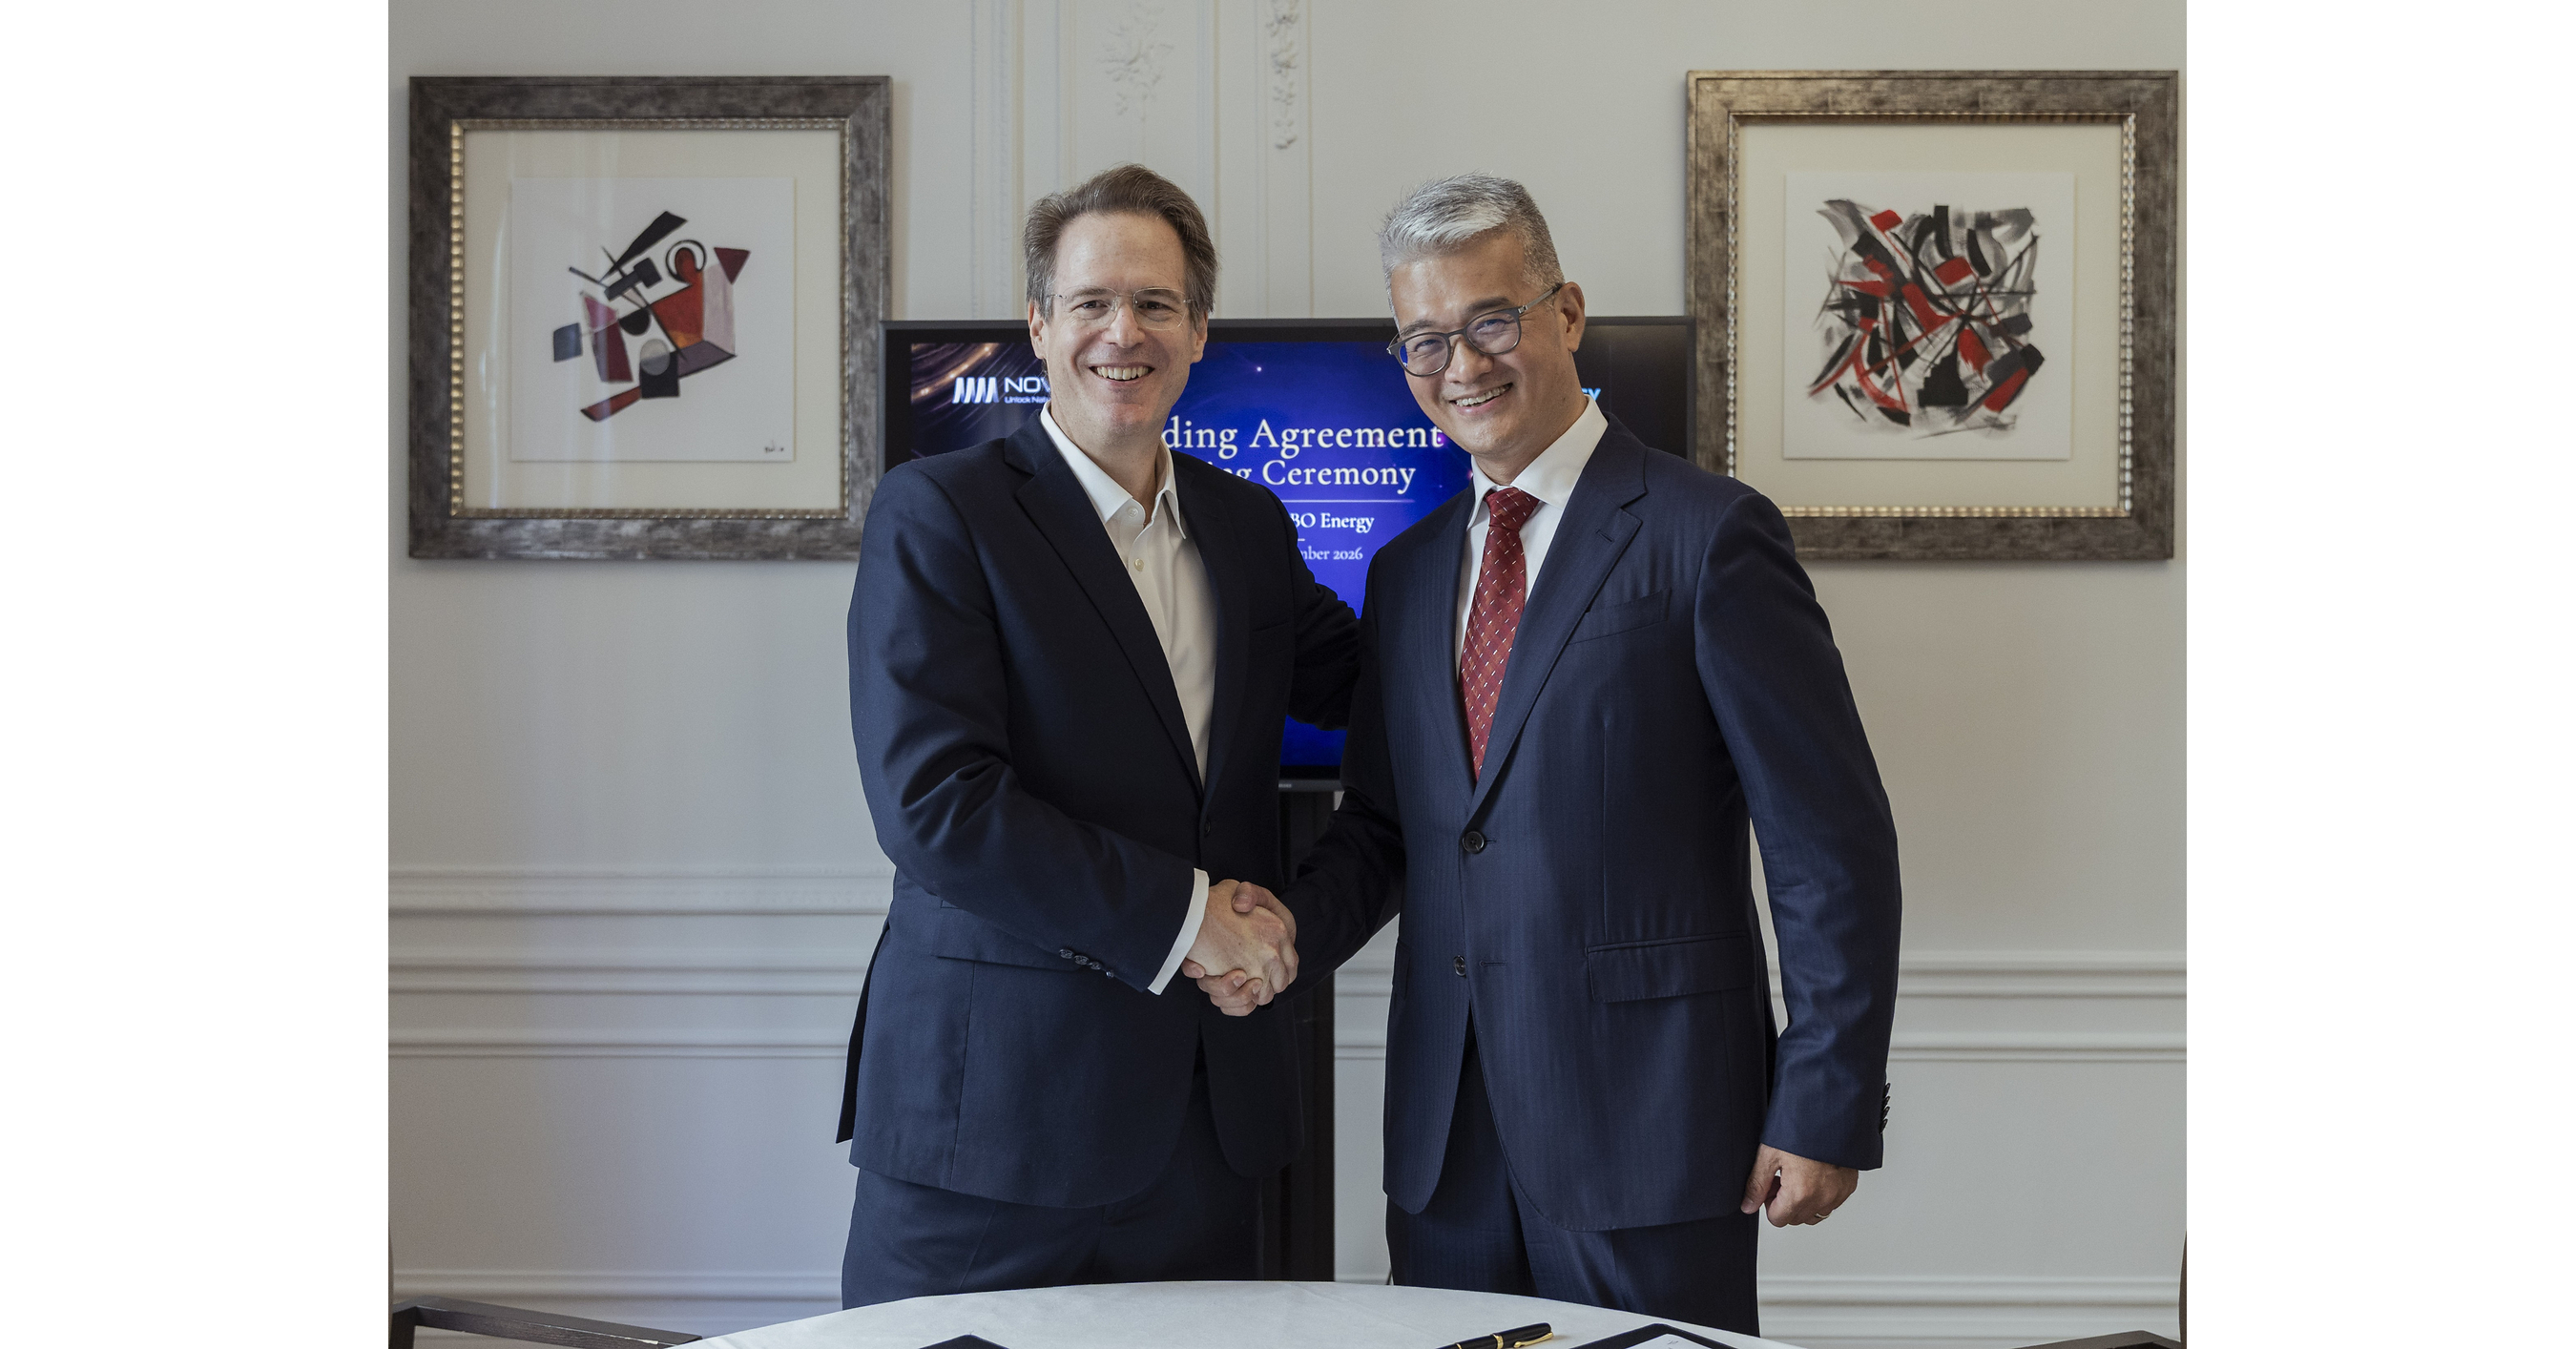
NOVVA Group signed a binding framework agreement to acquire a 3.17 GW renewable-energy portfolio in Argentina from Germany's ABO Energy, following its acquisition of three Colombian solar projects earlier this year. The deal materially expands NOVVA's Latin American clean-power pipeline and is intended to support energy supply for AI data centres and related powered-land infrastructure. Financial terms, project development stages and closing timing were not disclosed.
Analysis
For ABO Energy (AB9), the economic value is determined less by the headline GW figure than by project maturity, interconnection rights, land control and whether the buyer assumes development-capex obligations. A portfolio sale can improve capital recycling and reduce Argentina-specific funding needs, potentially supporting a higher valuation for ABO's remaining core-market pipeline; however, a binding framework agreement is not equivalent to a closed asset sale, and absent consideration, milestones and closing conditions, no NAV uplift can be underwritten.
The likely bottleneck is not renewable-resource availability but Argentina's convertibility, offtaker-credit and transmission constraints. If the assets require merchant exposure or local-currency revenues, financing costs could absorb much of the apparent development value; AI-related demand does not solve this unless Novva can disclose creditworthy USD-linked PPAs, grid access and funded data-center commitments. Conversely, a credible international-power-purchase structure would make these projects strategically scarcer and could attract infrastructure funds seeking Latin American development optionality.
Near term, AB9 may receive a modest sentiment benefit from evidence that its pipeline can be monetized despite emerging-market risk. Over 1-3 months, transaction disclosure and any cash proceeds matter more than the portfolio size; over 6-18 months, successful recycling could validate an asset-light developer model and release capital for higher-return European projects. The contrarian view is that market participants may assign too much value to nominal development GW: a delay in Argentine FX reform, grid-connection approval or project financing would sharply reduce realizable value while leaving ABO exposed to execution drag.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Maintain AB9 as a watch-list long rather than initiate on the announcement; enter only after disclosure of consideration, payment currency, closing date and the proportion of late-stage/ready-to-build capacity. A cash valuation implying material value per de-risked MW and limited retained guarantees would be the confirmation signal.
- If AB9 rallies more than 10-15% before transaction economics are released, fade or avoid chasing: the framework structure leaves substantial closing and valuation risk. Thesis is falsified positively by an announced cash close with funded milestones and limited Argentine residual exposure.
- For renewable-infrastructure exposure, prefer a relative long in diversified listed developers/utilities with contracted OECD-market cash flows over AB9 until Argentina-specific financing terms are known; AB9's risk/reward is dominated by sovereign and FX variables rather than broad renewable-power pricing.
- Set event alerts for Argentine capital-control changes, USD-linked PPA or offtaker disclosures, interconnection awards and project-finance commitments. Any requirement for ABO to retain material development funding, guarantees or minority equity would weaken the capital-recycling thesis and warrants reassessment.
More News
- Skupina NOVVA získala od společnosti ABO Energy významné portfolio obnovitelných zdrojů energie o výkonu 3,17 GW, které bude napájet globální infrastrukturu umělé inteligence
- NOVVA Group adquiere una cartera histórica de energía renovable de 3,17 GW a ABO Energy
- NOVVA Group secures landmark 3.17 GW renewable energy portfolio from ABO Energy to power global AI infrastructure
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Iran war increasing inflation, straining US munitions: congressional report