
Why Did SpaceX Stock Soar Today?
Source: fool.com
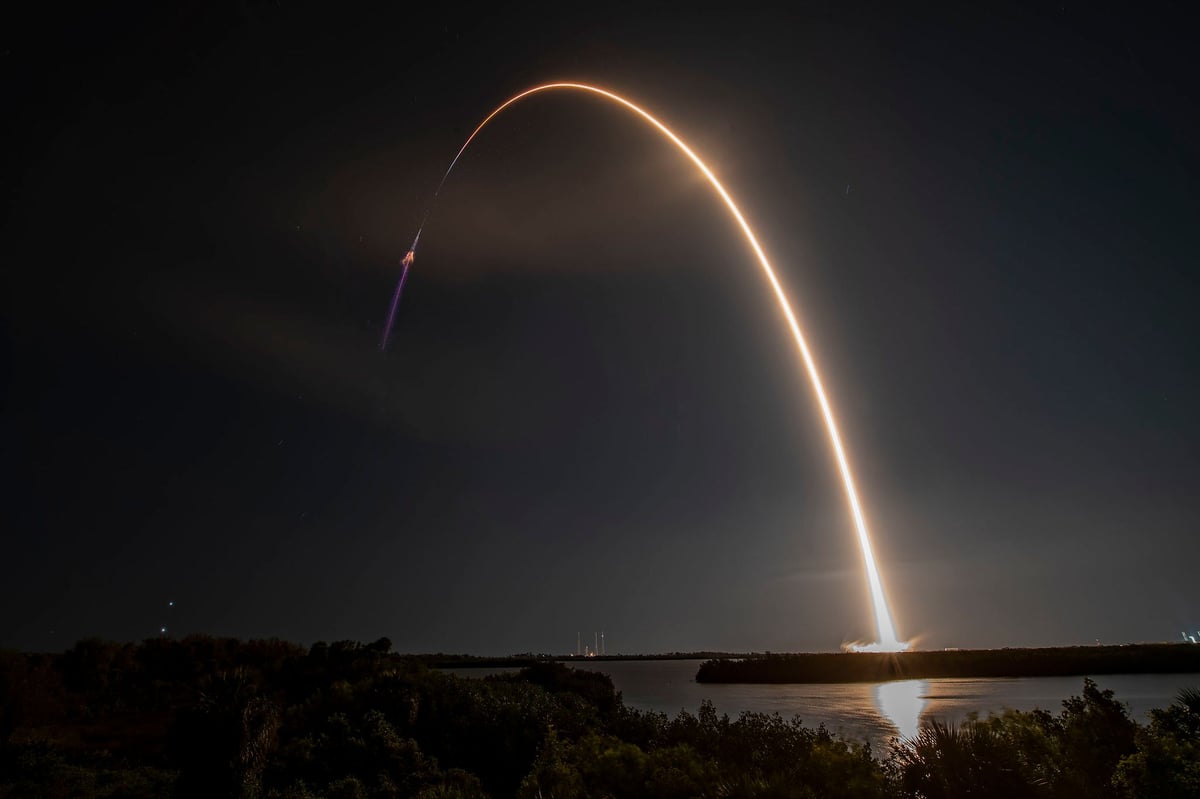
SpaceX reported 161% year-over-year revenue growth and Q3 revenue of $14.6 billion, nearly $2 billion above analyst expectations; shares were up 11.9% as of 10:10 a.m. ET. Its SI superintelligence business generated about $430 million in net income and more than half of latest-quarter revenue, while Starlink subscriptions rose from 12 million in Q2 to 13.6 million in Q3. SpaceX forecast Q1 2027 revenue of $33 billion–$37 billion, versus analysts’ $22.2 billion estimate.
Analysis
The key issue is not the reported growth but whether SI revenue is durable, cash-generative compute demand or a capex-heavy capacity build whose economics are obscured by segment reporting. If leasing compute capacity is the engine, power availability, accelerator utilization, depreciation and customer concentration—not headline revenue—will determine whether reported segment profit converts to free cash flow. A fast ramp could also tighten access to GPUs, power and data-center capacity for other AI providers; conversely, weak utilization would expose SpaceX to costly idle assets and pressure the valuation.
Treat the quoted Q1 2027 outlook as the central verification risk: it implies a step-change from the reported quarter, so investors need the actual filing, comparable revenue definitions, segment eliminations, and a reconciliation of guidance to contracted capacity. The stated $2.1T valuation leaves little room for a miss if growth is dependent on continuing investment; annualizing one quarter is not a sound valuation method, but it underscores the need to test the price against forward cash flow rather than sales momentum.
Near term, the sharp rally raises event-risk and makes chasing unattractive. Over 1–3 months, disclosure quality, capacity utilization and customer commitments should drive revisions. Over 6–18 months, execution on compute economics and Starlink retention matter more than subscriber additions alone. The bullish thesis fails if guidance is withdrawn or materially cut, SI margins/cash conversion weaken, or capacity is not filled. The article’s extraordinary figures require independent verification before treating them as investable facts.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.80
Ticker Sentiment
Key Decisions for Investors
- Do not chase the post-results spike on the article alone. Put SPCX on a verification watch pending the company filing or call transcript and confirmation that the revenue, SI profit and Q1 outlook share comparable accounting scope.
- If verified, assess an SPCX long only after checking SI utilization, contracted backlog, customer concentration, capex and free-cash-flow conversion. A revenue beat without evidence on these measures is not enough to underwrite the valuation.
- Watch AI infrastructure suppliers and power/data-center capacity as potential beneficiaries of a genuine compute buildout, but avoid assuming incremental demand is net-new until customer commitments and deployment schedules are disclosed.
- Reassess promptly if management cuts the outlook, SI profitability reverses, or reported growth fails to translate into cash generation; those would challenge the premium-growth thesis. No short is warranted solely from the article given the lack of verified financial detail.
More News
- Elon Musk Thinks $3.5 Trillion Tesla-SpaceX Mashup Is a Good Idea
- Why is Tesla stock falling after-hours today?
- Futures orbit around SpaceX as Tesla merger talk cheers investors
- Zuckerberg told Meta directors he might leave California, where he could lose billions to a wealth tax. Meta answered with a new class of stock
- SpaceX gives the AI trade a shot in the arm. What it means for our stocks
- Apple's iPhone Duo in short supply — plus, the 2 stocks fueling an AI rebound
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Hebbia Alternatives: A Workflow-Based Buyer’s Guide
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect