
Hanwha Defense USA to Locate Munitions Manufacturing Campus at Pine Bluff Arsenal
Source: PR Newswire
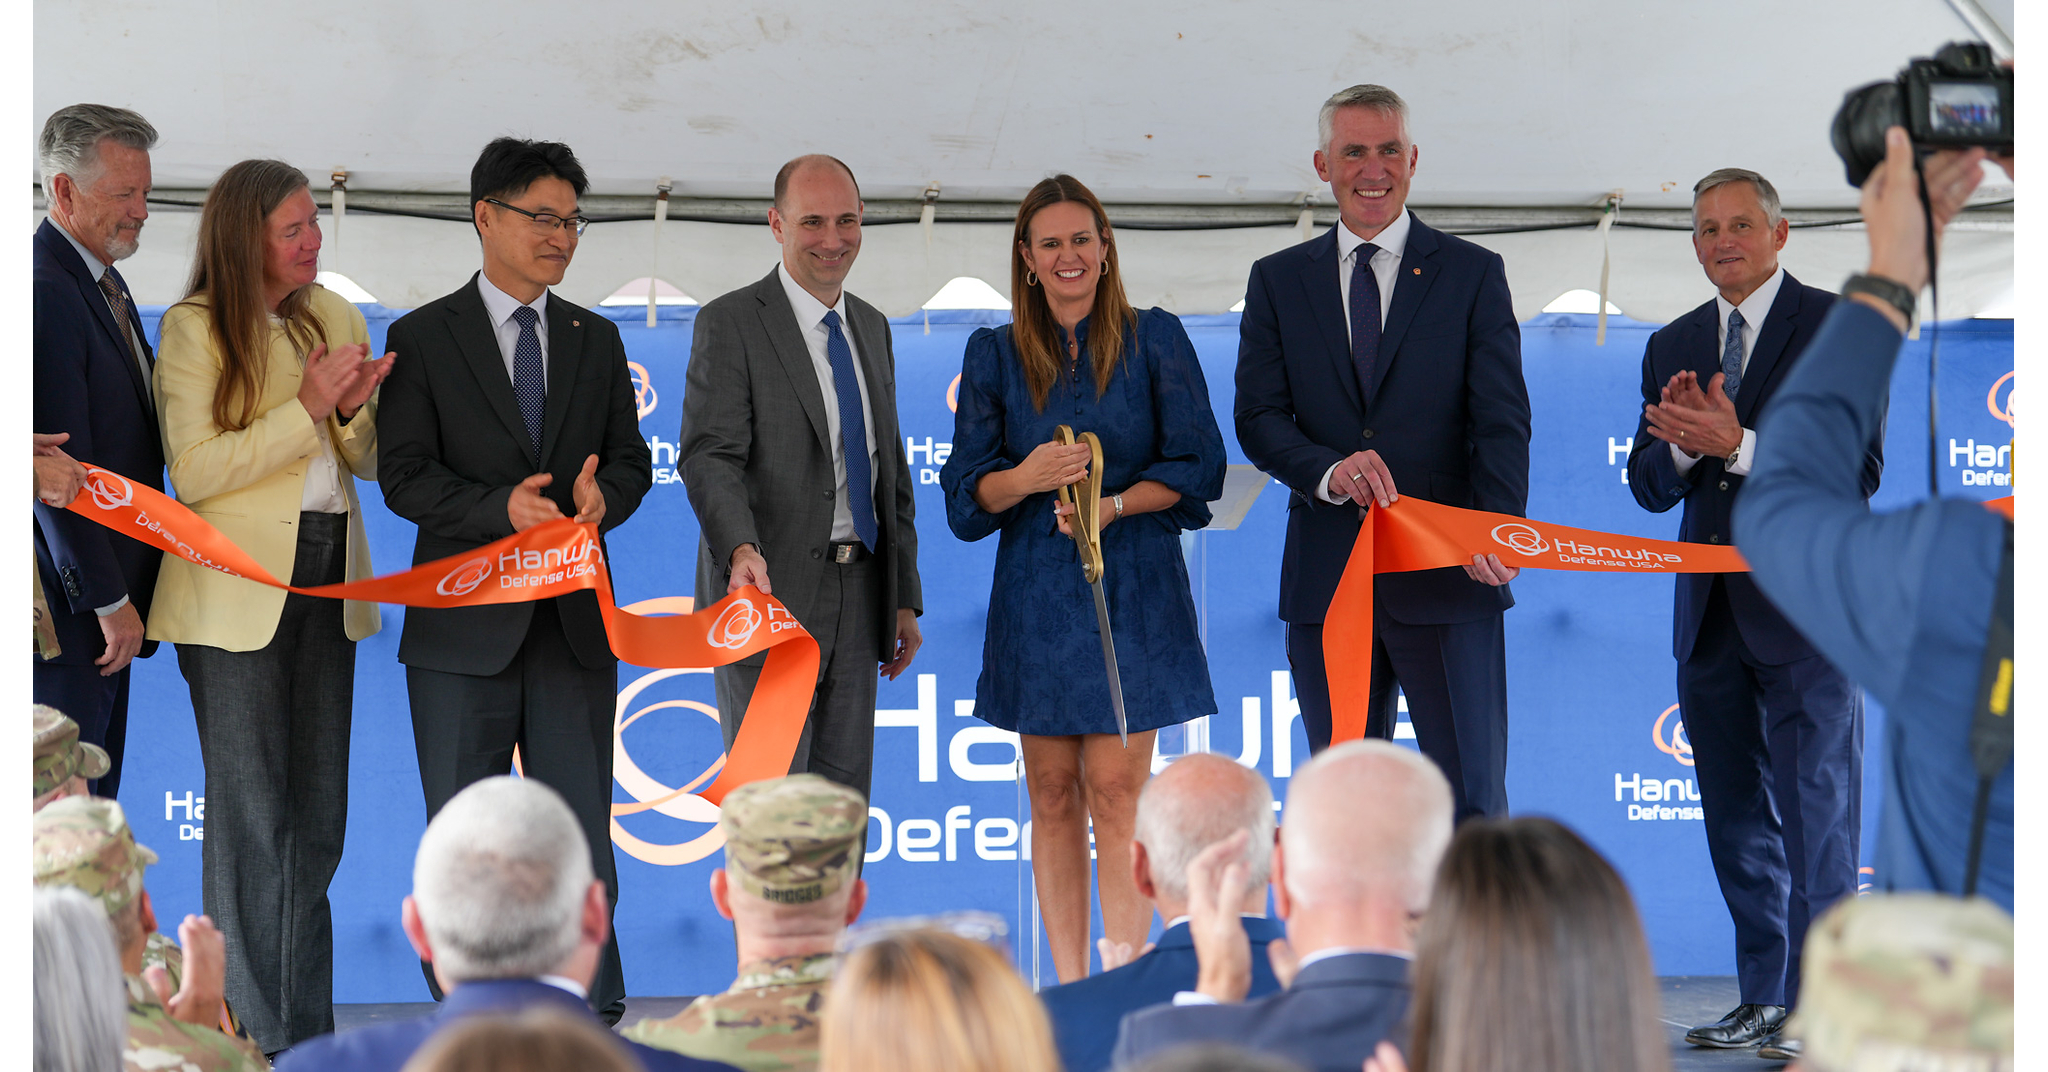
Hanwha Defense USA plans to invest $2.2 billion in an Advanced Manufacturing Campus at the U.S. Army's Pine Bluff Arsenal in Arkansas, targeting nearly 400 jobs over seven years. The facility will manufacture 155mm propellant charges and base-bleed units, expanding domestic munitions capacity and supporting modernization of the U.S. defense industrial base. The project is contingent on an eventual Army lease but represents a substantial U.S. expansion for Hanwha Aerospace's defense subsidiary.
Analysis
The economic signal is less the announced capital figure than the implied localization of a constrained midstream artillery component set. Domestic charge and range-extension capacity can raise throughput for U.S. shell assemblers without requiring each prime to duplicate the same process chain; GD is the most plausible indirect beneficiary because higher component availability improves ammunition-delivery execution and reduces working-capital and schedule risk. The likely competitive pressure falls on imported component suppliers and on incumbent domestic producers whose scarcity pricing has depended on bottlenecks rather than differentiated technology.
This is not yet a near-term earnings catalyst: the project’s long build-out, unfinalized lease language, and absence of disclosed multiyear procurement awards mean the market cannot underwrite utilization or returns on capital. For Hanwha Aerospace (012450.KS), the first 1-3 month catalyst is a binding Army/DoD offtake framework or appropriations linkage; over 6-18 months, signed volume commitments could justify a U.S.-defense multiple re-rating, while unsupported capex would instead dilute FCF and elevate execution risk. The unusually capital-intensive footprint relative to direct employment points to automation, but also raises commissioning and qualification risk.
Consensus may overread this as immediately additive to U.S. defense-prime revenue. A larger industrial base can be strategically positive while compressing unit economics if demand normalizes after emergency replenishment; the relevant variable is funded artillery consumption and replenishment targets, not announced capacity. Thesis falsifiers are a delayed lease/permit process, lack of FY2027-FY2028 procurement funding, or evidence that component supply expansion lowers realized ammunition pricing faster than it lifts shipment volumes.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Key Decisions for Investors
- Do not chase 012450.KS on the announcement alone. Place an event-driven buy watch only after a binding lease plus disclosed multiyear DoD offtake or funded production award; use a 6-12 month, approximately 2:1 upside/downside framework, with the thesis invalidated by capex escalation or no contracted utilization by the next annual results cycle.
- Maintain a constructive watch on GD as the cleaner listed U.S. ammunition-throughput exposure, but require confirmation in backlog, Aerospace/Combat Systems shipment guidance, or Army production orders before adding. The opportunity is 6-18 months; the key risk is that added component supply reduces pricing rather than increases delivered volume.
- Avoid shorting LMT, NOC, or RTX on presumed competitive disruption: their exposure is too diversified and the facility does not directly displace their principal weapons franchises. Reassess only if procurement shifts from prime-led ammunition contracts toward component-level competitive sourcing.
- Monitor FY2027 defense appropriations, Army multiyear munitions contract announcements, and U.S. propellant/explosives input availability as gating data. If funding lags capacity commitments, treat 012450.KS as a capex-risk story rather than a U.S. growth catalyst.
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Latest Oil Market News and Analysis for Sept. 22
- Oil Settles Near $100 as Hormuz Flows Stunt Rally