
Acquisition Lets AI and Operators Learn From Nearly $2 Billion in Annual Aesthetics Transactions
Source: PR Newswire
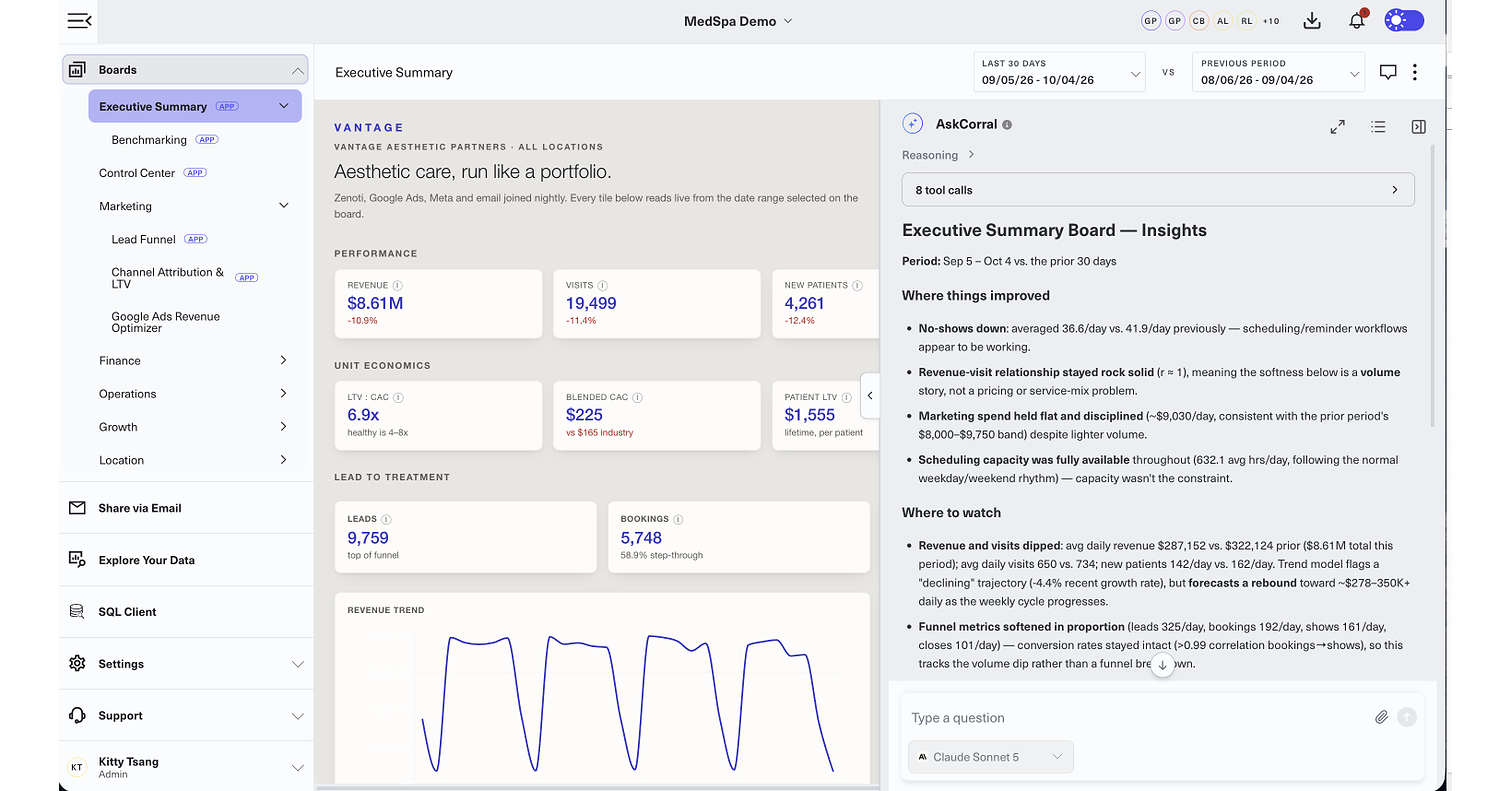
CorralData acquired The Data Co, bringing customers including Cosmetic Physician Partners and Aesthetic Partners onto its analytics and AI platform. Combined coverage includes many of North America's largest aesthetics groups and nearly $2 billion in annual aesthetics transactions. The platform adds peer benchmarks and AI recommendations using aggregated, anonymized data; the announcement disclosed no deal terms or quantified financial impact.
Analysis
The strategic asset is not the AI interface but the possibility of a better operating dataset: comparable clinic-level outcomes could make CorralData harder to replace and support cross-selling beyond aesthetics. That advantage is conditional. Benchmark quality depends on consistent definitions, clean integrations and enough retained customers; adding clinics alone does not establish product efficacy or pricing power. If managers use the tools to shift spend toward repeat-visit channels, lead-generation vendors and agencies paid for first-time bookings could lose share, while operators with weak retention or provider utilization may face faster site-level restructuring. Practice-management and EHR vendors could be pressured if customers increasingly rely on a neutral analytics layer, but could blunt that threat by improving their own reporting and data access.
Near term, this is a private-company capability signal, not a clean public-equity catalyst: deal economics, customer retention, adoption and revenue contribution are undisclosed. Over 1–3 months, verify whether CPP/AP clinics actually deploy the product and whether CorralData discloses measurable expansion; over 6–18 months, the test is whether benchmarks improve retention or utilization enough to support renewals and expansion across other verticals. Risks include integration friction, inconsistent source data, customer concentration and privacy or competition scrutiny around aggregated peer benchmarks. Anonymization reduces—but does not eliminate—those concerns. The contrarian read is that broader data access may be overvalued: a benchmark is useful only if clinics can act on it, and heterogeneous systems can make comparisons misleading. No listed company is identified in the supplied mapping, so there is no high-conviction direct trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No immediate trade: CorralData and the acquired business are private, and the release provides no transaction terms or independently verified financial impact. Avoid treating the announcement as evidence of near-term listed-sector earnings upside.
- Set a 1–3 month diligence alert for customer deployment, retention, and measurable changes in repeat bookings, provider utilization, or marketing ROI. If those indicators are absent, treat the claimed data-network advantage as unproven.
- Monitor practice-management/EHR and healthcare analytics vendors for signs of neutral-platform displacement or, conversely, improved interoperability and bundled analytics. Reassess only if customer wins, churn, or pricing evidence establishes a material competitive effect.
- Falsification watch: integration delays, customer attrition, weak adoption, or privacy/regulatory limits on peer benchmarking would undermine the network-effect thesis; repeatable operating improvements and expansion beyond aesthetics would strengthen it.
More News
- Asia shares subdued, bonds swamped by AI debt wave
- Elon Musk blames Indian 'oligarchs' for stalling Starlink launch
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Megacaps Are Back Driving the US Stock Rally in Hot-Running Economy
- Levi Strauss hikes profit guidance after tariff refunds, but its sales outlook is less optimistic
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI in Asset Management: 2026 Statistics That Hold Up
- What is Broker Research and RMS Systems (And How to Actually Use Them)