
CLERHP presents its 2026-28 Business Plan, projecting $784 million in revenue
Source: PR Newswire
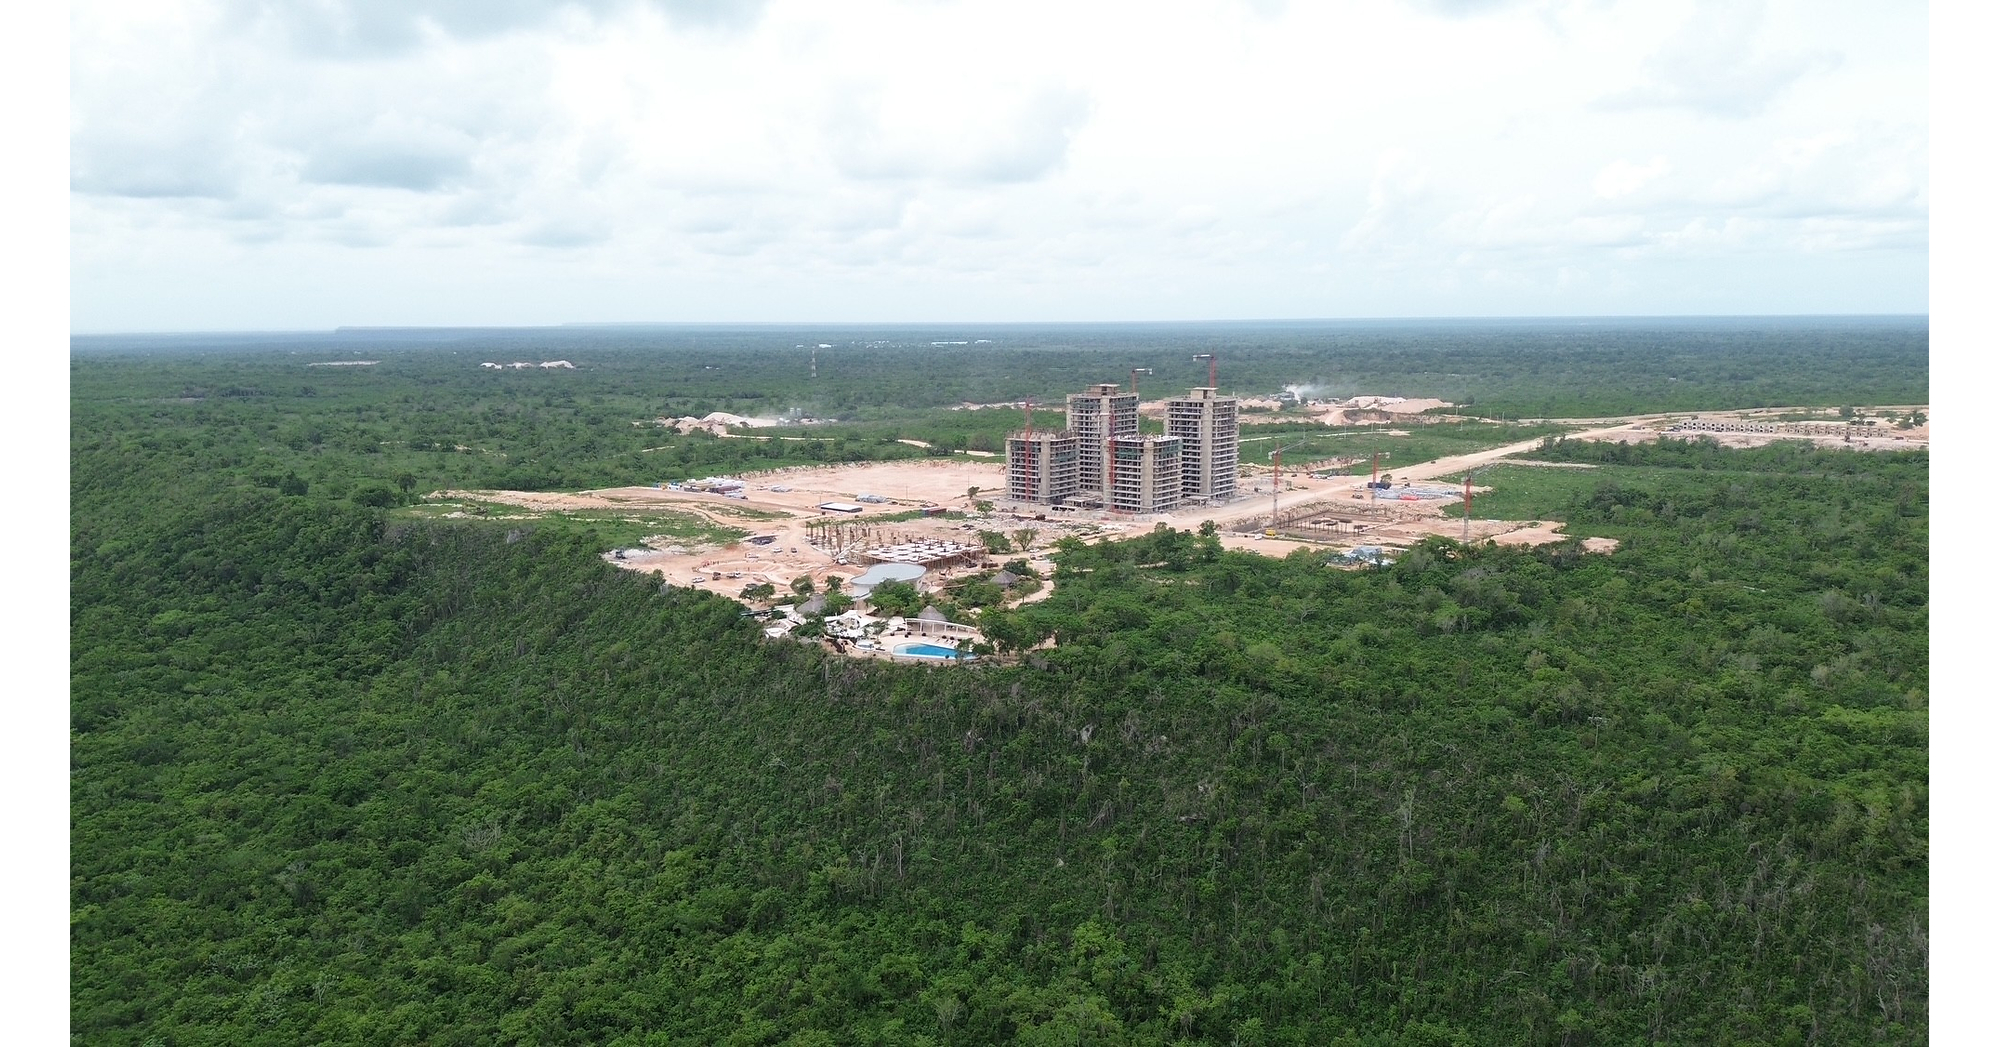
CLERHP's 2026–28 business plan projects $784 million in revenue, $252 million in EBITDA and $162 million in net income; $224 million of projected EBITDA would come from real estate development. Larimar City & Resort has reached $400 million in sales, while the company reports $56 million in project financing, including $22 million in bonds and $33 million in private debt, and $13 million in cash. CLERHP plans to begin dividends in 2027, allocating 25% of profits to shareholder distributions.
Analysis
The key underwriting issue is conversion, not demand headlines: the $400 million of sales cannot be treated as recognized revenue or cash until the company discloses contract terms, collections, cancellations and delivery schedules. The plan’s implied EBITDA margin is about 32%, with roughly 89% of projected EBITDA attributed to real estate development. That makes the proposed shift toward engineering, services and operations less of a near-term diversification than the five-business-line framing suggests; execution remains concentrated in Larimar City & Resort and Dominican Republic property development.
Near term, the plan may support sentiment, but the $13 million reported cash balance and project financing make funding cadence and construction obligations important to monitor. Over 1–3 months, evidence of buyer deposits converting to collections, permits, infrastructure delivery and recognized revenue matters more than additional sales announcements. Over 6–18 months, delays or cost overruns could undermine EBITDA conversion and the credibility of a 2027 dividend. A 25%-of-profits payout is not equivalent to distributable cash: development capex, debt service and working capital compete for funds.
Contrarian angle: the headline sales figure may be priced as a de-risked backlog even though the release does not establish cash collected, delivery timing or project-level returns. Conversely, if audited reporting demonstrates strong collections and margins, the market may be underestimating the recurring services and third-party project opportunity. Verify valuation, liquidity, debt terms and cash-flow disclosures before sizing; do not infer them from the release.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Ticker Sentiment
Key Decisions for Investors
- Do not chase CLR solely on the plan announcement. Treat it as a high-execution-risk, concentrated real-estate exposure; reassess after the next reported results provide presales-to-cash conversion, revenue recognition, project costs and debt maturities.
- Set a 1–3 month watch for cancellations/refunds, collections against reported sales, permits and infrastructure milestones, and revisions to the 2026–28 forecast. If sales growth is not accompanied by cash receipts and recognized revenue, the thesis weakens even if bookings remain strong.
- Treat the 2027 dividend as contingent, not a yield catalyst, until cash flow after capex, debt service and working-capital needs is disclosed. A payout announcement unsupported by recurring free cash flow would be a potential reversal trigger.
- No options or peer pair trade is justified from this release alone. Revisit a small, risk-limited long only after confirming valuation and trading liquidity alongside project financing terms; falsifiers include forecast cuts, material delivery delays, rising project debt or weak cash conversion.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- Why is Rocket Lab stock tumbling today?
- Traders pile into 'bubble puts' on CoreWeave as neocloud stocks plunge
- Why is Netwealth stock sliding today?