
Ballard finalise l'acquisition de GeoPura et devient ainsi un fournisseur intégré de solutions énergétiques à l'hydrogène
Source: PR Newswire
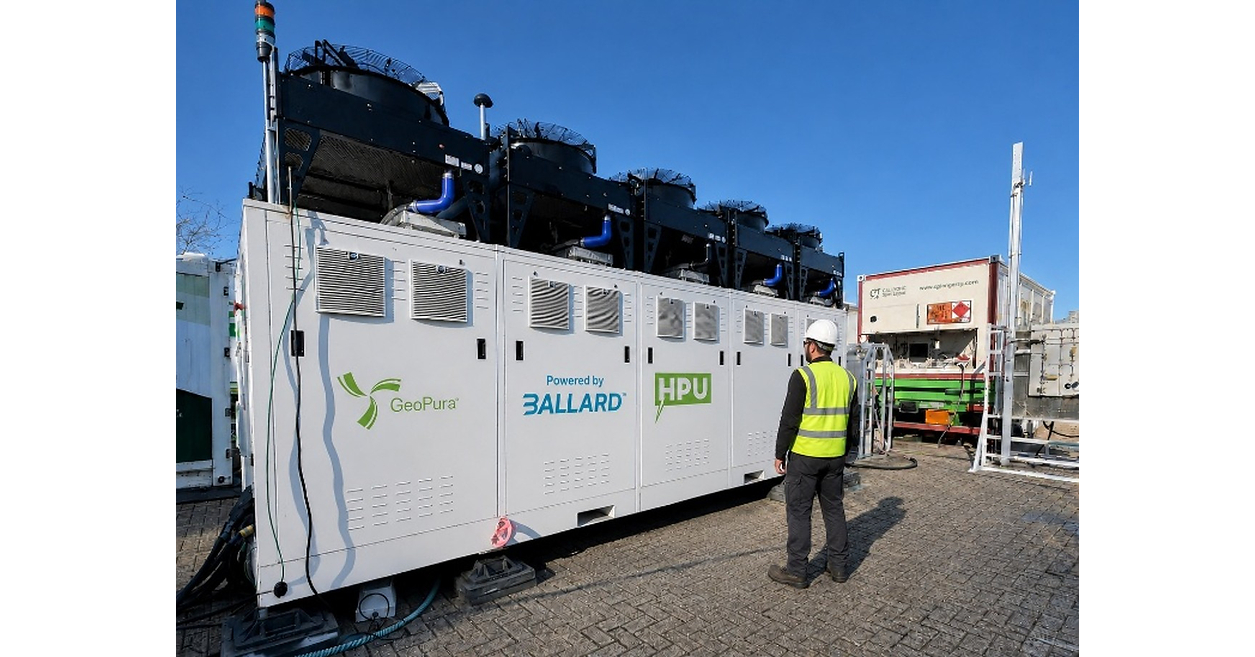
Ballard Power Systems has finalized its acquisition of GeoPura, creating a vertically integrated hydrogen energy solutions and “energy-as-a-service” platform. The deal value is £275.0m upfront (including £82.5m cash plus newly issued Ballard shares and restricted stock) and adds up to an additional £27.5m conditional consideration if financial targets are met post-close. On a pro forma basis, GeoPura’s former shareholders will hold ~14.1% of Ballard, strengthening Ballard’s European presence while expanding commercial opportunities in North America.
Analysis
This is more of a narrative de-risking event than an immediate earnings inflection. The strategic value is that BLDP is no longer selling only a component; it can now package uptime, fuel, logistics and service-level guarantees into one contract, which should improve win rates in markets where customers care more about reliability than stack efficiency. The catch is that the economics move from a relatively asset-light technology model toward a more capital-intensive service platform, so the market should not assume margin expansion just because the product is "integrated."
The second-order effect is competitive: this raises the bar for smaller hydrogen players that lack fuel sourcing or deployment infrastructure, while putting pressure on diesel genset rental and temporary power incumbents that compete on convenience rather than zero-emission branding. Over the next 1-3 quarters, the key variable is utilization: if GeoPura-style units sit idle between projects, BLDP inherits working-capital drag and lower returns on invested capital; if utilization tightens, the bundle becomes a moat. That makes this a capacity-management story as much as a technology story.
The contrarian point is that investors may be overrating the significance of vertical integration in a still-immature end market. Buying distribution and fuel capability can also be read as proof that standalone fuel-cell demand is not yet strong enough to justify organic scale, which means dilution and integration risk matter more than press-release synergy language. Falsifiers are simple: if the next two earnings prints do not show better backlog conversion, improved service gross margin, and a slower cash burn rate, the market should fade the re-rating over 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Initiate only a small tactical long BLDP on post-deal weakness, with a 1-3 month horizon; thesis is improved order conversion and a stronger service narrative, but exit if cash burn or gross margin deteriorates next quarter.
- Pair trade: long BLDP / short PLUG for 1-3 months. BLDP has the cleaner execution story and a more credible integrated-service model; risk is a broad hydrogen sentiment squeeze that lifts both names.
- If BLDP rallies sharply on the headline, fade the move rather than chase it; the deal is strategically useful but does not yet prove accretive economics. Use any 10%+ pop as a signal to wait for the first post-close operating update.
- Watch URI and CMI as second-order losers in temporary power and off-grid generation if BLDP can prove uptime and fuel logistics at scale; if BLDP backlog does not accelerate, those incumbents remain the better risk-adjusted exposure.
More News
- Huge profits at tech and energy companies are masking this key trend
- Why this little known Chinese chipmaker has caused a global stock rout
- Apple releases HomeView smart home hub with screen as showcase for Siri AI
- Microsoft Eyes First Record in Nearly a Year as AI Rally Builds
- Russia's Oil Exports Slow as Black Sea Loading Takes Longer
- Why did investors react so negatively to Schneider-PTC deal? M&A expert weighs in