
Celine Dion’s Soft Power in France Meets Hard Budget Times
Source: Bloomberg
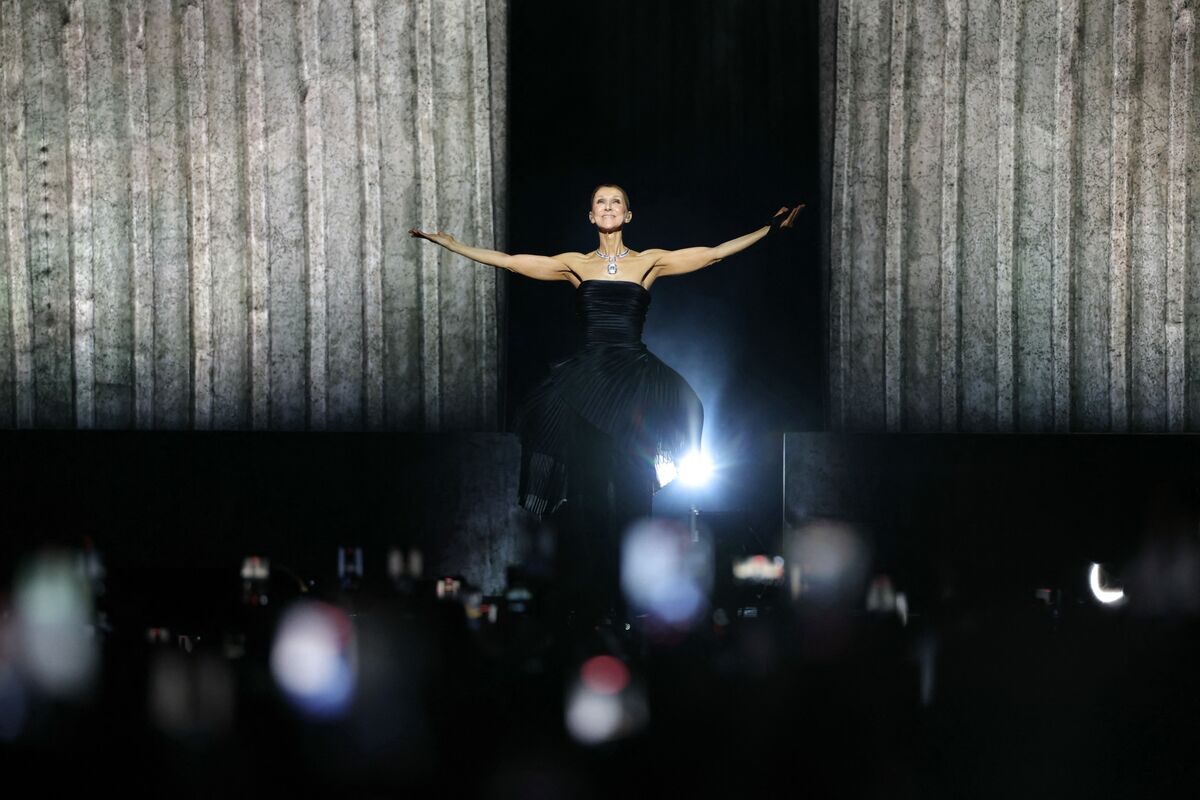
Celine Dion’s return from a six-year health-related hiatus, with more than a dozen Paris-area shows at roughly three concerts per week, is expected to provide a modest economic boost to the French capital. The tourism and spending windfall offers limited relief against France’s broader fiscal pressures and weak growth outlook, and is unlikely to materially alter the country’s economic trajectory.
Analysis
The investable read-through is not the performer-specific revenue but the marginal-demand signal for Paris discretionary spend: concerts concentrate high-intent visitors into hotels, restaurants, local transit and premium retail, sectors whose earnings are sensitive to occupancy and revenue per available room rather than headline tourist counts. A short-lived event can lift weekly pricing, but it is unlikely to alter quarterly guidance for listed French consumer or hospitality exposures unless it coincides with broader evidence of inbound-demand resilience.
Near term, watch Accor (AC) for booking-window strength and Paris RevPAR commentary, as well as Air France-KLM (AF) for premium-leisure yield trends. Luxury names LVMH (MC), Kering (KER) and Hermes (RMS) have only a weak direct benefit: affluent visitor traffic helps conversion at flagship stores, but Chinese demand, FX and US consumption remain overwhelmingly larger earnings drivers. The more meaningful second-order effect is that event-led tourism may partially cushion central-Paris service employment and VAT receipts, marginally reducing downside to local consumption rather than changing France's fiscal trajectory.
Consensus should resist extrapolating sold-out cultural events into a French demand recovery. Event visitors often substitute spending from other entertainment and domestic travel budgets; persistent gains require hotel occupancy and airline yields to remain elevated after the concert window. A deterioration in euro-area PMIs, renewed transport disruption, or weak post-event booking data would falsify any tourism-led resilience thesis within one to three months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.08
Key Decisions for Investors
- No standalone event-driven trade: the estimated macro and company-level earnings effect is too small relative to France-wide growth, fiscal and FX variables.
- Set a 1-3 month monitoring alert on Accor (AC): consider a tactical long only if Paris/France RevPAR and forward bookings accelerate through the post-event period while management maintains or raises full-year guidance; exit on a RevPAR deceleration or guidance cut. This is a data-dependent watch item, not a current recommendation.
- Avoid using LVMH (MC), Kering (KER), or Hermes (RMS) as direct proxies for this demand impulse; any short-term flagship traffic benefit is unlikely to overcome their larger exposure to global luxury demand and currency translation.
- For macro positioning, require confirmation from French retail sales, services PMI, and tourism receipts before treating event demand as evidence against a bearish France-consumption view; absent confirmation, retain preference for diversified European travel exposure over France-only consumer cyclicals.
More News
- Kevin Warsh just revealed a huge change for the Fed. The press missed it
- Bank of Japan Hike Could Reshape Yen Carry Trade
- European Economies Eye Another Energy Crisis Heading Into Winter
- Three words from Kevin Warsh have Wall Street wondering how far the Fed will go with rate hikes
- American, United and Southwest are all cutting ‘marginal routes’ as jet fuel prices spike
- Time for Cyclical Sector ETFs?