
Xinhua Silk Road: Jiaxing Nanhu Airport gains strong momentum in global aviation logistics hub landscape
Source: PR Newswire
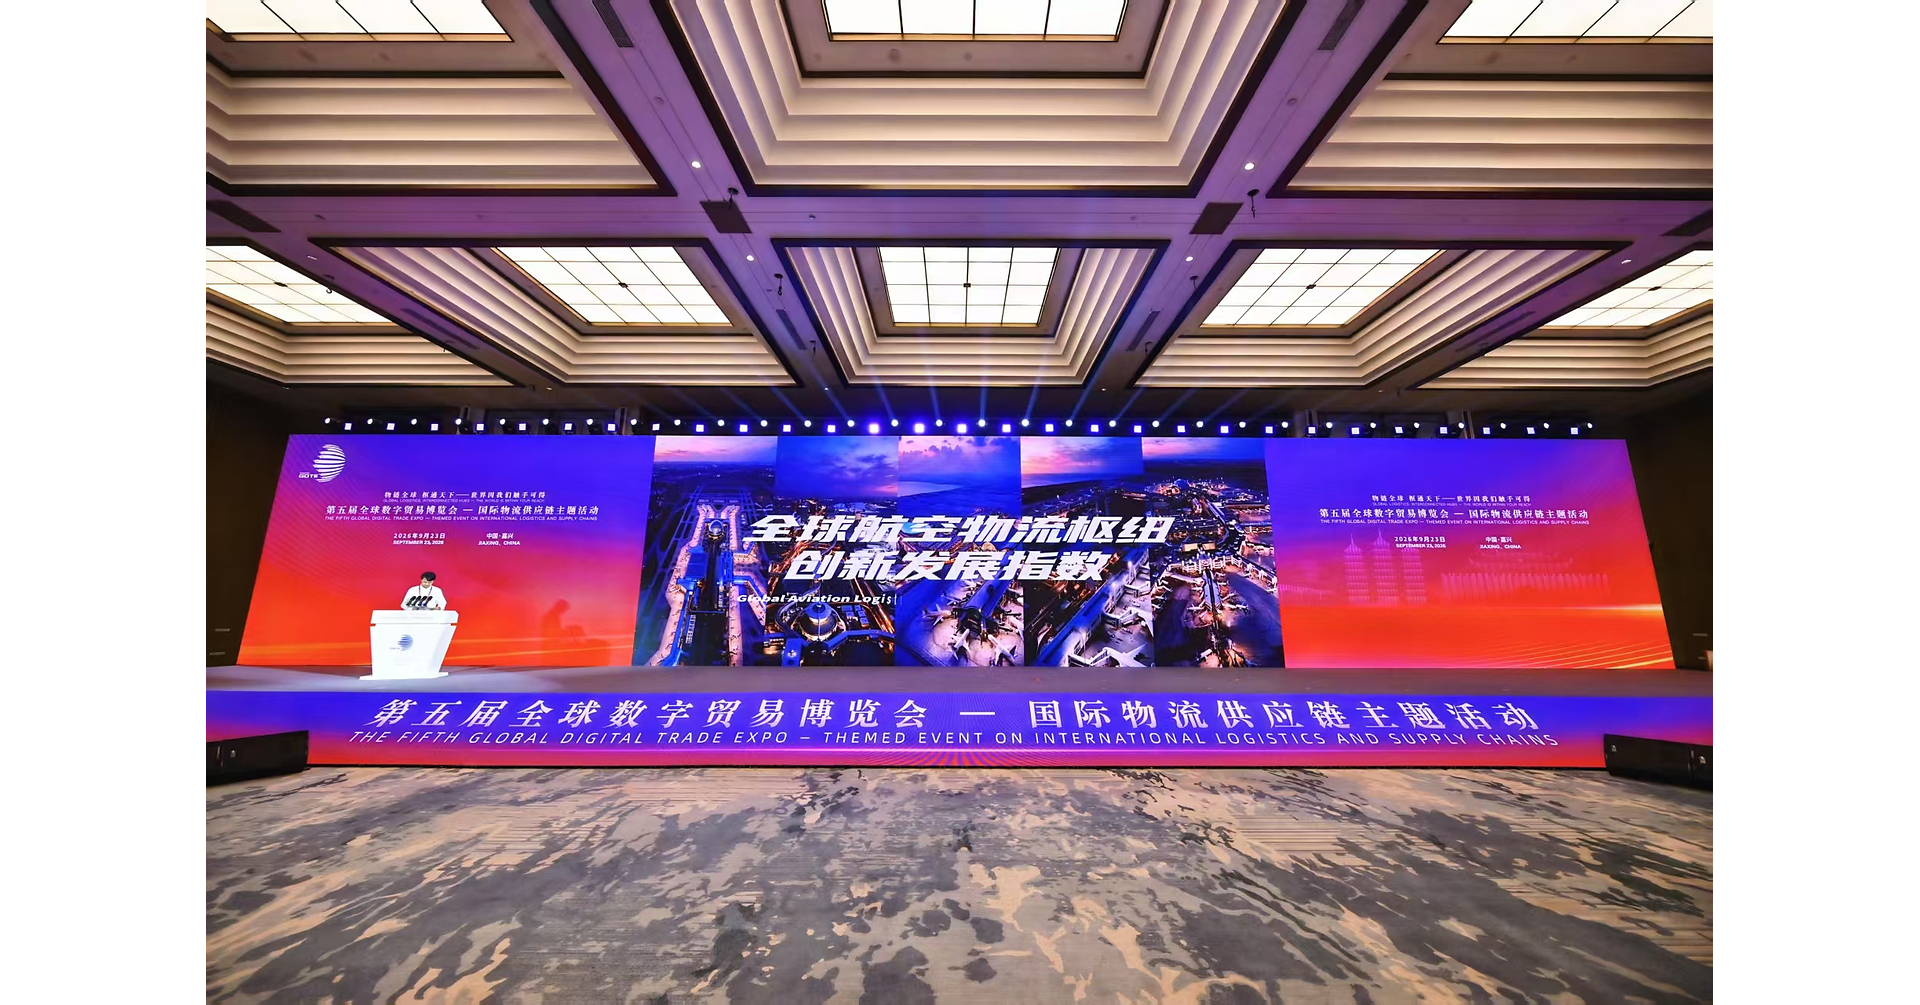
Jiaxing Nanhu Airport's YTO Skyhub, which began operating at the end of 2025, is gaining momentum as a global aviation-logistics hub, supported by a 12.2 billion yuan investment. The facility has designed annual cargo and mail capacity of 1.1 million metric tons, with long-term capacity expected to reach 2.4 million tons. Its development is underpinned by Yangtze River Delta trade flows, where 2025 goods imports and exports reached $2.2 trillion, or 35.2% of China's total.
Analysis
The relevant listed-company read-through is YTO Express (600233 CH), but the asset’s strategic value is unlikely to translate into near-term earnings without evidence of route density, third-party utilization and unit-cost improvement. A dedicated hub can improve sortation economics and reduce reliance on Shanghai-area capacity, yet initial ramp typically creates depreciation, labor and load-factor drag; the first 12-24 months are more likely to pressure reported margins than expand them. SF Holding (002352 CH) and JD Logistics (2618 HK) face a modest competitive threat only if YTO converts infrastructure into superior next-day coverage in the Yangtze River Delta rather than merely adding capacity to an already competitive parcel market.
The second-order opportunity is in cross-border e-commerce fulfillment, where proximity to export manufacturing and customs integration could shift marginal volume from truck-to-Shanghai routing toward direct air consolidation. This would favor operators with captive merchant flow and customs/data integration, while Shanghai Airport (600009 CH) is not necessarily a loser: regional capacity expansion can relieve congestion and support broader cargo growth, but it weakens scarcity-value arguments for cargo aeronautical pricing over a multi-year horizon. The promotional source and index methodology provide no independently verifiable throughput, yield, carrier-commitment or utilization data, so this is not a standalone catalyst.
Near term, treat this as a monitoring signal rather than a directional trade. The thesis becomes investable over 1-3 quarters if YTO discloses sustained hub volumes, international route additions, and parcel cost-per-ticket improvement while capital expenditure remains within cash-flow capacity. It is falsified if utilization stays low, express-delivery price competition intensifies, or incremental depreciation drives YTO’s operating margin below sector peers despite volume growth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate position based solely on this release; place YTO Express (600233 CH) on watch for quarterly disclosures of cargo throughput, utilization, capex and express unit-cost trends. Initiate only after two quarters of evidence that incremental volume is improving, rather than diluting, operating margin.
- Monitor a 6-18 month relative-value setup: long YTO Express (600233 CH) versus short a basket of SF Holding (002352 CH) and JD Logistics (2618 HK) only if YTO demonstrates faster Yangtze River Delta cross-border volume growth with stable pricing. Avoid the pair if sector-wide parcel pricing falls, as margin compression would dominate network advantages.
- For Shanghai Airport (600009 CH), do not extrapolate regional hub development into a bearish view without cargo-yield evidence. Reassess if cargo-related revenue per ton or airline capacity utilization weakens for two consecutive reporting periods; otherwise broader regional trade growth may offset competitive supply.
- Key alert: carrier contracts and third-party freight forwarder adoption matter more than designed capacity. A disclosed anchor-carrier commitment or measurable international e-commerce lane expansion would be the first credible catalyst; absent that, assign a low probability to material earnings impact within the next 12 months.
More News
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Trump-Xi summit: Four key takeaways from the Washington, DC, meeting
- Trump, Xi Address AI, Taiwan During State Visit
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- China's Xi urges U.S. to cooperate on AI
- Trump Hosts China’s Xi With Trade, AI, Taiwan in Focus
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can Hedge Funds Use ChatGPT? A Control Framework
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash