
Reimagined Ocean Bar Debuts on Oosterdam with Expanded Entertainment
Source: PR Newswire
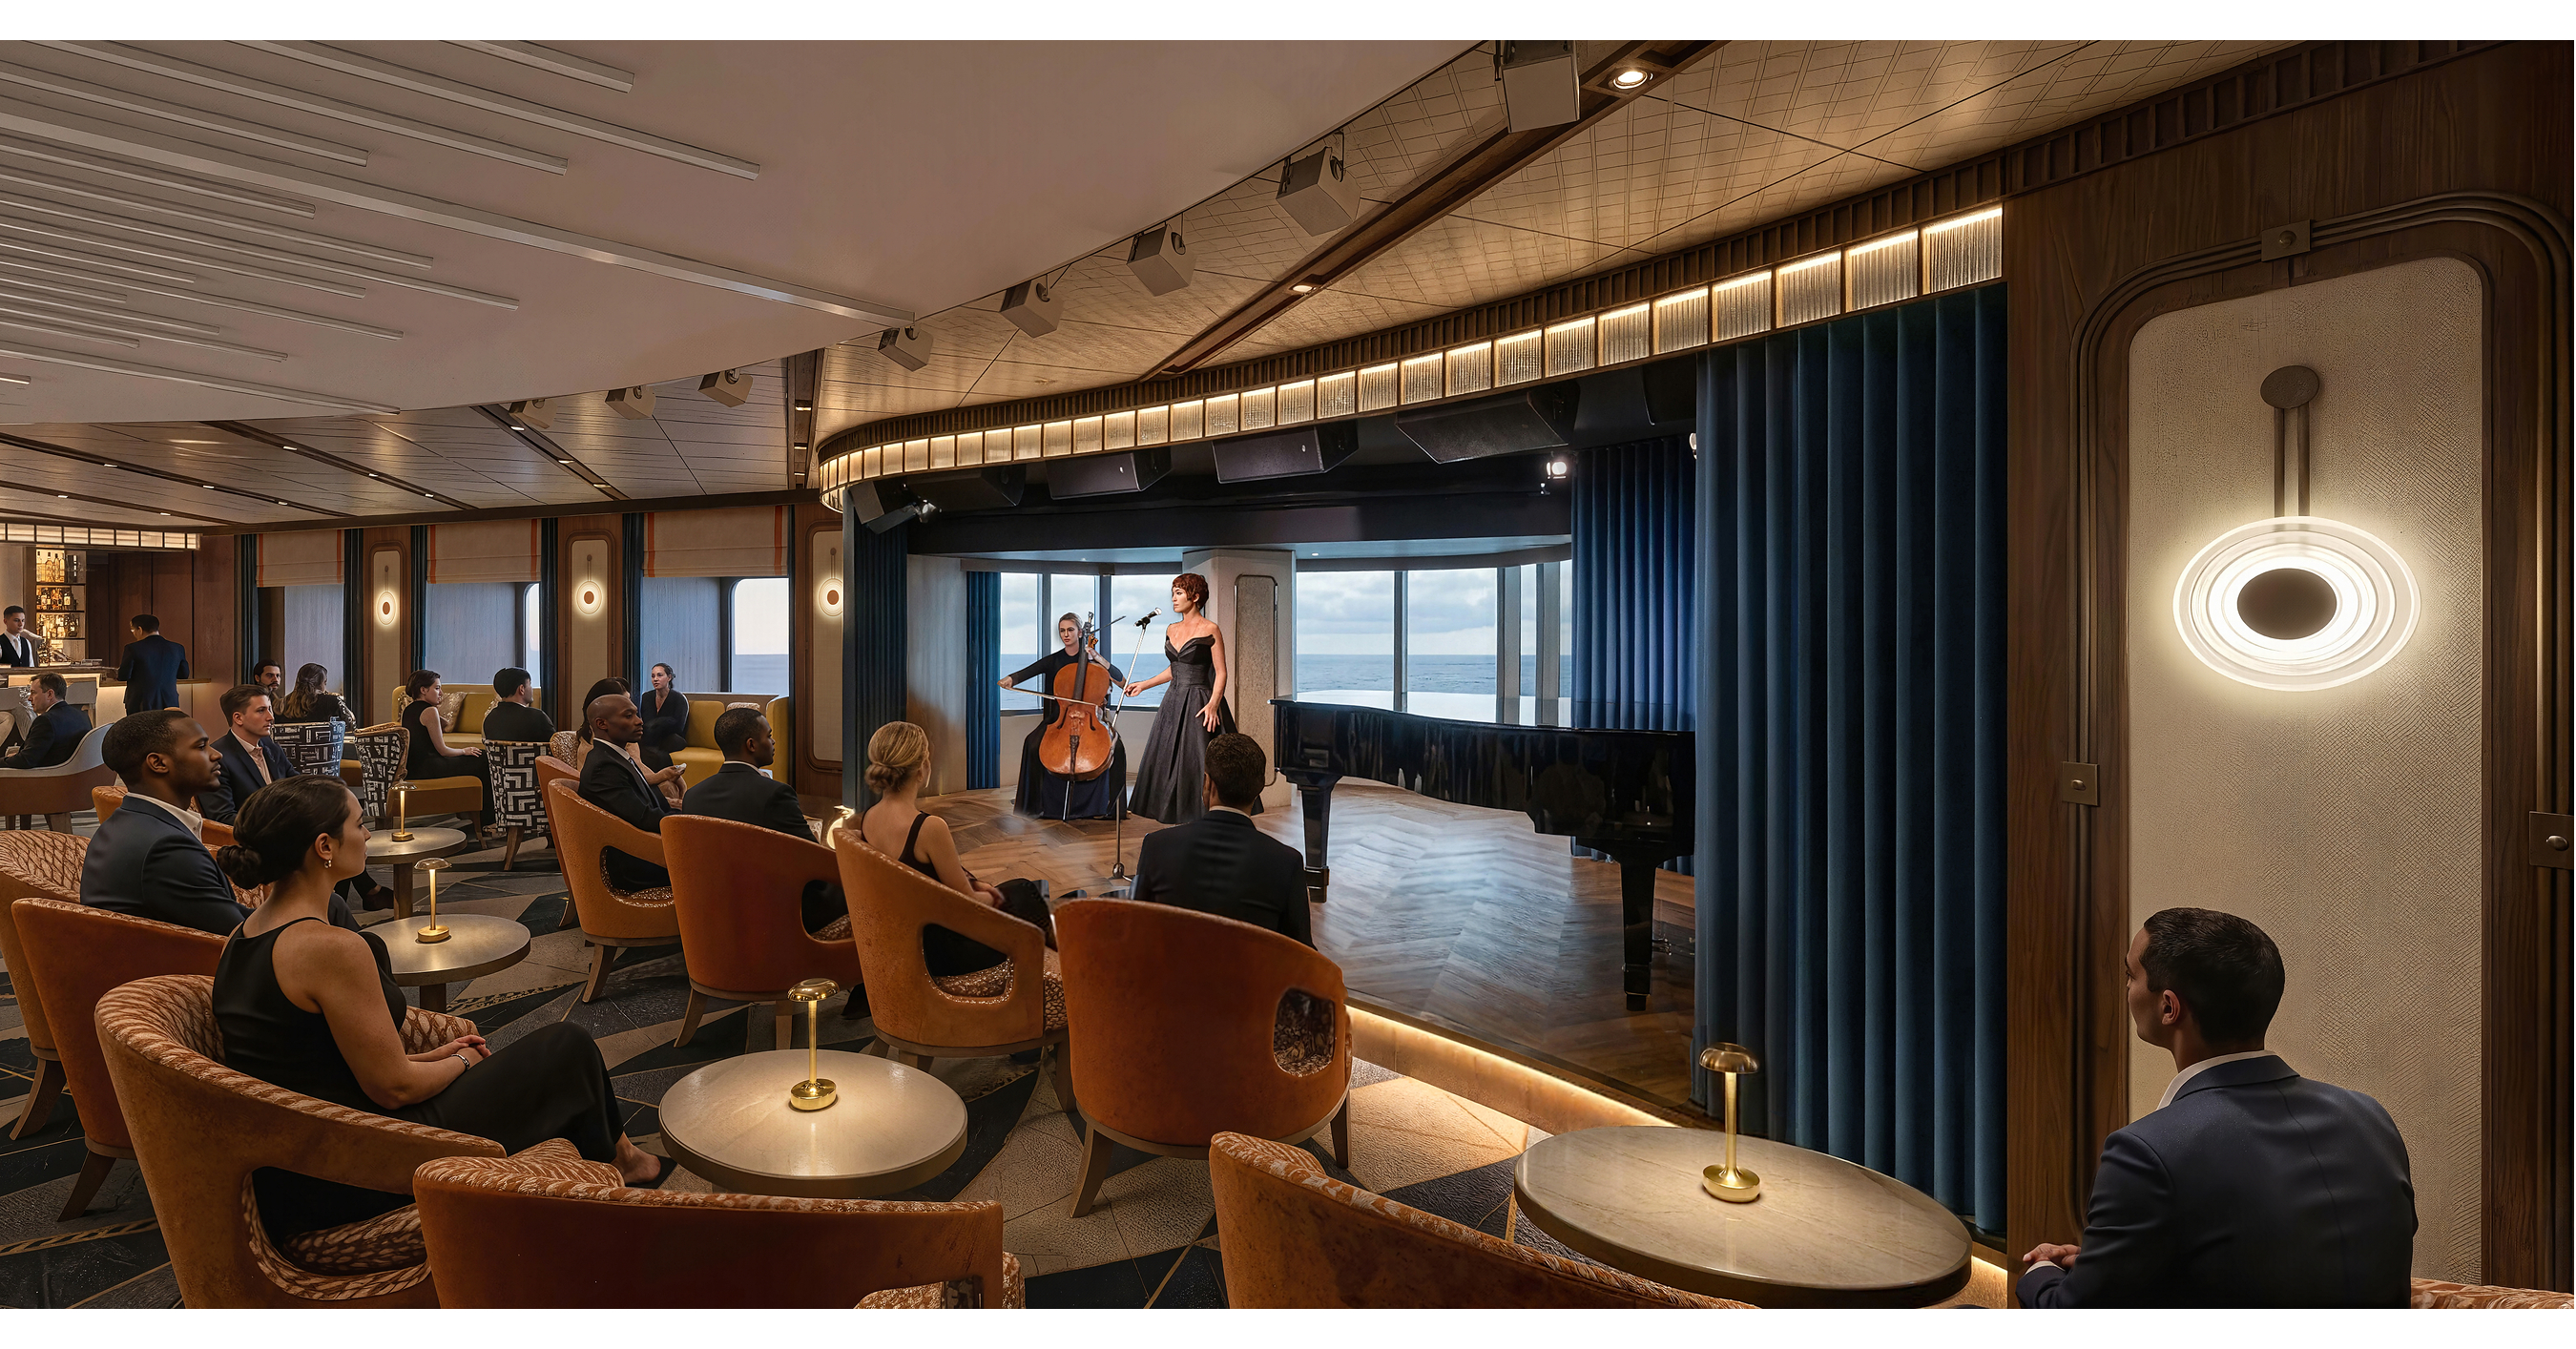
Holland America Line’s “Evolution” upgrade launches a redesigned Ocean Bar on Oosterdam with a new stage, expanded live music (including Vivace Strings and late-night cabaret), and a relocated bar to bring guests closer to performances. The company says it will invest more than $500M across six Vista and Signature Class ships, starting with Oosterdam and Zuiderdam, with bookings now open after refurbishments. The announcement is a positive demand/experience signal but is unlikely to materially move markets immediately.
Analysis
This is more about mix than size: the market will likely underappreciate whether these refurbishments lift onboard spend per available berth and reduce the premium-discount to larger rivals. If the redesign meaningfully increases dwell time in public spaces, the upside is not ticket price but higher beverage, specialty dining, and retention economics — the kind of incremental margin that compounds over multiple sailings. That said, the headline capex is still small relative to fleet economics, so the first reaction is more likely to be a modest sentiment bump than a rerating.
The competitive angle is nuanced. For CCL, the real test is whether this helps the brand defend pricing against RCL’s premium product without requiring a broad-based discounting war; if it does, the payoff shows up in 1-3 quarters via yield and onboard revenue, not immediately in the stock. For peers like TNL, there is little direct read-through, but any evidence that mature ships can be refreshed cheaply to sustain occupancy is a reminder that brand investment can be a better use of capital than aggressive share repurchases when demand is stable.
The contrarian view is that investors may be overvaluing the press-release signal and undervaluing execution risk. A tasteful venue upgrade does not solve the bigger issues for cruise equity: leverage sensitivity, fuel/FX volatility, and the need for sustained pricing power to offset fixed costs. If the next two quarters do not show improved ticket yield, onboard spend, or Net Promoter-style commentary, this becomes cosmetic spend with limited multiple impact.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Stay neutral-to-slightly constructive on CCL over the next 1-3 months; the catalyst is only real if upcoming booking/yield commentary shows 100-200 bps improvement in premium onboard spend metrics.
- Use CCL strength into the announcement to sell covered calls or trim exposure; the market is likely to price this as maintenance capex unless management quantifies incremental revenue uplift.
- Watch the next earnings call for evidence that refurbished ships are outperforming fleet averages on ticket yield and onboard revenue; if not, fade any post-newsoutperformance.
- Relative value: consider a small long CCL / short TNL pair only if CCL starts proving premiumization economics, since the trade is about brand monetization rather than sector beta.
- Falsifier for a constructive view: if refurb rollout triggers capex creep, delays, or no measurable booking uplift within 1-2 quarters, treat this as neutral and remove it from the bull case.
More News
- Trump Says US Team Met With Iranians at UNGA
- ‘I have a big decision to make’: Trump had a ‘good meeting’ with Iranian officials warning he may ‘annihilate the Islamic Republic’
- Bank of America says Brent crude oil could top $150 a barrel if Iran war disruptions persist
- Paramount will need to release way more movies to make this merger work
- U.S. regulators rush to write crypto rulebook after Clarity Act stalls in Senate
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts