
Envision Energy posiluje trh s větrnou energií v jihovýchodní Evropě: Největší větrný projekt v Severní Makedonii dosáhl finančního uzavření
Source: PR Newswire
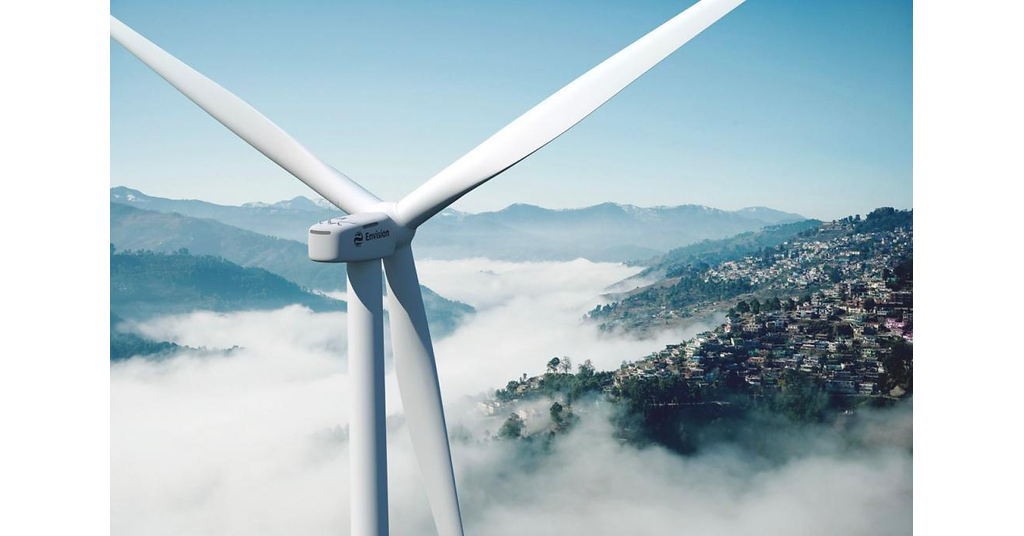
The 131.25MW first phase of the Štip wind farm in North Macedonia reached financial close, marking the country’s largest wind-energy project to date. Envision Energy will supply 21 EN182 onshore turbines rated at 6.25MW each, while the three-phase project could ultimately reach 396MW and more than quadruple North Macedonia’s installed wind capacity. Financing support and bankability recognition from EBRD, IFC and Erste, alongside a long-term private power-purchase agreement, strengthen the project’s commercial viability and Envision’s position in Southeast European renewables.
Analysis
This is strategically useful validation for Envision's European financing credibility, but economically immaterial for listed wind-equipment peers in isolation: a 21-unit order is unlikely to move Vestas (VWS.CO), Nordex (NDX1.DE), or Siemens Energy (ENR.DE) revenue estimates. The second-order issue is competitive: multilateral lender acceptance reduces a historical procurement advantage held by incumbent European OEMs in emerging Europe, where financing eligibility can matter more than turbine headline price. If replicated across the Balkans, this could incrementally pressure OEM pricing and service-contract attachment rates over the next 12-24 months.
The key underwriting risk is not turbine delivery but merchant/PPA and grid economics. An unrated or undisclosed corporate offtaker, local congestion, and cross-border power-price volatility can impair project economics even with construction financing in place; these risks become more relevant as later phases seek capital. Near term, there is no identifiable public-equity earnings catalyst. Over 1-3 months, watch for a disclosed offtaker, EPC scope, turbine-service terms, and transmission upgrades; over 6-18 months, successful commissioning would make lender-approved Chinese OEM equipment a more credible substitute in EBRD/IFC-backed procurement.
Contrarian view: the press-release framing overstates the read-through from one financed project to a broad European market-share inflection. European developers still value local service networks, availability guarantees, political-risk mitigation, and procurement compliance—areas where Vestas and Nordex retain entrenched advantages. The thesis turns more material only if Envision wins multiple follow-on Balkan tenders or if incumbents acknowledge pricing pressure in regional order intake or margins.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- No directional action on EBS: the provided ticker has no demonstrated economic linkage to the project, and the named technology provider/developer are not clearly investable public-equity exposures.
- Maintain a 6-12 month watchlist on VWS.CO and NDX1.DE for Balkan tender awards and order-book pricing; consider a relative short only if Envision secures additional lender-backed regional projects and either incumbent reports lower service attachment or turbine gross-margin pressure.
- For ENR.DE, treat this as neutral rather than a wind-equipment catalyst: its equity remains more sensitive to grid technology, gas-power execution, and balance-sheet de-risking than to a small onshore-turbine order. Reassess only if regional project financing translates into material grid-equipment awards.
- Set an alert for financing/contracting of subsequent project phases and for disclosure of the offtaker's identity and credit support. A credible investment-grade counterparty plus completed grid connection would strengthen the competitive-incumbent risk; delayed commissioning, curtailed output, or PPA repricing would falsify it.
More News
- Why is Booking stock sliding today?
- Oil falls on report Asia will import highest volume of crude since start of Iran war
- Japan's 10-year bond yield hits 30-year high following sell-off in Treasurys
- America’s Asian allies want a Trump-Xi truce — but not at their expense
- US Debt Selloff Spans Most Maturities: Evening Briefing Americas
- Chinese authorities reportedly in possession of F-35 components in Hong Kong