
Xinhua Silk Road : de la visite d'un temple à une escapade sur une île : l'île de Meizhou, dans le Fujian, renforce son attrait touristique
Source: PR Newswire
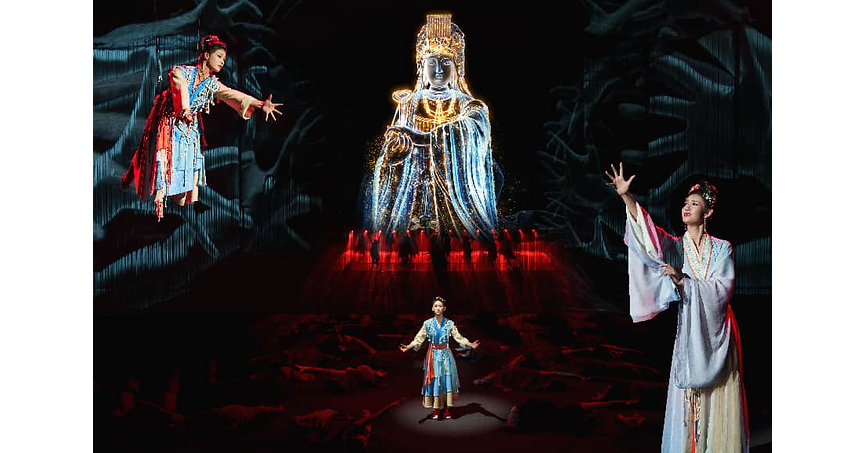
Meizhou Island welcomed approximately 3.23 million visitors in 2025, surpassing 3 million for the first time as it expanded from Mazu temple visits into longer-stay leisure tourism. The Fujian destination is adding cultural experiences, performances and nighttime activities to attract families, self-driving tourists and younger visitors, supporting higher visitor retention and local tourism spending.
Analysis
This is not a tradable company-specific catalyst; it is promotional destination-marketing content with no disclosed lodging inventory, visitor spend, transport capacity, or listed corporate beneficiary. The relevant mechanism is modestly supportive for Fujian regional leisure demand, but the reported visitor mix shift only matters economically if overnight stays and per-capita spend rise faster than marketing/event subsidies and local infrastructure costs.
For public markets, any impact is too diffuse to move national travel platforms or hotel operators. A sustained increase in multi-day coastal travel could marginally support China domestic-travel demand indicators for Trip.com (TCOM), Tongcheng Travel (0780.HK), and budget/midscale hotel chains such as H World (HTHT), but Meizhou alone is immaterial relative to their network-wide booking bases. The more useful read-through is qualitative: cultural-IP packaging and evening entertainment can increase destination monetization by expanding hotel, food-and-beverage, local transport, and ticketed-event attach rates rather than simply increasing admissions.
Over the next 1-3 months, verify whether holiday-period room rates, ferry/air capacity utilization, and hotel occupancy in Putian rise; absent those data, there is no basis to extrapolate revenue. Over 6-18 months, the thesis would be weakened by weak Chinese discretionary spending, weather disruption, transport bottlenecks, or local price competition that converts visitor growth into low-margin volume. Consensus is likely correct to ignore this item: cultural-tourism initiatives are only investable when they become visible in regional RevPAR, OTA gross merchandise value, or company guidance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone trade: do not position in TCOM, 0780.HK, or HTHT on this release alone; the stated impact is geographically immaterial and lacks independently verifiable spend or occupancy data.
- Add a monitoring alert ahead of Golden Week and the next quarterly results cycle: consider a tactical long TCOM only if domestic hotel/attraction booking growth and management commentary indicate broad coastal leisure acceleration, not isolated pilgrimage traffic. Falsifier: flat domestic hotel booking growth or lower take-rate/guidance.
- For China consumer exposure, prefer a diversified travel basket rather than a destination-specific thesis: long TCOM versus a China discretionary retailer with higher promotional and inventory sensitivity can be considered only after OTA booking data confirm improving domestic trip duration and accommodation demand.
More News
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
- New York sues Polymarket over allegations of illegal gambling operations
- Argentina’s poverty rises to 32 percent under Milei with more pain forecast
- New York sues Polymarket U.S., two months after filing lawsuit against Kalshi
- Meta nears first new high in a year as Muse success showcases winning AI strategy