
Arizona Biltmore and Wrigley Mansion Reunite for a New Era of Hospitality
Source: PRWeb
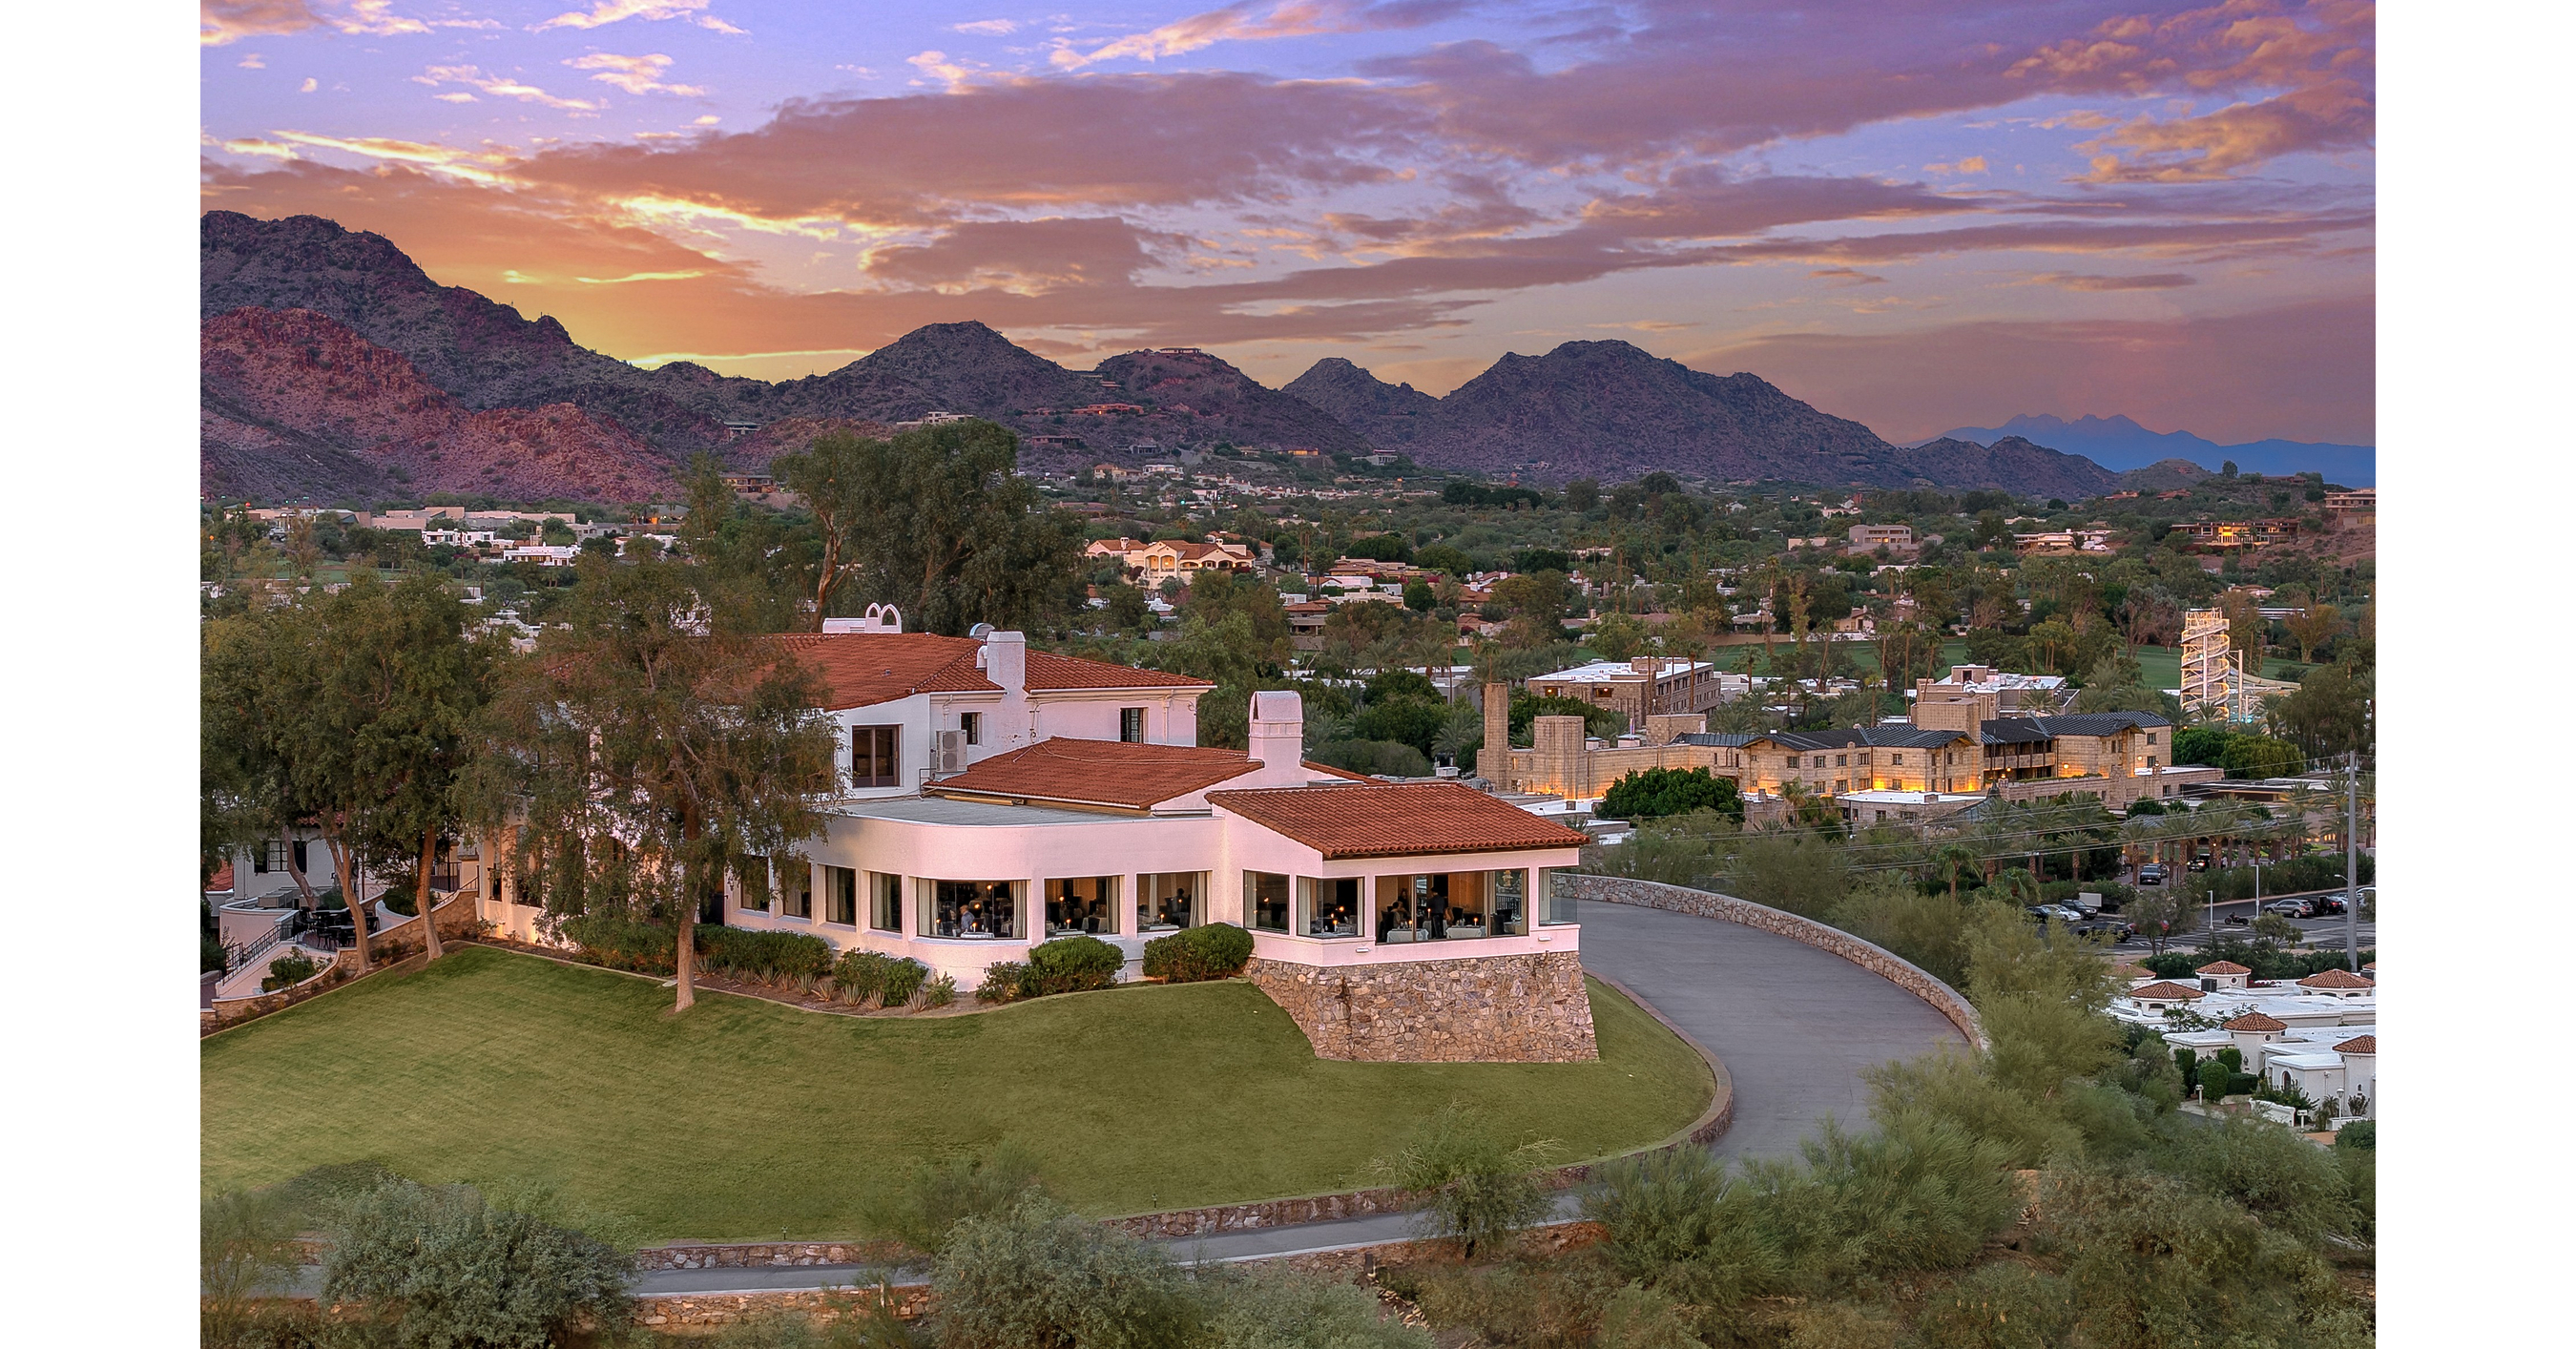
Arizona Biltmore and neighboring Wrigley Mansion are now under common ownership through a Henderson Park-led joint venture with Western & Southern Financial Group and funds managed by Hamilton Lane, South Street Partners and Pyramid Global Hospitality. Pyramid will operate both Phoenix hospitality assets, integrating Wrigley Mansion's Michelin-recognized Christopher's restaurant and broader dining, event and wellness offerings into the Arizona Biltmore platform. The transaction is positioned as an enhancement to the destination's luxury and culinary appeal, though no purchase price or financial terms were disclosed.
Analysis
This is immaterial to HLNE’s near-term earnings or valuation: the firm is one of several capital providers, the assets are private, and no transaction value, equity check, leverage package, or fee economics were disclosed. The only investable read-through is incremental evidence that institutional private-capital vehicles continue to allocate toward experiential real estate with pricing power, particularly scarce luxury assets that can combine lodging, food-and-beverage, events, and wellness revenue.
The operating upside depends less on combining the properties than on realizing cross-property spend, higher group/event capture, and premium ADR support without diluting the Mansion’s local luxury positioning. A shared operator can reduce back-office and procurement costs, but labor intensity and elevated food costs limit margin conversion; the meaningful payoff is likely 12-36 months, after brand integration and revenue-management optimization rather than in the next quarter.
For HLNE, consensus should not extrapolate one co-investment into a material acceleration in FRE or realizations. The potentially constructive second-order effect is fundraising: visible participation alongside insurers and specialist hospitality sponsors can broaden Hamilton Lane’s access to evergreen/private-real-estate allocations. That thesis requires evidence in subsequent AUM flows and fee-related earnings, not publicity around a single property.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in HLNE on this announcement; the disclosed information is insufficient to quantify invested capital, management fees, or mark-to-market impact.
- Maintain HLNE as a watch-list long only if the next two reporting periods show sustained private-markets AUM inflows and fee-related earnings growth above consensus; use any broad alternative-asset-manager selloff rather than this event as entry timing.
- For a hospitality-real-estate expression, monitor public luxury lodging proxies such as H and MAR for Phoenix group-demand and ADR data, but do not infer a direct earnings benefit: the assets are privately held and operator economics are undisclosed.
- Falsifier for the modestly constructive HLNE read-through: weaker fundraising, declining management-fee margins, or evidence that institutional allocations are shifting away from private real estate due to refinancing costs and cap-rate pressure.
More News
- Mark Ruffalo says Paramount’s $111 billion Warner Bros. deal ‘Will stifle creativity, weaken free speech, and cost people their jobs’
- David Ellison says combined Paramount and Warner Bros. Discovery will be named Skydance
- Paramount and Warner Bros Discovery to become Skydance
- Broadcom, Amazon Test Limits of Investor Demand for AI Buildout
- Paramount’s Warner Bros. megamerger will just be called Skydance
- David Ellison goes minimalist with his new name for his Paramount-Skydance-Warner-Bros-Discovery empire
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?