
CityUHK (Dongguan) marks 2026 Opening Convocation Ceremony, celebrating rapid cross-border growth in the Greater Bay Area
Source: PR Newswire
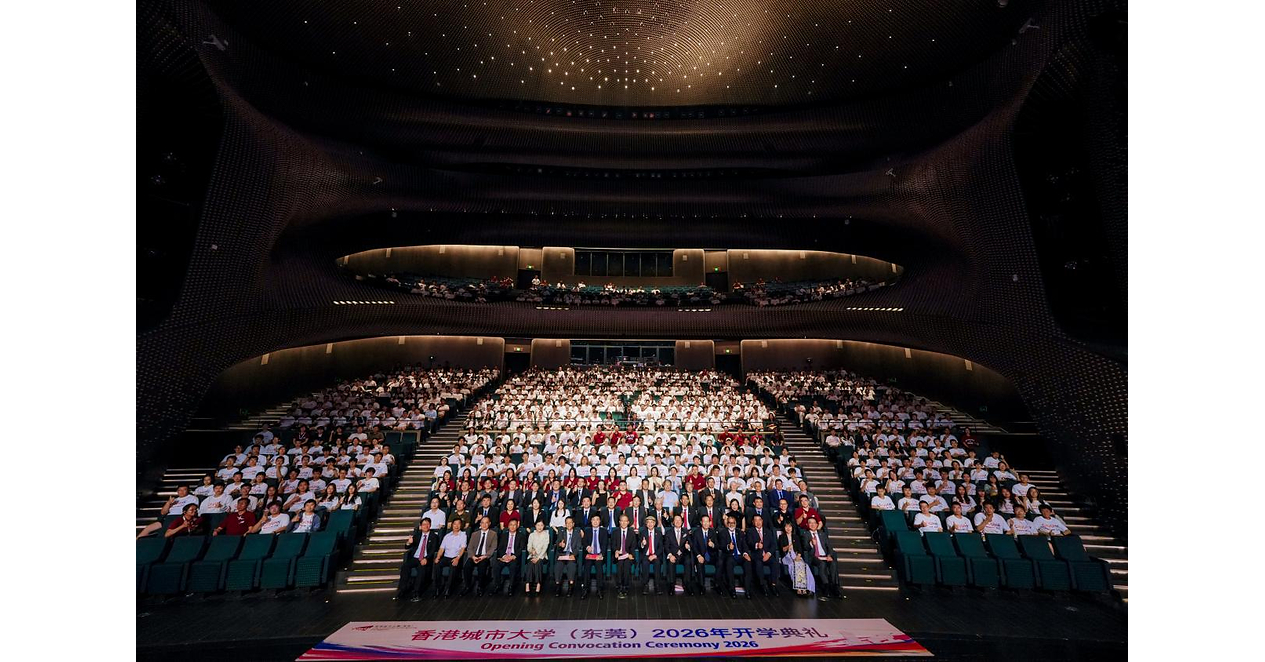
City University of Hong Kong (Dongguan) held its 2026 Opening Convocation Ceremony on 2 Sep 2026, welcoming its third student intake of 1,300+ students. The article highlights post-launch growth since 2024, improved undergraduate admissions standards, and expanded recruitment across Hong Kong, Macao, Taiwan, and more international students. Overall framing is positive but provides no material financial or market-moving data.
Analysis
This reads more like a credibility milestone than a tradable earnings event. The real mechanism is that a successful cross-border campus with stronger admissions quality can act as a flywheel for donor funding, postgraduate applications, and government support, but the revenue sensitivity for any listed proxy is still likely small in the next 1-3 quarters. The market should be cautious about extrapolating one strong intake into a durable valuation step-up unless the school can show pricing power, recurrent research income, and sustained international enrollment.
Second-order winners are adjacent real-estate and service providers in the Greater Bay Area: student housing, local retail, transit, and campus facilities benefit if enrollment keeps compounding, but those are slow-burn effects rather than immediate catalysts. The more important competitive effect is on lower-tier private institutions and test-prep operators: elite cross-border options pull away the best marginal students, which can worsen pricing and retention for weaker schools. That said, if policy support or quota expansion is not forthcoming, the competitive moat may remain narrow and the story stays reputational.
Contrarian view: the consensus is likely overestimating the ability of branding to translate into cash flow. A few thousand students is meaningful for campus optics, not necessarily for listed equity value, especially if the model relies on continued regulatory goodwill. What would falsify the positive read-through is flat or declining application quality next cycle, no evidence of tuition uplift, or any tightening in cross-border education policy that slows future cohorts.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No immediate trade in CEGHF/UNIB/WWRL on this release alone; wait for audited enrollment, tuition mix, and operating margin disclosure over the next 1-2 earnings cycles.
- If CEGHF is the closest listed proxy for premium China higher education, use it only as a tactical long on pullbacks after confirmation of sustained admissions strength; target 6-12 months, with thesis broken if growth or pricing stalls.
- Watch lower-tier China education names as relative shorts over 6-18 months if elite cross-border campuses continue to absorb top students; the trade works only if weaker operators report softer enrollment or higher marketing spend.
- Set a policy alert on Greater Bay Area cross-border education rules and subsidy announcements; any restriction or quota change would be the fastest catalyst to unwind the bullish structural view.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Tesla is taking $250,000 deposits for a Roadster with SpaceX thrusters. The FAA says it isn’t an aircraft
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test