
Seanergy Maritime: Perpetually Undervalued, Maintaining Strong Buy
Source: seekingalpha.com
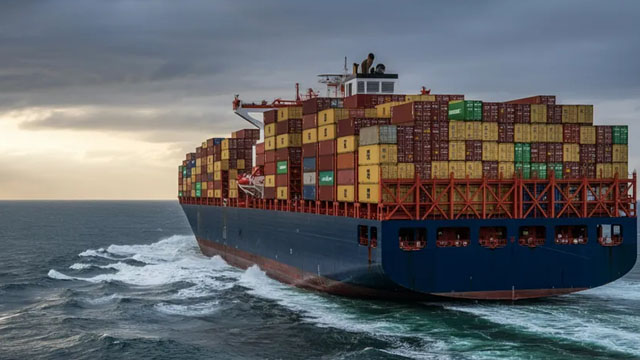
Seanergy Maritime was reaffirmed as a Strong Buy, with its price target raised to $25 on robust Capesize shipping fundamentals. The recent share-price decline was attributed to an ex-dividend adjustment and commodity-price movements rather than deterioration in operating performance or trade volumes. The company's fixed charter book is viewed as undervalued, with Q3 and Q4 time-charter-equivalent results projected to exceed company guidance by about $5.7 million per quarter.
Analysis
The investable question is not whether Capesize spot economics are healthy, but whether SHIP’s contracted earnings can close the valuation gap before rates normalize. A $5.7M quarterly TCE upside versus guidance would be meaningful for a micro-cap owner because incremental charter revenue has limited operating-cost leakage; however, the market will likely capitalize it at a discount until management demonstrates that excess cash is retained, used for accretive debt reduction/buybacks, or returned consistently rather than absorbed by fleet renewal.
Near term, the catalyst path is Q3/Q4 reported TCE and booked-vs-spot disclosure: two consecutive beats could force NAV/earnings estimate revisions over the next 1-3 months. The principal risk is that the apparent discount reflects duration, not mispricing—Capesize freight is highly exposed to Chinese steel demand, Brazilian iron-ore exports, and fleet supply. A sudden decline in iron-ore volumes or a weaker forward curve would compress SHIP’s earnings multiple before fixed-charter upside is fully recognized.
The more attractive expression may be relative rather than outright: SHIP has greater operating leverage to Capesize rates than diversified dry-bulk owners such as Star Bulk (SBLK) and Golden Ocean (GOGL), while its smaller capitalization and dividend mechanics create liquidity-driven volatility. Consensus may be over-attributing the recent decline to a benign technical adjustment; if the stock fails to recover after earnings despite a verified TCE beat, that would indicate investors are assigning a structurally higher governance/liquidity discount and undermine the $25 valuation framework.
Over 6-18 months, fleet supply discipline is the key structural variable. If newbuilding deliveries remain constrained and commodity tonne-miles hold, SHIP’s aging-fleet replacement optionality becomes valuable; if secondhand vessel values fall alongside rates, leverage and refinancing capacity matter more than near-term charter outperformance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Watch, rather than chase, SHIP into the next quarterly release; initiate only if reported TCE and forward fixtures validate at least the indicated ~$5.7M quarterly upside and the stock remains below a peer-normalized NAV discount. Target a 3-6 month rerating; size modestly given micro-cap liquidity.
- Use a relative-value structure: long SHIP / short SBLK or GOGL in dollar-neutral sizing after confirmation of the earnings beat. The thesis is superior near-term earnings torque; exit if SHIP’s TCE premium to its own guidance does not translate into higher forward booking or if Capesize forward rates weaken materially.
- Set a hard fundamental stop around a downward revision to fleet utilization, cash break-even, or 2026 charter coverage—not the ex-dividend price movement. Those metrics would show that the earnings surprise is transient rather than a rerating catalyst.
- Do not underwrite the $25 target from a single analyst estimate. Require disclosure of debt maturities, vessel-sale assumptions, and capital-allocation plans; absent those, treat the position as a freight-cycle trade rather than a durable NAV compounder.
More News
- South Korea’s exports hit record high on AI boom
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Greer urges G20 to back Trump tariff agenda, takes aim at China
- Asia stocks rise on chipmaker gains, soft U.S. inflation; Nikkei outperforms
- Why is Nidec stock plunging today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI in Asset Management: 2026 Statistics That Hold Up
- What is Broker Research and RMS Systems (And How to Actually Use Them)