
PPX Intercepts High-Grade Gold, Silver, and Copper at Callanquitas, Including 20.04 g/t Au over 0.85 m and 2251 g/t Ag With 3.0% Cu over 0.90 m
Source: Newswire
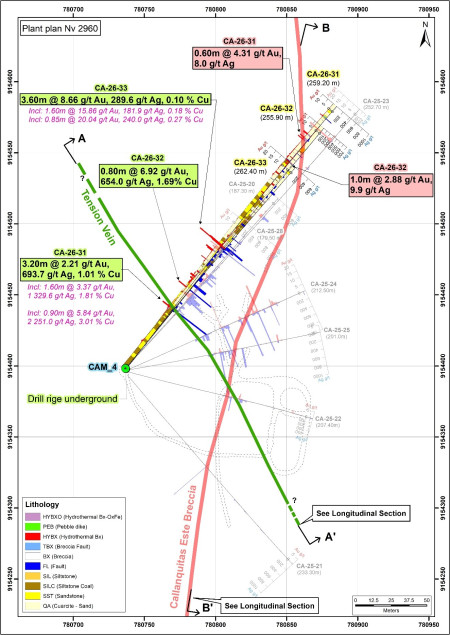
PPX Mining reported high-grade underground drill results at its Callanquitas Mine in Peru, led by 20.04 g/t gold over 0.85 m in hole CA-26-33 and 2,251 g/t silver with 3.01% copper over 0.90 m in CA-26-31. The Tension vein returned 8.66 g/t Au, 289.6 g/t Ag and 0.10% Cu over 3.60 m in CA-26-33, while drilling also confirmed the Callanquitas East oxide zone up to 75 m below prior drilling. Management said the results support continued exploration and future updates to sulfide and oxide resource estimates, with mineralization open northward and at depth.
Analysis
The marketable implication is not the headline grade but whether added sulfide tonnes can be converted into reserve-backed mine life without a disproportionate processing-capex or recovery penalty. Narrow, high-grade vein intercepts can materially improve recovered ounce economics, while the copper and silver credits could lower all-in sustaining costs; however, true widths, metallurgical recoveries, dilution, and mining geometry remain unreported. Until those variables are independently quantified in an updated technical report, this is exploration optionality rather than an earnings upgrade.
Near term, the stock may attract junior-mining momentum buyers, but liquidity in a TSX-V issuer makes any initial reaction vulnerable to reversal absent the pending assays and a resource update. Over 1-3 months, the key catalyst is whether step-out drilling demonstrates consistent grade and width beyond local infill success, particularly at depth and northward; confirmation could support a resource re-rating. Over 6-18 months, value realization depends on permitting, underground development execution, concentrate/payability terms for polymetallic sulfide material, and funding needs—each can dilute shareholders before mineralization reaches cash flow.
The contrarian view is that silver/copper-rich sulfide zones may be economically less straightforward than headline gold-equivalent intuition suggests: complex silver minerals and arsenopyrite-bearing material can raise treatment charges, penalties, or require separate flowsheet optimization. Conversely, if metallurgy demonstrates clean recoveries and payable credits, PPX becomes more levered to silver and copper than a conventional small gold developer, creating upside in a sustained precious/base-metals bull market. SGSN is the laboratory provider disclosed in the release, not an investable read-through beneficiary; this announcement does not change its earnings outlook.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No core position in PPX solely on this release. Place on a catalyst watchlist through the remaining 2026 assays and resource update; initiate only if continuity is demonstrated over meaningful step-out distances and the company discloses true-width, recovery, and resource-conversion evidence.
- For a speculative natural-resources sleeve, consider a small PPX long only after post-release liquidity normalizes, sized as binary exploration risk. Target a 2:1 upside/downside profile into the resource update; exit if pending holes fail to extend mineralization or if an equity raise is announced before a credible economic study.
- Use SILJ or GDXJ, rather than SGSN, for diversified exposure if the intended thesis is improving junior precious-metals exploration sentiment. This release alone is insufficient to support a sector allocation; require confirmation from gold/silver prices and broader junior-miner fund flows.
- Set diligence alerts for metallurgical testwork, concentrate specifications, treatment-charge assumptions, updated NI 43-101 resource estimates, and cash runway. A lower-grade resource update, adverse metallurgy, or financing at a material discount falsifies the re-rating thesis.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- Oil prices dip as U.S. inventory build offsets M.East supply jitters
- Iran war has cost Pentagon $38 billion and depleted missile stockpiles, CBO says
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say