
Hot Chili Limited - Quarterly Report, Period Ending 30 September 2026
Source: PR Newswire
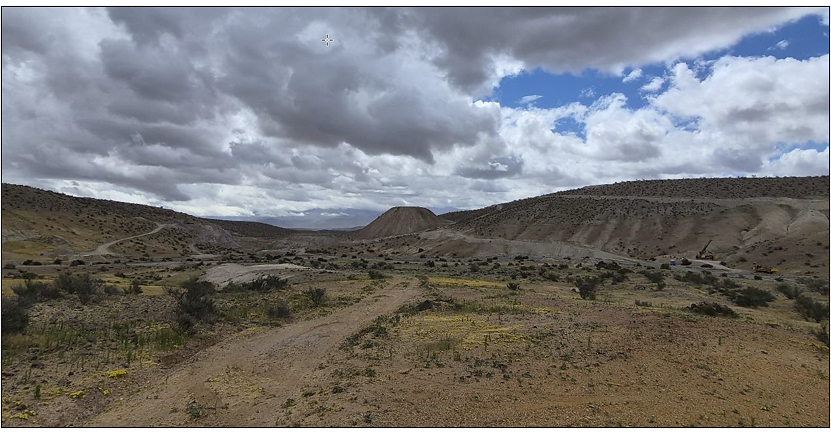
Hot Chili confirmed a second copper-gold porphyry centre at La Verde South, extending the interpreted project footprint to 1,400 m across two centres; step-out hole DKP084 returned 148 m at 0.44% CuEq, while diamond hole DKD100 visually recorded 307 m of porphyry-style mineralisation, with assays pending. The company completed 50,000 m of drilling at La Verde and reported A$29.3 million cash and no debt at 30 September 2026, after receiving A$20.4 million net from the OR royalty amendment. Costa Fuego EIA submissions remain targeted for Q2 2027 despite weather-related field delays; a strategic partnering process continues, with no certainty of a transaction.
Analysis
La Verde’s second centre could improve Costa Fuego’s scale and mine-plan flexibility, but the value is conditional: the new southern sulphide interval is visually described, not yet assayed, and the published CuEq relies on proxy recoveries. The key 1–3 month test is whether pending assays and the maiden resource convert footprint into coherent, mineable tonnes. A larger resource may lift project value while also increasing infrastructure, water, tailings and permitting demands; growth is not automatically a better return on capital.
The A$20.4m royalty proceeds reduce near-term equity-funding pressure, but the expanded royalty interest encumbers La Verde’s future economics and may complicate a strategic partner’s valuation. The change-of-control buyback terms matter: flexibility is not equivalent to a cost-free release. For OR Royalties (OR), the transaction adds exposure to a long-dated development outcome; without royalty-rate, buyback and asset-level valuation details, the impact on OR’s fair value is not measurable. Near term, the report’s positive exploration signal is partly offset by execution risk and the absence of a binding partner. Over 6–18 months, EIA progress, resource conversion, metallurgical results and partner terms—not drill footprint alone—will drive value. Contrarian point: market enthusiasm may overprice scale before recoveries, capital intensity and the royalty burden are resolved.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in OR on this report alone. Verify the incremental royalty rate, buyback formula and OR’s attributable project economics before revising valuation; those terms are the key missing data.
- Treat Hot Chili’s discovery as a catalyst watch, not a resource-backed valuation upgrade: monitor assays from the southern diamond hole, the maiden La Verde resource and revised PFS inclusion. Strong assays that establish continuous sulphide mineralisation would support a positive reassessment; weak assays or a resource that fails to demonstrate mineable continuity would falsify it.
- Track the strategic partnering process and Q2 2027 EIA submission path. A binding partner on acceptable terms would reduce funding and execution risk; prolonged non-binding discussions, permitting slippage or evidence that water/infrastructure requirements materially expand would undermine the thesis.
- Avoid extrapolating drilling success into near-term copper supply or a sector-wide trade: any competitive impact on copper producers and developers is remote until resource, metallurgy, permitting and financing milestones are cleared.
More News
- Trump called out Big Oil profits. Here’s how much their refining earnings have surged since
- Nasdaq Nears Correction as Amazon, Alphabet, Intel Disappoint Wall Street
- Tankers defy sharp escalation of Iranian attacks to keep crude oil flowing through Strait of Hormuz
- Reddit stock plunges 30% after weak outlook, heads for worst day ever
- Binance’s $6.3 Billion Cyber Heist Shows Crypto Vulnerabilities
- Big Oil Scores $56 Billion Windfall on Spiking Fuel Prices