
Lam Research Breaks Ground on New Oregon Lab to Accelerate AI Era Semiconductor Research & Development Locally, Globally
Source: PR Newswire
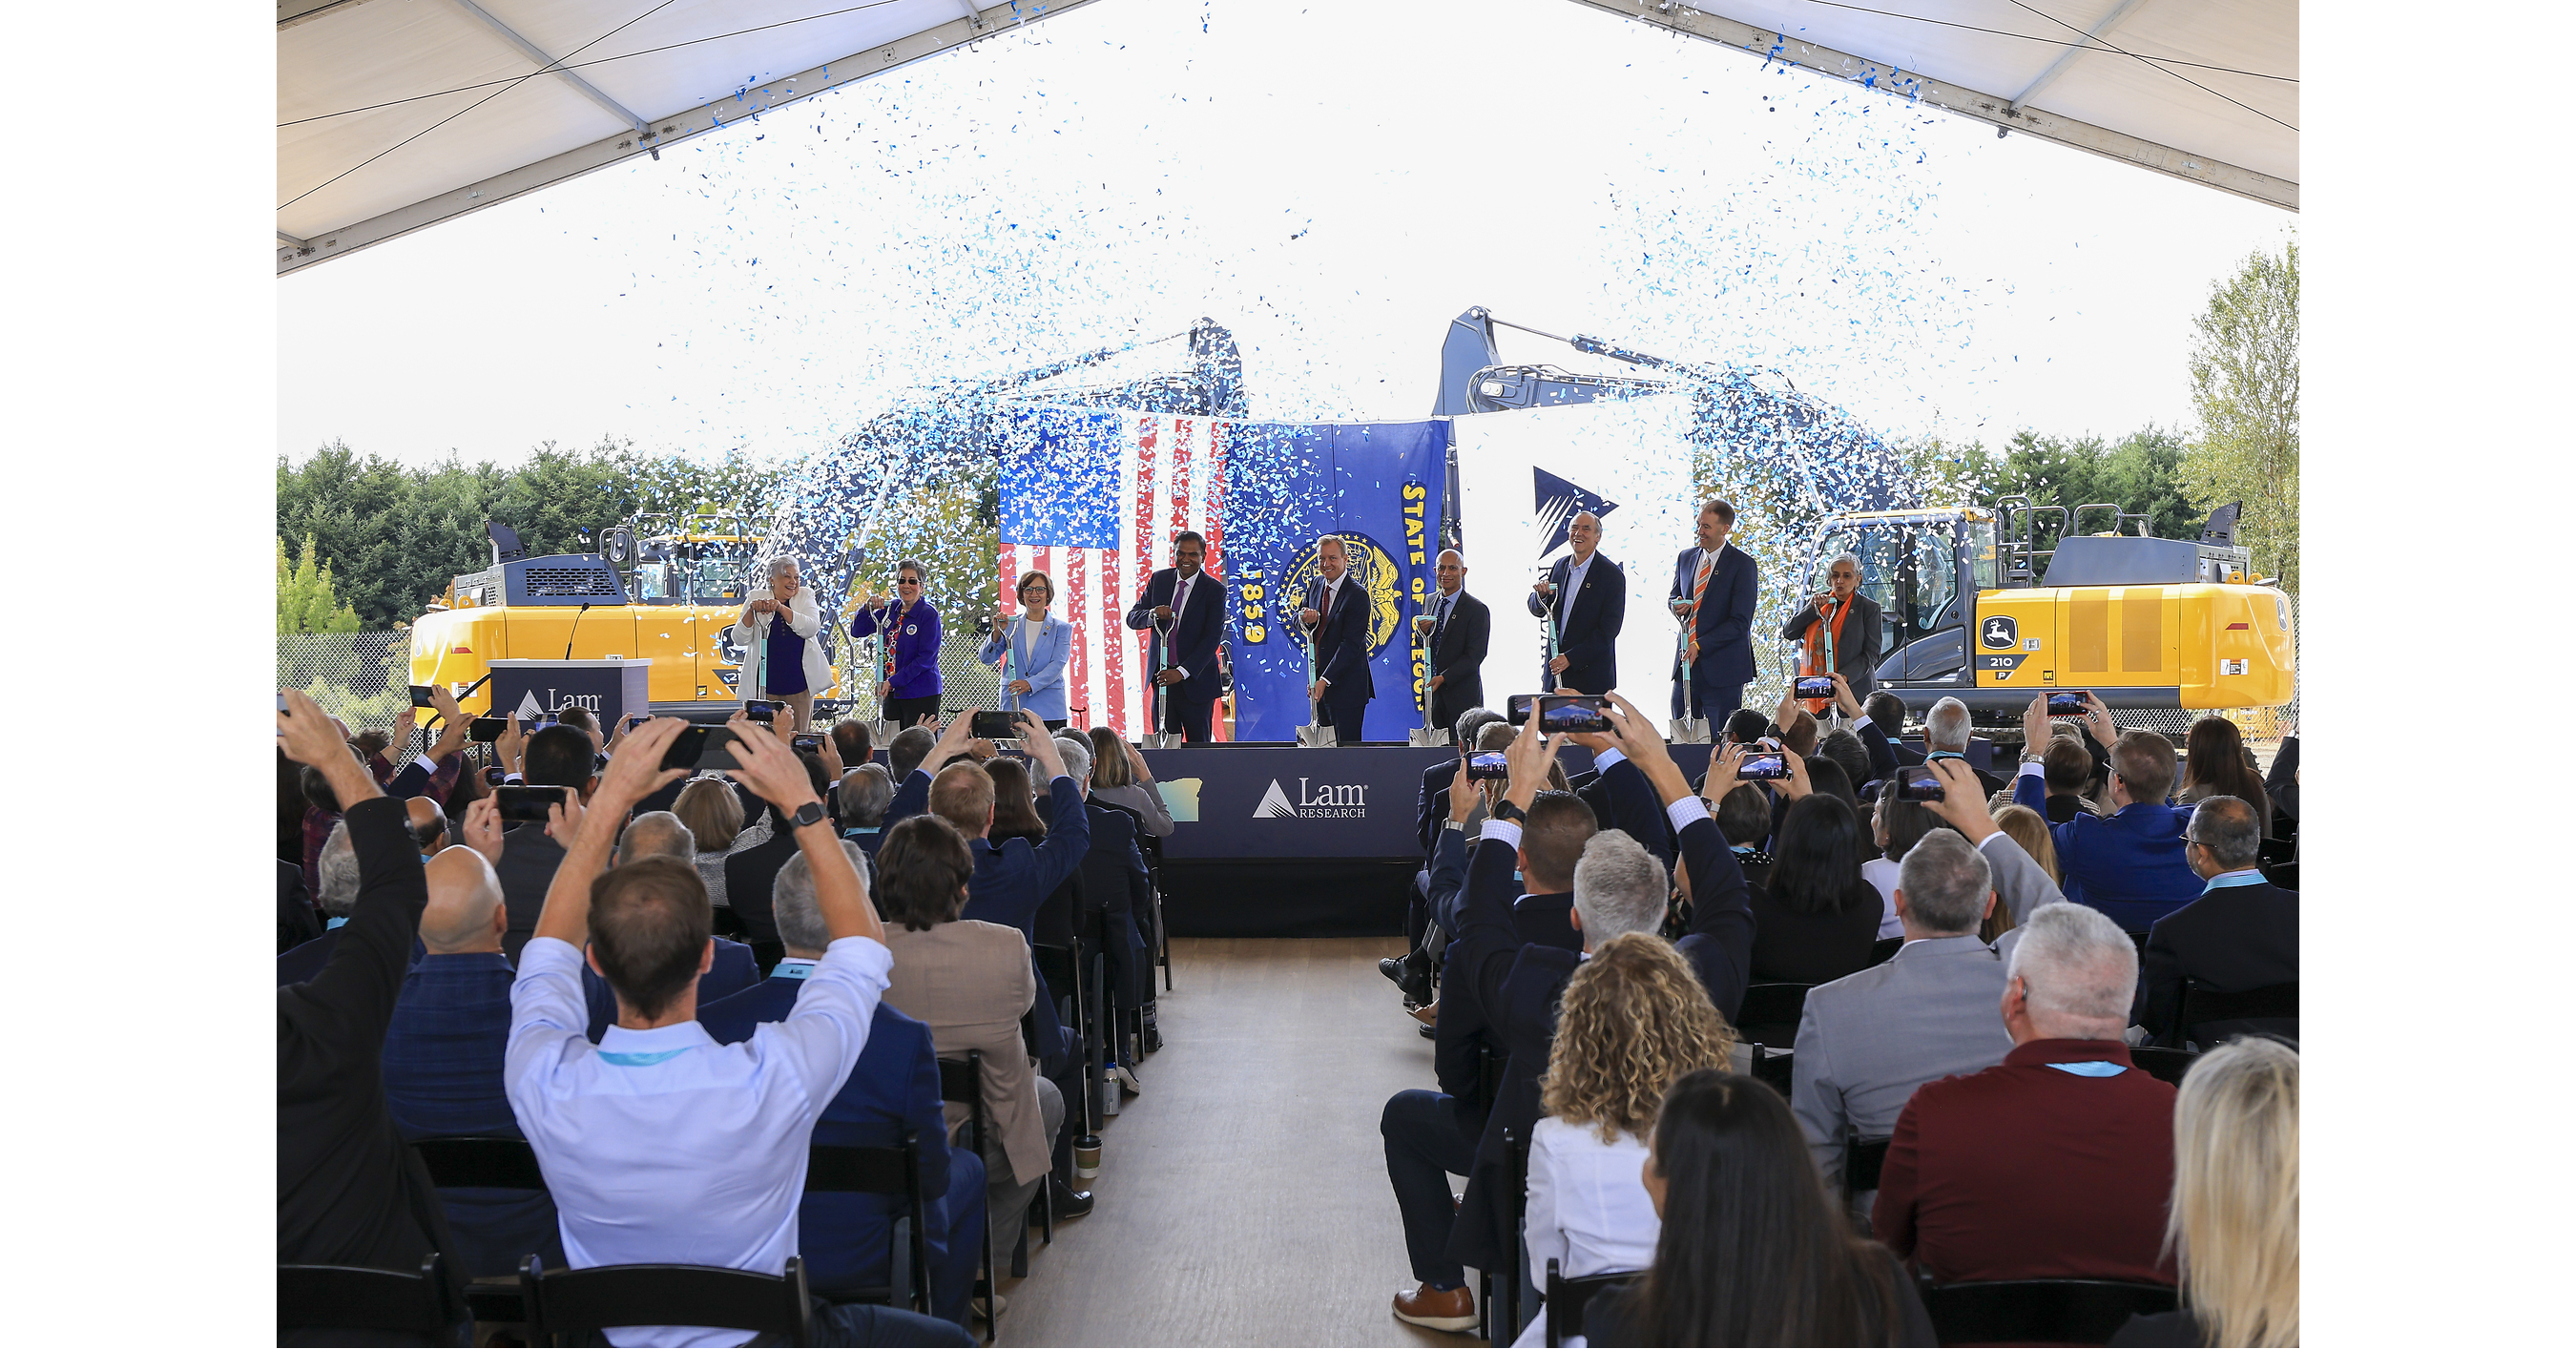
Lam Research (LRCX) broke ground on a 120,000-square-foot Oregon R&D lab that will expand cleanroom lab space by more than 50%, opening in 2028, to accelerate AI-chip process development. The project is part of a planned $3B+ global lab-network investment over five years, with a third-party estimate of ~900 jobs and ~$500M economic output during the 3-year construction period and broader statewide job support to 11,000+ (with Lam’s Oregon economic contribution projected to exceed $1.8B once complete). The expansion is positioned to deepen customer side-by-side innovation and compress product development cycles.
Analysis
This reads less like an earnings catalyst and more like a signaling device: Lam is advertising that it expects advanced-node customer engagement to stay tight enough to justify pre-committing capital. The strategic value is not the building itself; it is the deeper embedding of Lam into customer process development, which raises switching costs and improves win rates on future deposition/etch tools when customers move from pilot to volume.
The near-term market impact should be modest because the spend is long-dated and mostly non-recurring, while the incremental revenue uplift is indirect. The more important second-order effect is competitive: if Lam can compress qualification cycles, it can pull forward design wins versus peers in semicap, but it also quietly increases dependence on a concentrated set of customers whose capex timing still controls the outcome. If AI-related wafer fab spending slips, the lab becomes a cost center rather than a growth lever.
The contrarian read is that the market may overvalue the PR and undervalue the execution risk. A five-year lab build does not change the near-term order book, and the real falsifier is not ribbon-cutting optics but whether Lam can translate this into higher share of wallet, higher gross margin, and stronger forward bookings over the next 2-4 quarters. For Intel and Micron, the read-through is mostly narrative support for their own process roadmaps, not material financial help unless it coincides with a genuine capex upcycle.
Over 6-18 months, the best expression is to own Lam as a high-quality enabler of AI fab complexity, but only on pullbacks and only if bookings remain above replacement run-rate. If customer capex normalizes or export controls pressure China exposure, the multiple can compress quickly because the stock already trades on future node adoption, not current lab headlines.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Buy LRCX on any 2-3% post-news fade; 3-6 month thesis is improved customer lock-in and higher share-of-wallet at leading-edge fabs. Risk/reward is favorable if forward bookings and gross margin inflect; falsify if management cuts capex-guidance commentary or bookings decelerate next quarter.
- Use LRCX as the cleaner AI semi-capex exposure versus INTC: long LRCX / short INTC as a pair trade for 1-3 months. LRCX monetizes the ecosystem directly; INTC gets mostly optics and still carries execution risk on foundry ramp. Exit if Intel’s foundry guidance or customer adoption data materially improves.
- Watch MU as a secondary beneficiary rather than a primary trade. The lab investment supports the memory-tech cadence tied to AI density, so a long MU works only if you also see capex confirmation from Micron over the next 1-2 quarters; otherwise the news is too indirect for an outright entry.
- Do not chase the announcement with an options call-buy unless you can anchor to the next earnings date. Implied vol is likely to be expensive relative to the slow-burn nature of the catalyst; a better structure is a call spread in LRCX into the next booking update, with a thesis failure if the stock cannot hold recent support after the first analyst checks.
- If you want a contrarian hedge, short a basket of semicap names that rely on broad WFE beta rather than customer-specific integration. The risk is that this becomes a 'quality wins share' tape, so keep the position small and cover if sector-wide capex commentary improves.
More News
- Trading expert sets date when Micron (MU) stock will crash to $400
- Earnings season kicks into high gear as big banks report next week. Here's what's ahead
- Memory stocks have hit a malaise. Jay Woods believes it's a buying opportunity
- Nvidia and Micron shares bounce as investors get clarity on a key OpenAI matter
- Sequoia-backed Nuvacore seeks $2.5bn valuation in funding round
- Cramer’s week ahead: Earnings kick off as banks and chipmakers face big tests