
Applied Materials: Buy The Engineering Powerhouse Behind AI
Source: seekingalpha.com
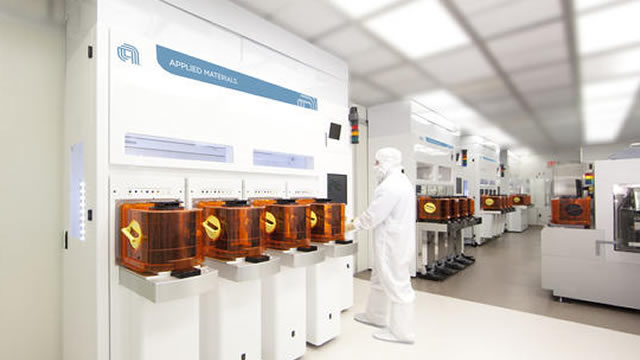
Applied Materials was initiated at Buy with a $583.80 price target, implying 55% upside, based on technology leadership and expected margin expansion. Q3 revenue grew 25% and EPS rose 41%; Q4 guidance implies year-over-year growth of 51% in revenue and 85% in EPS. AI-driven demand across advanced logic, DRAM and packaging, alongside recurring services and installed-base revenue, supports the positive outlook.
Analysis
The upside case is less about AI exposure in isolation than whether rising process complexity translates into sustained wafer-fab equipment budgets and share gains. Advanced logic, DRAM and packaging demand can support multiple product areas, but customer capex is lumpy: delays or utilization weakness can defer tool orders even if long-term AI demand remains intact. Services and installed-base revenue may cushion a downturn, but should not be treated as a hedge against a broad equipment-cycle reset.
The key distinction to test is market growth versus outperformance. Strong company growth and guidance do not, by themselves, establish that Applied Materials is taking share; peers can benefit from the same spending cycle. Near term, the bullish analyst call and elevated growth expectations create risk of a “good results, muted stock response” if orders or guidance merely meet expectations. Over 1–3 months, order trends, customer capex commentary and the next guidance update matter more than the price target. Over 6–18 months, export controls and any slowdown in AI-related infrastructure spending could impair the cycle; tighter process requirements and packaging complexity are structural supports, not guarantees of uninterrupted spending.
Treat the stated target as an analyst scenario, not independently validated fair value: current price, valuation, consensus estimates, order data and segment exposure are not supplied. The thesis weakens if order momentum or forward guidance rolls over, margins fail to convert revenue growth into operating leverage, or customer capex plans are cut.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing solely on the initiation or its stated upside. Verify current valuation, consensus expectations and order trends before underwriting further multiple expansion.
- Consider a staged long AMAT only after confirming that orders and forward guidance support the expected acceleration; size against the risk of a semiconductor-equipment cycle reversal rather than treating services as a full downside hedge.
- For relative-value exposure, compare AMAT with Lam Research, KLA and ASML after checking each company’s customer and product exposure; the article does not establish that AMAT will outperform peers.
- Track leading indicators over the next 1–3 months: customer capex commentary, equipment orders, DRAM and advanced-packaging investment, margin conversion, and any export-control changes. Reassess if these deteriorate even while headline AI spending remains strong.
More News
- Here's the AI Chip Stock That Hedge Funds Are Loading Up On
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests
- Next week brings major risks for the stock market, just as the AI trade keeps faltering
- AI Doubts Spread Cracks in Equities, Credit Markets: Evening Briefing Americas
- Looters hit 3,000 French businesses. Within hours, the haul was trending on Vinted under the riot’s date
- Kinder Morgan, Energy Transfer and Williams could benefit from cheap natural gas
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Search Earnings Call Transcripts With AI
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI