
Pre-Owned Jet and Turboprop Aircraft Inventory Levels Show Monthly Increases in September
Source: PR Newswire
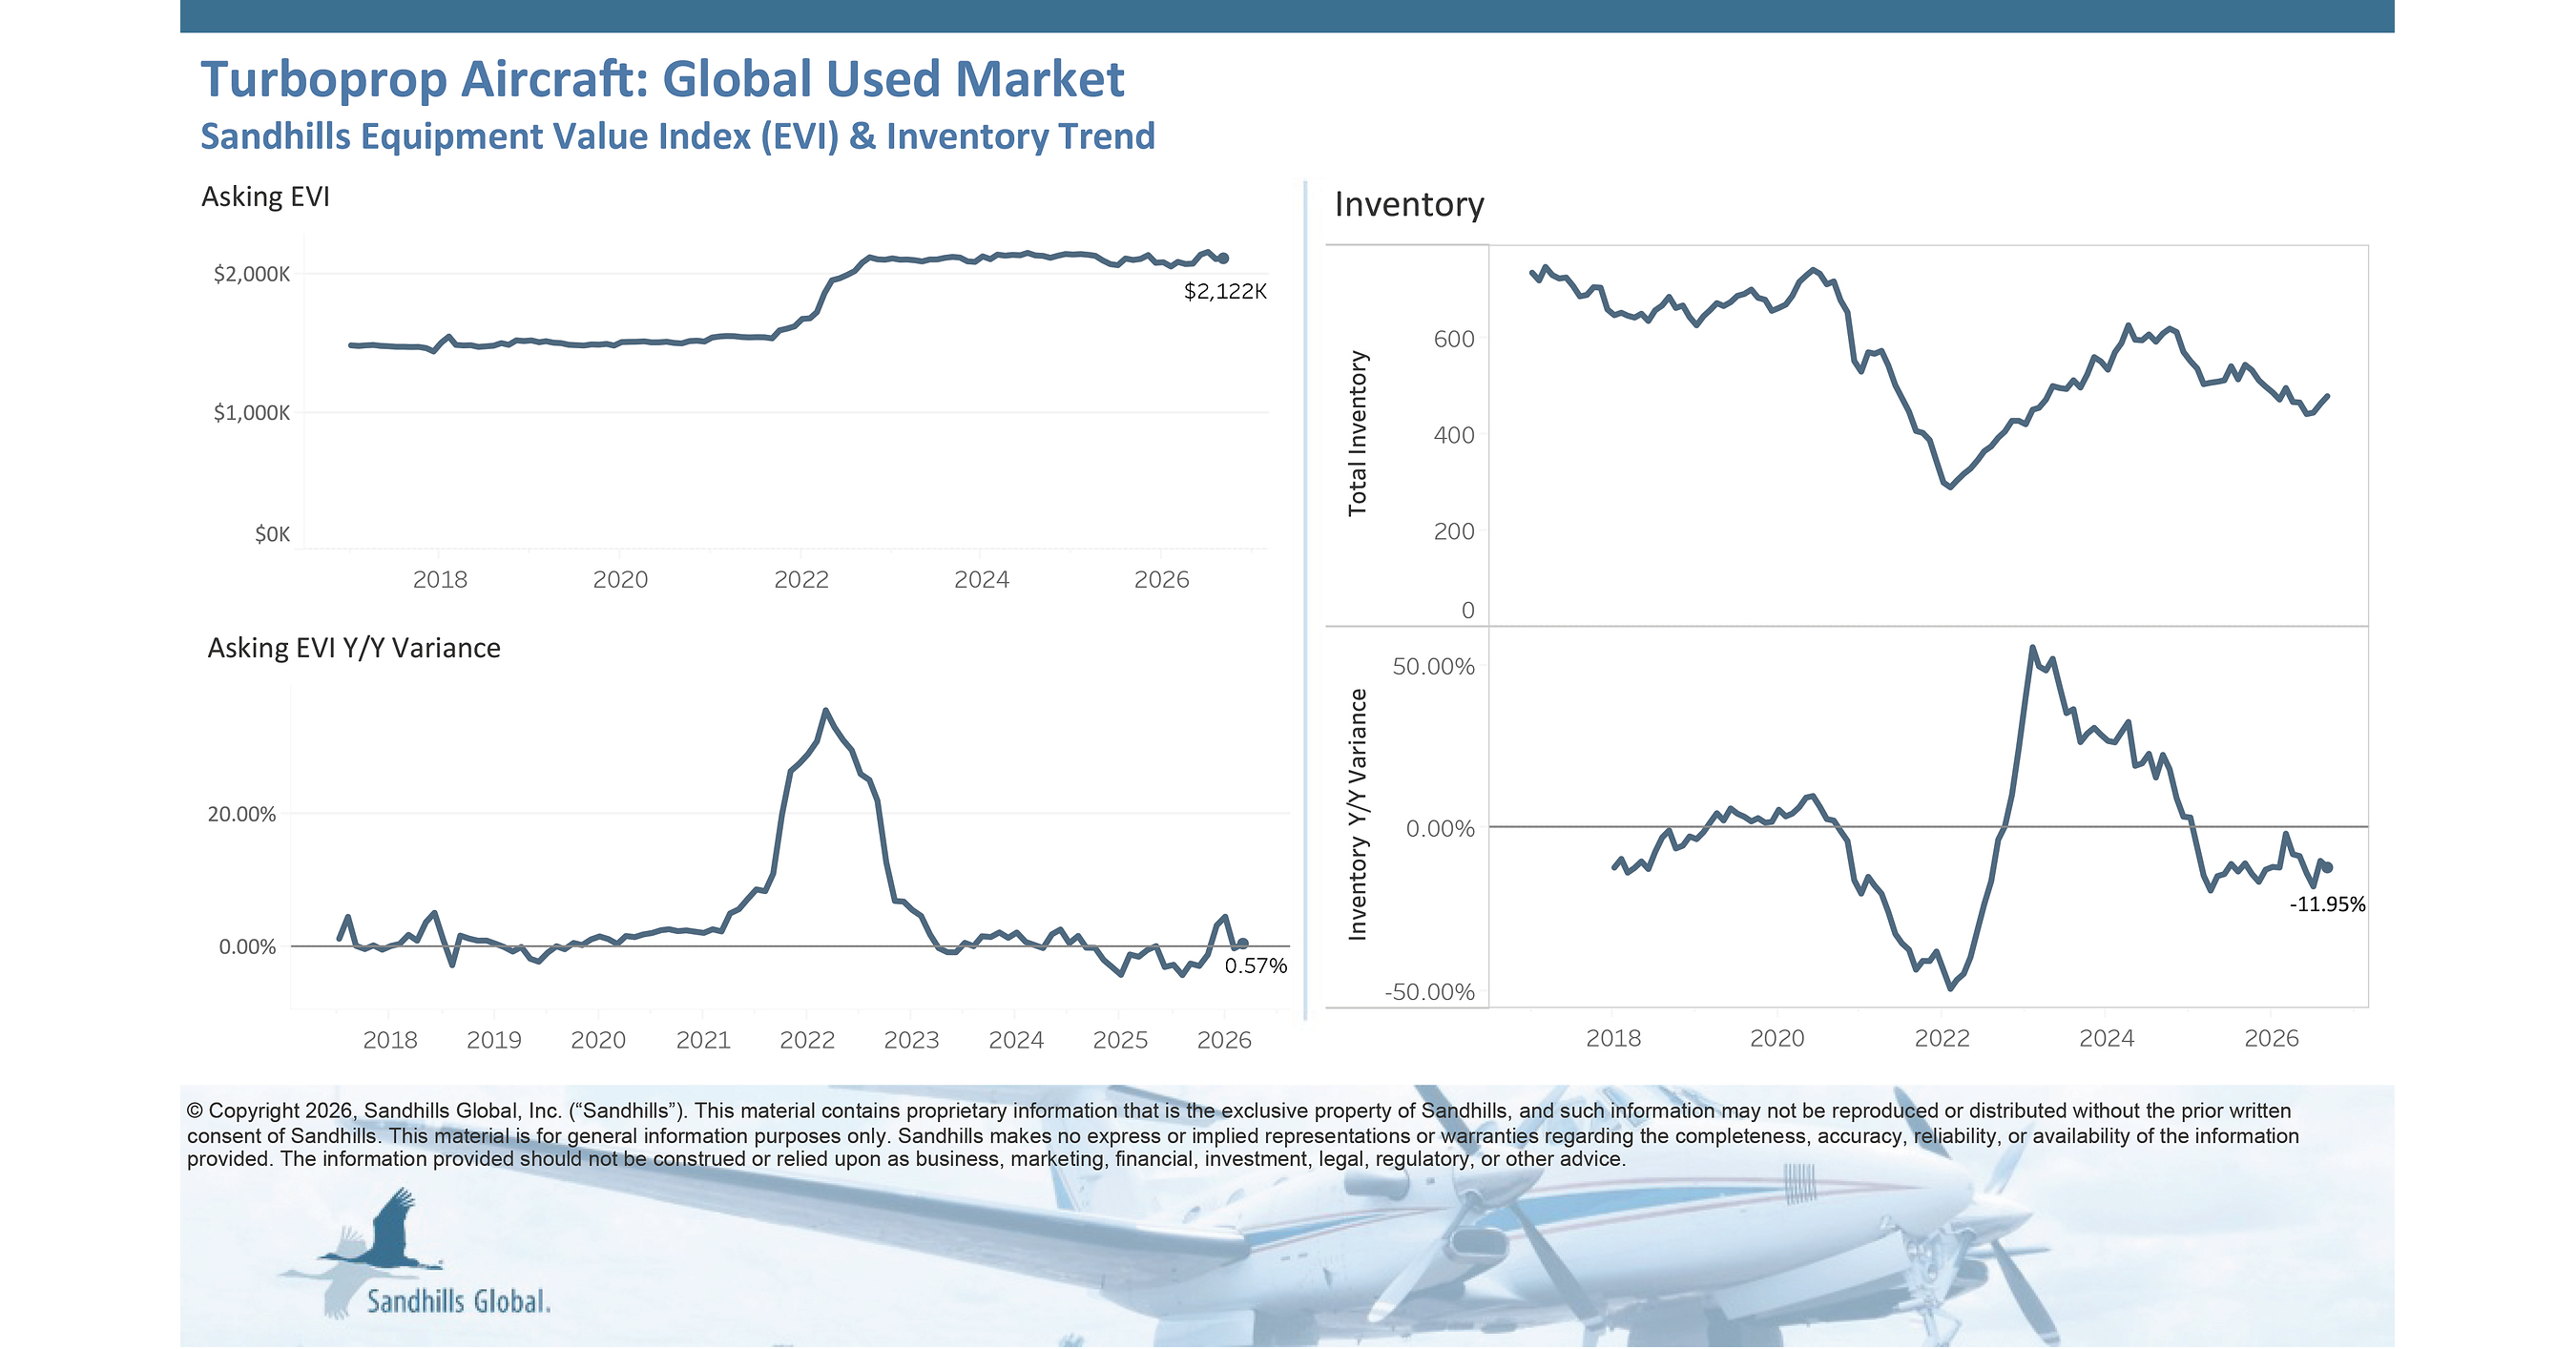
Sandhills reported mixed September trends across used-aircraft markets: global used-jet inventory rose 5.07% month over month but fell 23.58% year over year, while jet asking prices increased 2.02% M/M. Turboprop inventory rose 3.46% M/M and was down 11.95% Y/Y; U.S. and Canada piston-single inventory was flat M/M and down 12.24% Y/Y, with asking values down 0.74% M/M. The report characterized several segments as stabilizing or trending sideways, rather than accelerating.
Analysis
The more useful signal is divergence by aircraft class, not a broad aviation-cycle turn. Jet inventory remains tight year over year while asking values edge higher, which can support residual-value confidence and make new aircraft from Gulfstream, Bombardier, and Dassault more attractive to buyers unwilling to wait for scarce used models. That is a gradual order-book/residual-value channel, not evidence of an immediate delivery or earnings uplift. The 5% monthly jet inventory rise—especially in super mids—could instead mark the start of easing scarcity if it persists; asking prices are seller quotes, not cleared transaction prices.
Piston singles show the opposite tension: fewer listings but weaker asking values. That combination is consistent with softer buyer demand or a changing mix, and cautions against reading low inventory alone as pricing power. Turboprops look broadly range-bound; Robinson piston helicopters have the clearest year-over-year price weakness, though the monthly rebound argues against extrapolating a straight-line decline.
Near term, these are thin, segmented markets and one month of data is noisy; there is no clean listed-equity trade on this report alone. Over 1–3 months, watch realized transaction prices, days on market, inventory persistence, and OEM order/backlog commentary. Over 6–18 months, sustained used-jet scarcity could reinforce residual values, while a reversal in inventory or discounting could pressure that support. The thesis weakens if jet listings keep rising and completed-sale prices roll over, or if piston values stabilize alongside faster sales. Sandhills’ index is useful directional evidence, not independently verified transaction data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.00
Key Decisions for Investors
- No report-driven position in aircraft OEMs: the evidence is asking-price and inventory data, with no confirmation yet in completed transactions, order conversion, or guidance.
- Set an alert on used-jet inventory and realized-sale pricing over the next 1–3 months. Persistent inventory growth alongside price concessions would challenge the residual-value-positive view for Gulfstream, Bombardier, and Dassault.
- Treat piston-single weakness as a watch item rather than a short thesis; verify transaction prices, time-to-sale, and financing availability before inferring a demand downturn from lower asks.
- Avoid extrapolating the Robinson helicopter monthly price rebound. Reassess if year-over-year declines narrow and sales velocity improves; continued declines would indicate the segment’s softness is more persistent.
More News
- Why Dangote’s Nigeria Refinery IPO Is Such a Big Deal for Africa
- Oman evacuates injured crew from attacked tanker in Strait of Hormuz
- Oil rises as concerns over Houthi attacks on Saudi Arabia eclipse supply recovery
- Rebounding oil exports through Strait of Hormuz are vulnerable to stepped-up Iranian tanker attacks
- A 32% beat, a +6% jump: the IT solutions name our models picked in July
- Nvidia Is on the Verge of a $6 Trillion Market Value
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The $4.7 Trillion Bet: When Does AI Capex Become AI Revenue?
- Equity Research Automation Statistics: A 2026 Evidence Check