
This Is a World Many Bond Investors Have Never Seen Before
Source: Bloomberg
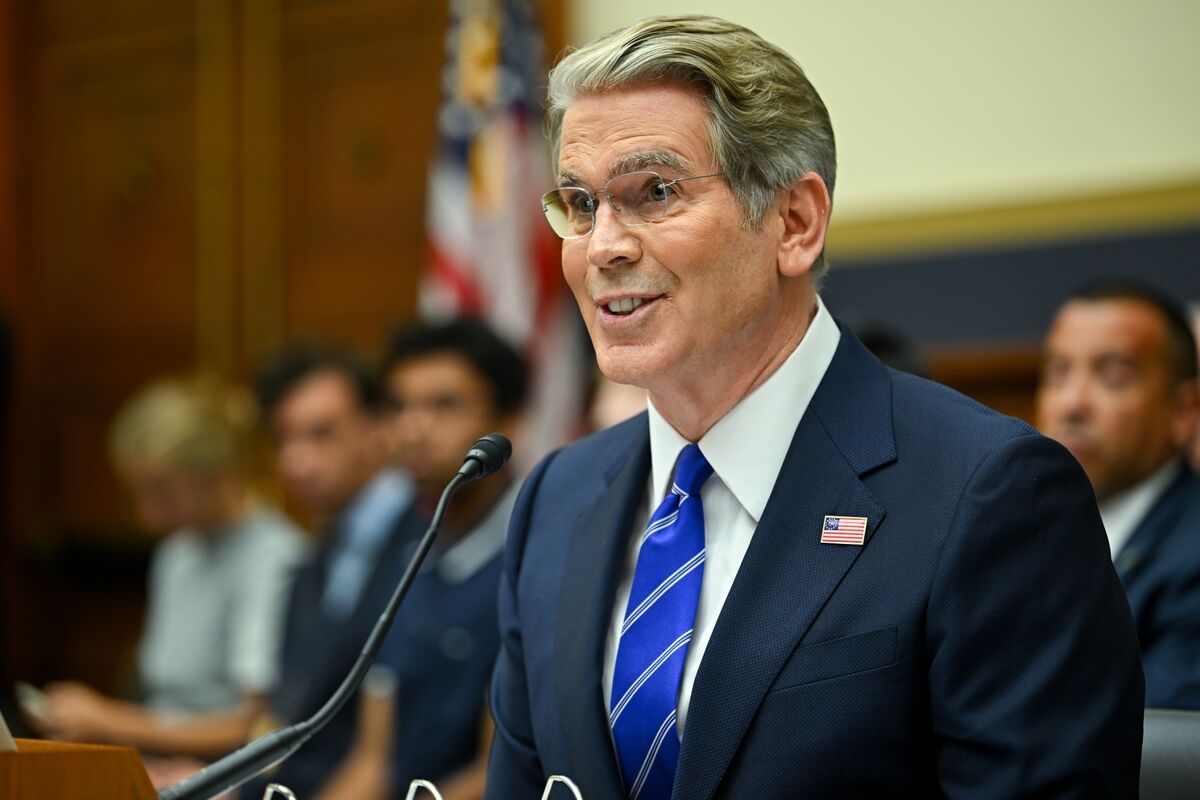
Bond yields near 5% are increasingly being viewed as a new structural norm or floor, marking a regime shift for investors accustomed to persistently low rates. Treasury Secretary Scott Bessent attributes the recent Treasury selloff to higher oil prices tied to the Iran war and expects yields to decline once the conflict ends. The sustained higher-yield environment presents a material headwind for bond valuations and interest-rate-sensitive assets.
Analysis
The key investable question is whether the rate move is a cyclical inflation shock or a durable term-premium reset. A durable reset would pressure long-duration equities far more than headline index exposure implies: software, unprofitable growth and rate-sensitive real estate carry both valuation-duration and refinancing risk, while banks face unrealized securities losses and deposit-cost pressure. Conversely, insurers such as ALL and CB, and asset managers with floating-rate cash balances, can benefit from reinvesting at higher yields, although credit losses would offset that benefit if policy becomes restrictive.
The official oil-war explanation is incomplete unless inflation breakevens rise in tandem with nominal yields. If real yields and the 10y-2y curve continue to rise after energy prices stabilize, the market is pricing fiscal supply, weaker foreign Treasury demand and a higher required term premium; those forces are not resolved by a geopolitical de-escalation. The most vulnerable second-order channel is commercial real estate and private credit: 2026-27 refinancing at materially higher coupons can force asset sales, widen BDC funding spreads and create losses that public markets have not fully discounted.
Over the next days, a sharp energy reversal could produce a crowded Treasury-covering rally and temporarily support long-duration equities. Over 1-3 months, auctions, inflation expectations and Treasury term-premium measures matter more than spot crude; sustained weak auction tails and rising dealer concessions would validate the structural bear case. Over 6-18 months, a higher nominal-rate regime favors companies with net cash, pricing power and near-term free-cash-flow yield over businesses valued on terminal earnings.
The contrarian view is that broad equity bearishness may be misplaced if nominal yields rise because real growth remains resilient rather than because inflation is reaccelerating. In that outcome, high-quality cyclicals and select financials can outperform even as long-bond proxies de-rate. The thesis is falsified by a sustained decline in real yields, tightening credit spreads and a meaningful reduction in Treasury supply expectations; that combination would favor duration again.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.35
Key Decisions for Investors
- Maintain a 1-3 month duration hedge via long TBT or short TLT, sized modestly because geopolitical de-escalation can trigger a violent rally in long Treasuries. Exit or reduce if 10-year real yields decline materially for two consecutive weeks and auction demand improves.
- Pair trade: long ALL and CB / short VNQ over 3-6 months. Insurers reinvest portfolios at higher yields while REIT cash flows and asset values remain exposed to refinancing; invalidate if long-end yields fall below the post-shock range and CRE transaction volumes recover.
- Underweight long-duration growth through a relative short in ARKK or IGV versus long QUAL for the next 1-3 months. The payoff is multiple compression if term premium persists; risk is a rapid disinflation-led rally, so use a defined stop on a sustained narrowing of real yields.
- Watch listed private-credit and BDC exposure, particularly ARCC and OBDC, rather than shorting immediately. Initiate a relative underweight only if non-accruals rise, portfolio marks weaken or unsecured funding spreads widen; higher base rates alone initially lift interest income and are not sufficient evidence of impairment.
- For equity longs, favor cash-generative value and financial quality over broad beta: XLF versus IWM is the cleaner expression if the curve steepens without a credit event. Reverse if high-yield spreads widen sharply, as credit stress would overwhelm banks' net-interest-income benefit.
More News
- US, Iran Explore Phased Deal to Reopen Strait of Hormuz
- Warsh's regime change at the Fed pushes ahead – and meets resistance
- Bond Selloff Fades, US-Iran Said to be Exploring Phased Deal, Trump-Xi Summit
- Why High Yields on US Treasury Bonds, Government Debt Look Like the New Normal
- Saudi Arabia allies line up support as Houthi attacks mount
- Iran pitches seven-day roadmap to end conflict with US
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Bitcoin's 52% Crash Proves It's a Tech Stock: Here's What That Means for Portfolio Construction
- What Is an AI Investment Research Platform?