
Haier Biomedical destaca sus soluciones automatizadas de bioalmacenamiento y farmacéuticas conectadas
Source: PR Newswire
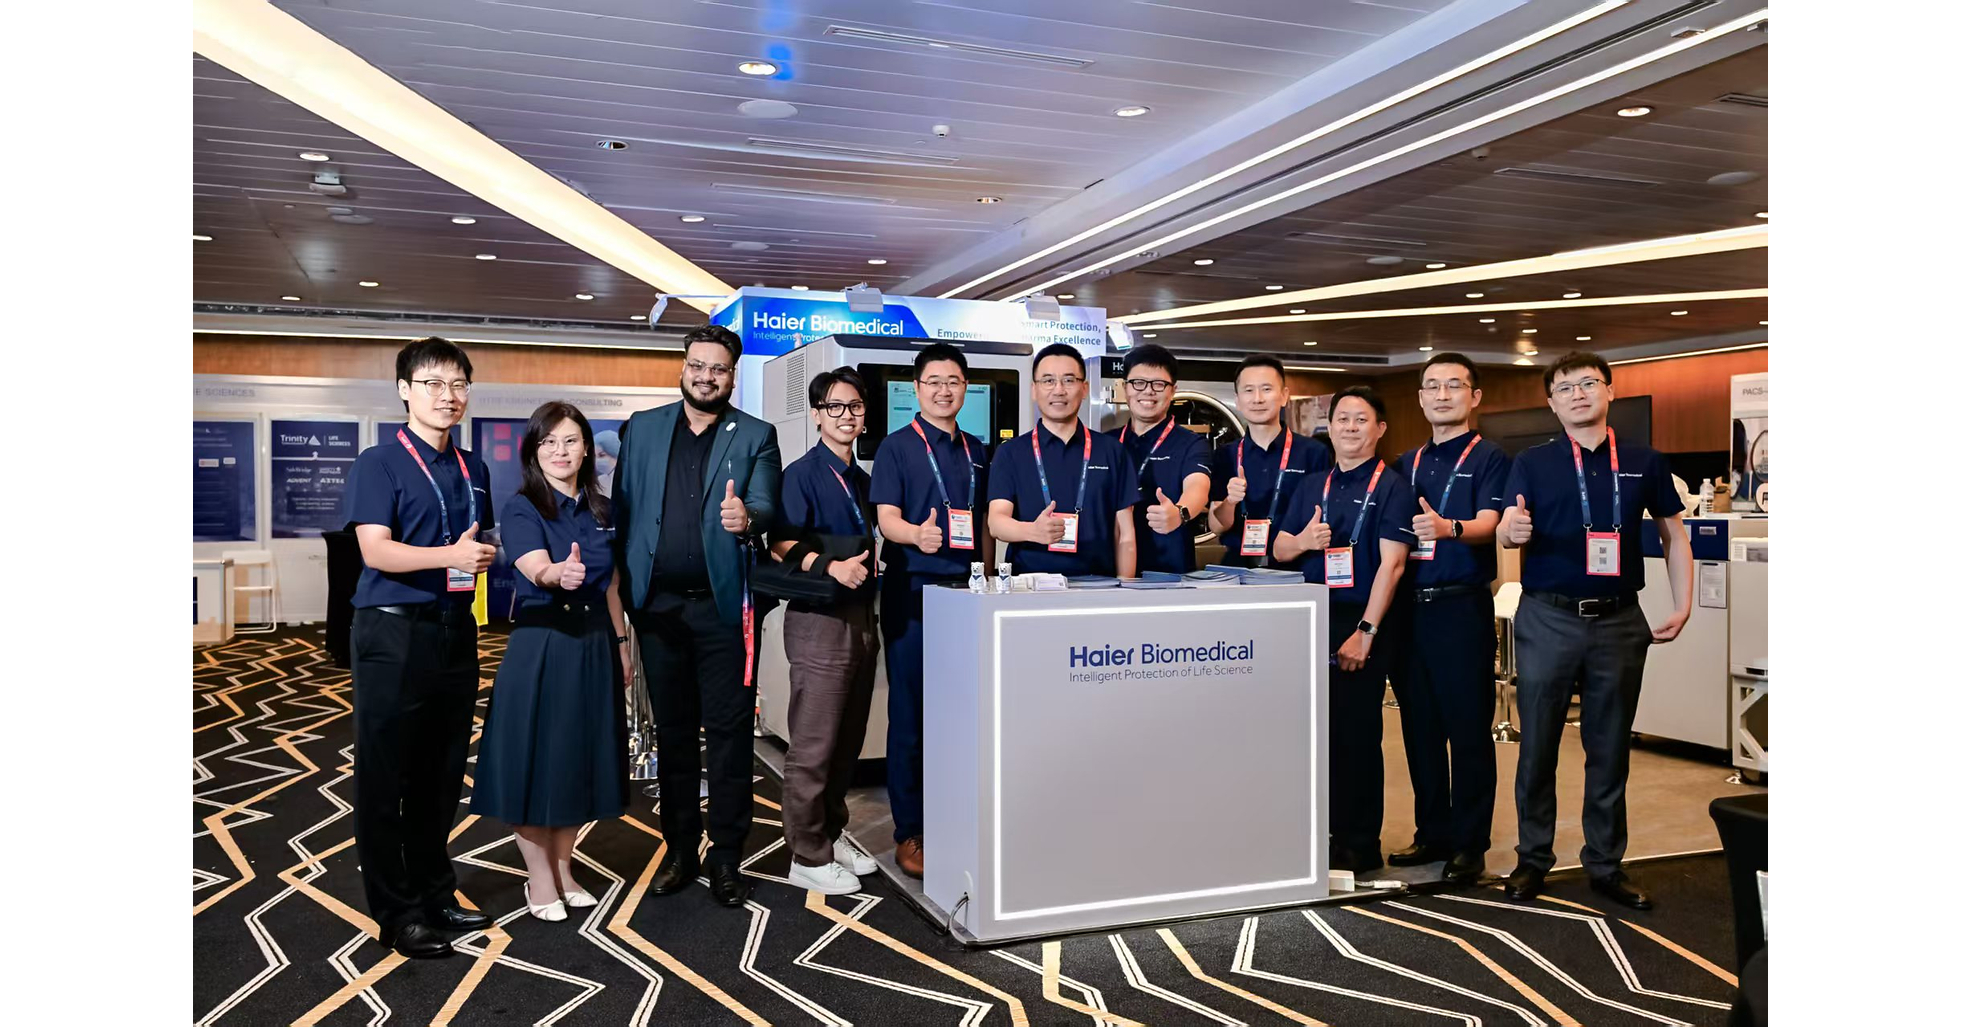
Haier Biomedical presentó en ISPE Singapore 2026 una nueva plataforma de bioinfraestructura inteligente, destacando el almacenamiento automatizado a -80°C, un liofilizador piloto y un sistema RFID ULT para trazabilidad de muestras sin escaneo visual. En 1S 2026, los ingresos ligados a clientes farmacéuticos subieron 23% interanual y los ingresos de soluciones de laboratorio crecieron 19%, mientras que los negocios relacionados con IA aportaron 18% del total ( +3 pp vs 2025). La noticia es positiva pero principalmente comercial/tecnológica, con impacto limitado en el corto plazo.
Analysis
This reads less like a near-term earnings catalyst and more like evidence that Haier Biomedical is trying to move up the value stack from commodity cold-chain hardware toward workflow control points. If that transition sticks, the economic prize is not the freezer margin itself but higher switching costs, installed-base software/service attach, and a longer replacement cycle that can stabilize revenue through pharma capex downturns. The competitive threat is aimed more at fragmented regional ULT vendors and mid-tier lab automation players than at premium incumbents like TMO, DHR, or Sartorius, which still win on validation depth, global compliance track record, and enterprise procurement relationships.
The second-order issue is that pharma customers buy infrastructure on validation time, not conference demos. Even if the product roadmap is real, conversion from pilot visibility to qualified purchase orders can take multiple quarters, and revenue recognition for integrated systems is lumpy. That means the stock can drift on narrative momentum for 1-3 months, but the thesis only becomes durable if management shows an inflection in backlog quality, gross margin, and service/software mix over the next 2-4 quarters. If those don’t improve, the market will likely re-rate this as marketing-led execution rather than a structural platform shift.
The contrarian miss is that automation adoption may actually compress differentiation for hardware vendors: once RFID, monitoring, and inventory reconciliation become table stakes, pricing power can migrate to the software layer or to the top-tier integrators. In that case Haier could win unit share while still disappointing on margin expansion. The key falsifier is whether pharma-related growth decelerates below mid-teens or whether AI/connected solutions remain low-quality revenue with no margin lift; if so, the market should fade the platform story.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate market trade: treat this as a watch item until Haier Biomedical (688139.SH) reports evidence of order conversion, not just product launches. The signal to wait for is 1-2 quarters of backlog growth and gross margin stability; absent that, the setup is narrative-only.
- If access to A-shares is available, accumulate 688139.SH on a pullback only if management confirms higher-margin mix and recurring service revenue. Target a 6-12 month hold; stop if pharma-related growth falls below ~15% YoY or margins fail to expand despite growth.
- Relative-value bias: short a basket of higher-valuation lab automation/consumables names if the market starts pricing in a broad automation upcycle without proof of adoption quality; prefer names most exposed to capex cyclicality and least exposed to consumables/service annuity. Use this only as a tactical hedge, not a core short.
- Overweight the beneficiaries of workflow digitization rather than the hardware headline names: TMO, DHR, and SRT3.DE should retain share if enterprise customers prioritize validation, service coverage, and software integration. This is a defensive way to express the trend without taking single-name execution risk in smaller OEMs.
- Set an alert for order commentary over the next 1-2 quarters: if Haier begins displacing standalone ULT/freezer vendors in meaningful pharma accounts, that is the first real confirmation that the platform strategy is working; if not, fade any multiple expansion above the broader Chinese industrial average.
More News
- Christine Lagarde: IMFC Statement
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Tesla is taking $250,000 deposits for a Roadster with SpaceX thrusters. The FAA says it isn’t an aircraft