
Niron Magnetics Marks Steel Raising at Sartell Manufacturing Site
Source: PR Newswire
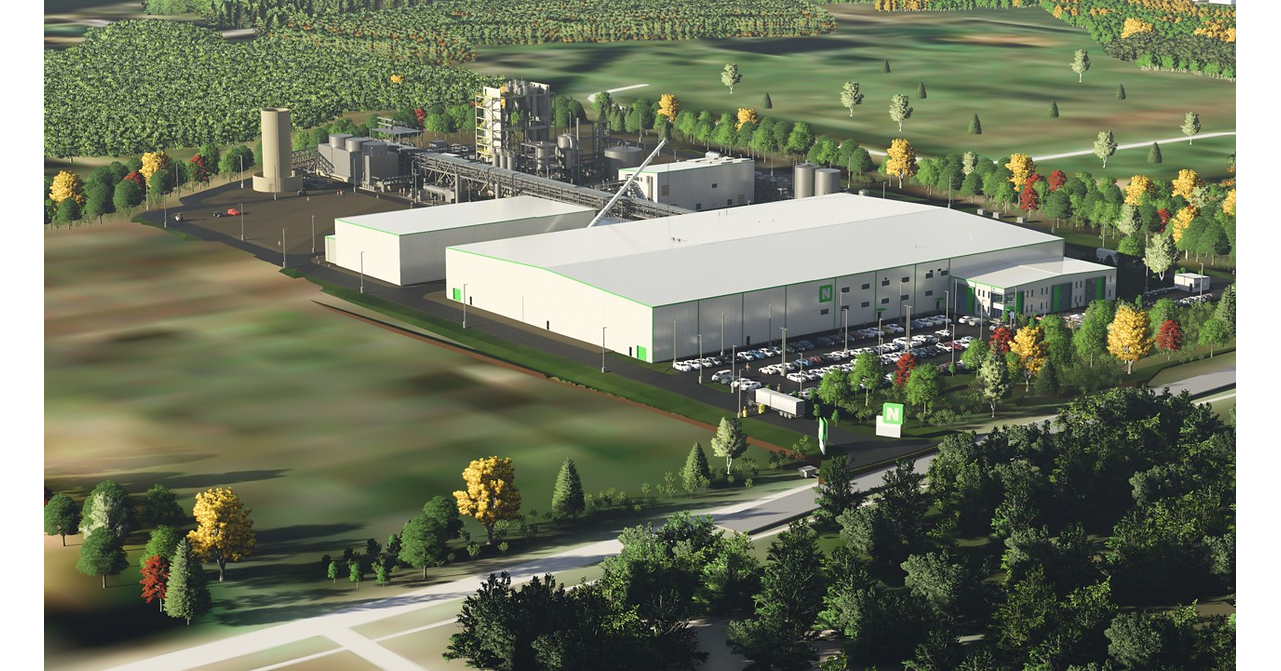
Niron Magnetics raised steel on its 287,000-square-foot Sartell, Minnesota facility, targeting 2027 operations with up to 1,500 tons of annual rare-earth-free permanent-magnet capacity and 175 full-time jobs. Honda, through Honda Xcelerator Ventures, made an undisclosed strategic investment to support commercialization and manufacturing scale-up. The project also has $300 million in previously announced loan commitments—$150 million each from the Department of War's Office of Strategic Capital and SMSC—supporting a domestic magnet supply chain independent of rare earth materials.
Analysis
Honda’s undisclosed minority investment is strategically more valuable as a potential qualification channel than as a financial event for HMC. If Niron’s material reaches automotive-grade performance, OEMs gain leverage over incumbent NdFeB magnet suppliers and over Chinese-linked rare-earth processing; however, automotive design-in, reliability testing, and supplier validation typically push any meaningful volume impact beyond the 2027 start-up into a 2028-30 window. HMC earnings sensitivity is therefore de minimis, while the signaling value matters most to Niron’s future fundraising and customer pipeline.
The near-term competitive threat to listed rare-earth names is likely overstated. A first commercial plant remains a scale-up and yield-risk exercise, and magnet performance must be measured not only by magnetic energy product but also coercivity, high-temperature stability, corrosion behavior, manufacturability, and delivered cost. MP Materials (MP) and Lynas (LYSDY) retain exposure to a much larger bottleneck—qualified separated rare-earth and sintered-magnet capacity—while Niron’s emergence could eventually cap the scarcity premium embedded in long-dated NdPr price assumptions.
The non-obvious beneficiary is the domestic motor and electrification supply chain: a qualified non-rare-earth magnet alternative could reduce procurement volatility and inventory buffers for U.S. industrial, data-center cooling, robotics, and automotive motor makers. Conversely, a failed ramp would reinforce the value of proven ex-China magnet capacity and make government-backed financing more likely to concentrate behind MP and established processors. Treat this as a 6-18 month technology-validation watch item, not an immediate public-equity earnings catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No directional HMC trade on this announcement. Reassess only if Honda discloses a supply agreement, motor-platform qualification, or a material committed-capital amount; absent that, the investment is immaterial to FY2027-28 earnings and ADR valuation.
- Use any Niron-driven selloff of more than 5-7% in MP as a tactical accumulation opportunity, provided NdPr pricing and MP’s commissioning/production guidance remain intact. The market may price a long-duration substitution risk before Niron proves yield, cost, and thermal-performance specifications; invalidate on a binding Niron OEM offtake tied to multi-thousand-ton annual volumes or an MP guidance cut.
- Maintain a 2027-30 watchlist pair: long MP versus short a basket of downstream magnet-cost-sensitive industrials only after independently verified Niron automotive qualification. The trade should not be initiated on press releases; required triggers are third-party performance data, disclosed unit economics, and customer offtake, because a successful alternative compresses rare-earth input exposure but could improve downstream margins.
- Monitor Department of War loan closing terms and construction progress over the next 3-6 months. A funding delay, cost overrun, or deferred commissioning would be a positive read-through for incumbent rare-earth/magnet supply-chain scarcity and a reason to remove any substitution-risk discount from MP and LYSDY.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Biotech stocks are surging. How investors can play the new drug innovation boom
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Hebbia Alternatives: A Workflow-Based Buyer’s Guide
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect