
Dahua Technology presenta la vita intelligente integrata e le innovazioni a IFA Berlin 2026
Source: PR Newswire
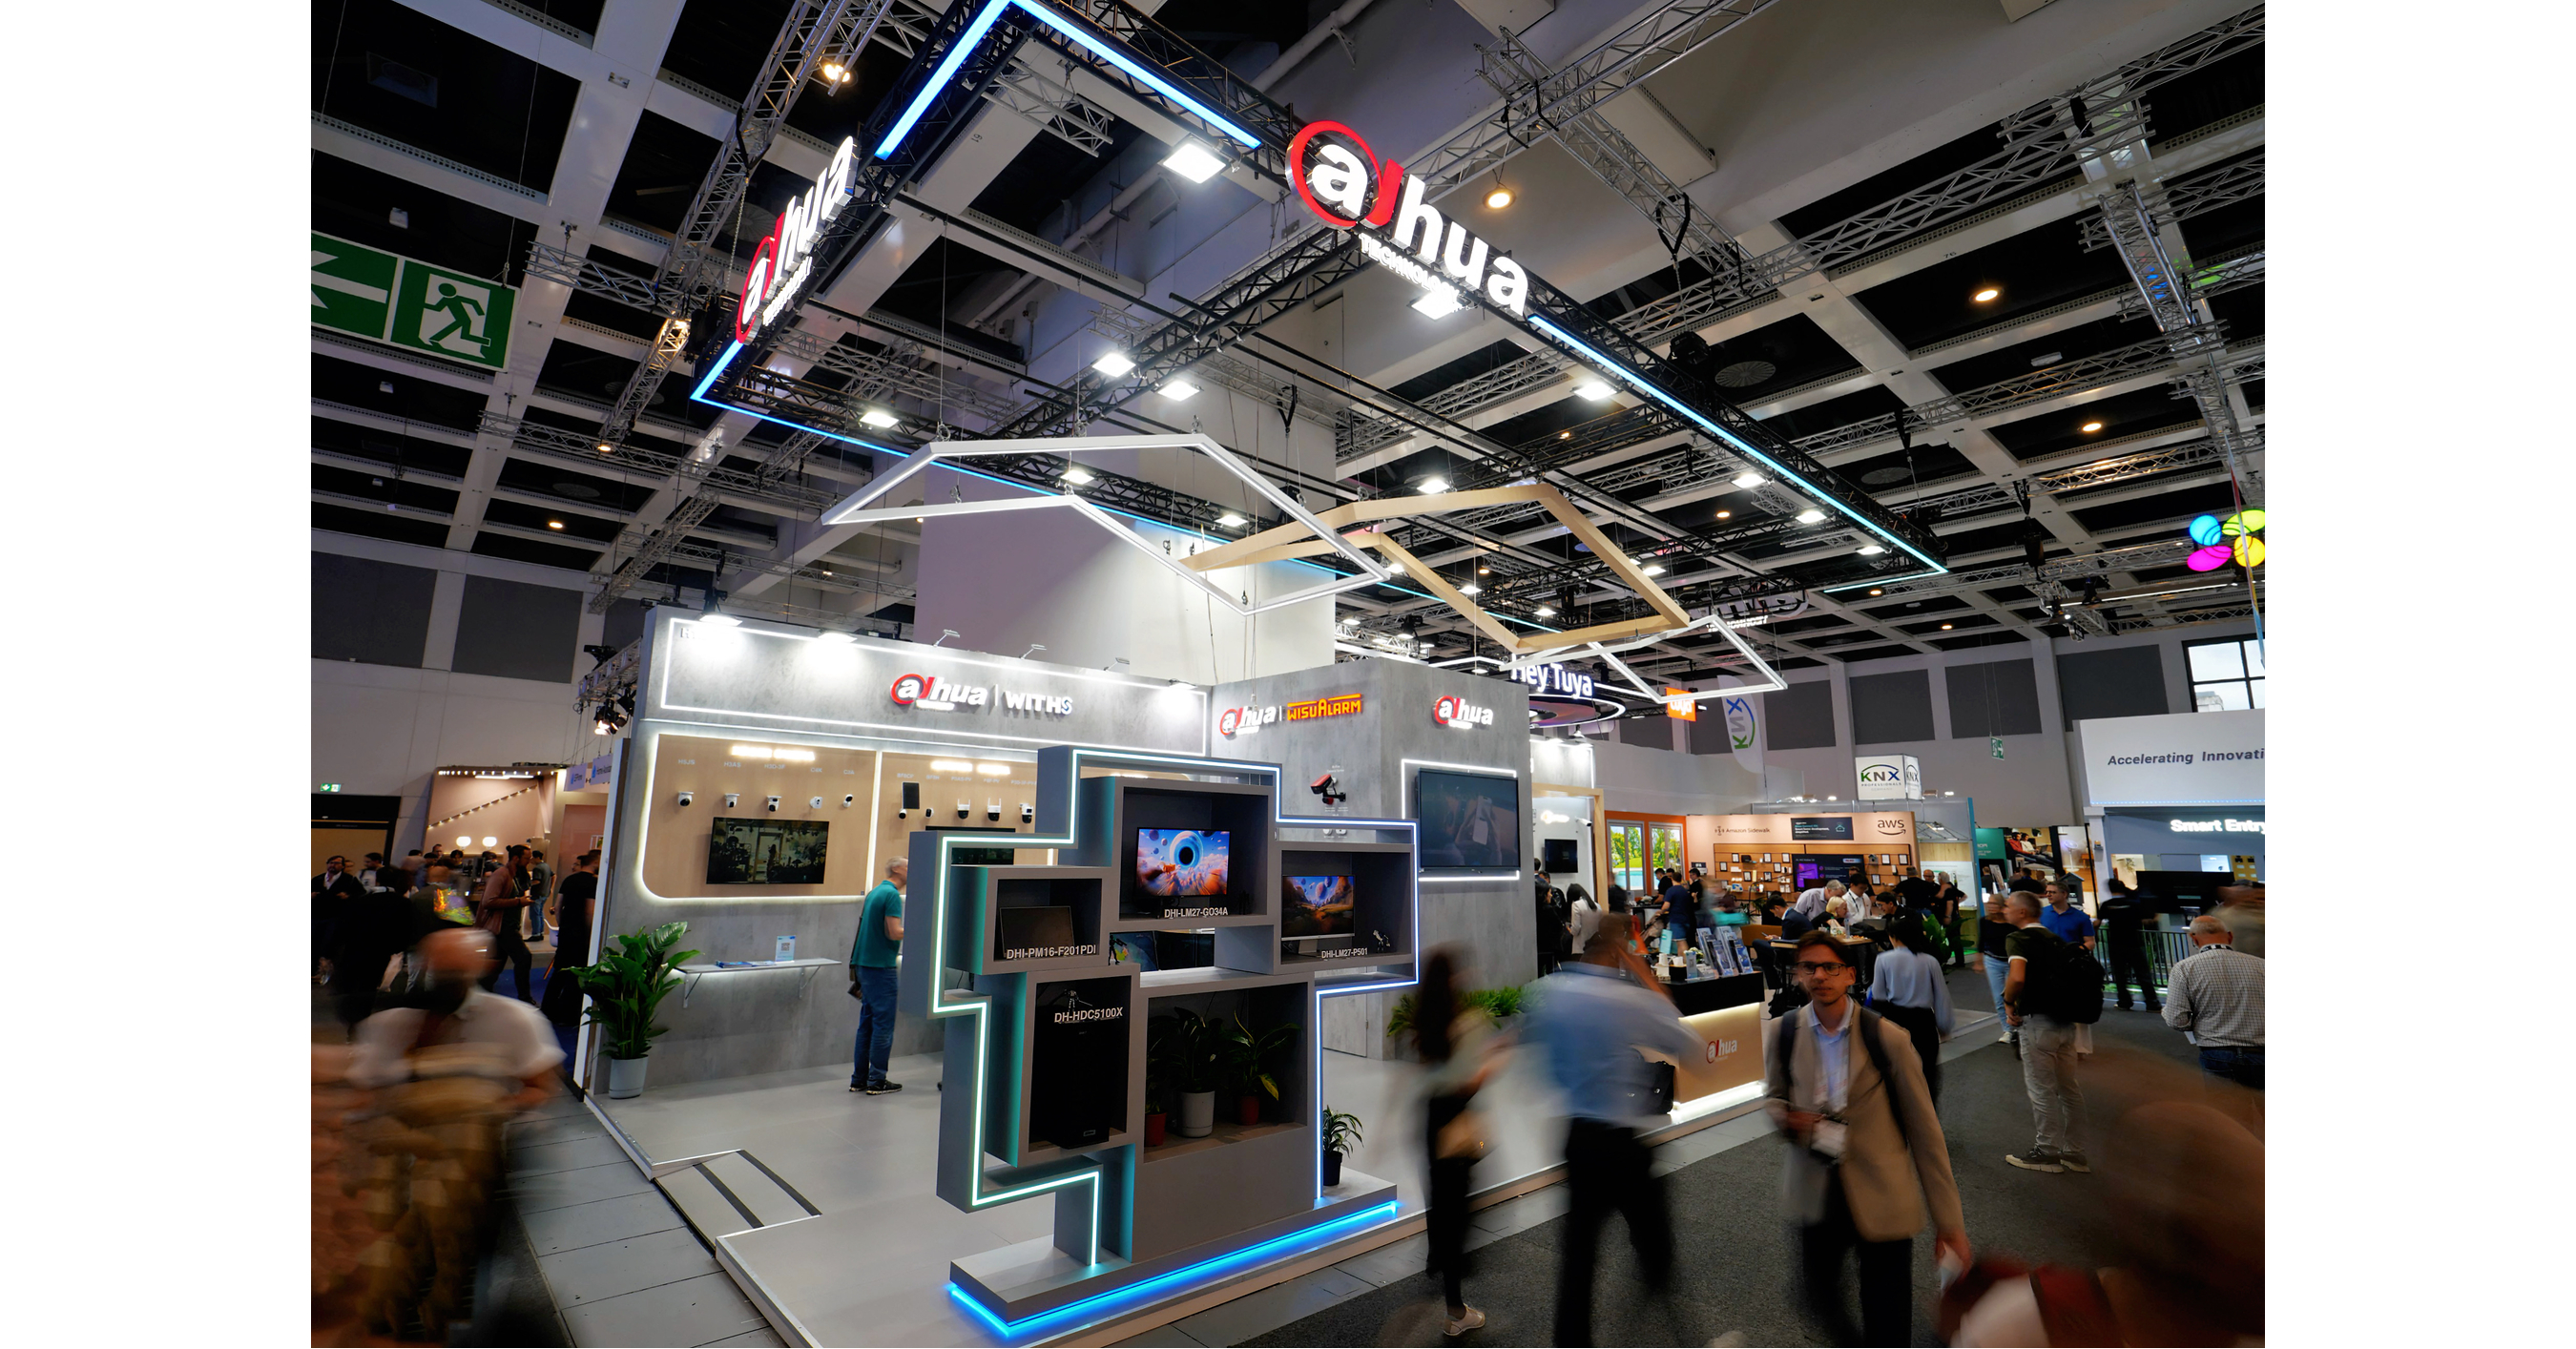
Dahua Technology unveiled an expanded AIoT product portfolio at IFA Berlin 2026, spanning wireless video surveillance, intrusion alarms, smart video intercoms, AI-assisted fire detection and gaming displays. Key launches include the WITHS wireless security range, AirShield integrated alarm platform and WizTalk IP intercom series, featuring functions such as person, vehicle, package and facial detection. The announcement signals continued product expansion beyond Dahua's core video-security business, but provides no financial guidance, sales targets or quantified commercial impact.
Analysis
This is a breadth-of-portfolio signal rather than an investable demand datapoint. Expanding from professional video security into wireless intrusion, access, fire detection and consumer displays can raise attach rates and recurring cloud/software revenue, but it also shifts Dahua into lower-switching-cost categories with entrenched channel competitors. The near-term economic benefit depends on installer adoption, cloud paid-conversion and European distributor inventory turns—not product-feature claims.
Competitive pressure is most relevant for European smart-security and access-control vendors, including ASSA ABLOY (ASSA-B.ST), Axis/Canon (7751.T), and privately held alarm incumbents, because a bundled camera-alarm-intercom offer can reduce installer complexity and win smaller commercial projects. Conversely, the move toward cloud-managed, wireless retrofits may support component demand for Wi-Fi/4G modules, image sensors and battery/solar power management, but the likely volumes are too uncertain to translate into a supplier trade.
The key risk is that European procurement restrictions, privacy scrutiny and cybersecurity qualification requirements remain a larger determinant of addressable market than feature parity. Bundling can also dilute margins if hardware is used as a loss leader to seed platform adoption. Over the next 1-3 months, there is no independently verifiable revenue catalyst; over 6-18 months, distributor wins, recurring cloud metrics and evidence of compliance acceptance would determine whether this is genuine category expansion or simply trade-show positioning.
Contrarian view: the market may overestimate the strategic value of an all-in-one AIoT stack. Customers increasingly separate physical-security hardware from monitoring software and access-control workflows to avoid vendor lock-in, meaning open integrations—not a broader proprietary product catalog—could be the decisive competitive variable.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No directional trade on this release: there is no listed Dahua ticker supplied and no disclosed pricing, order backlog, channel commitments or revenue guidance to underwrite a valuation change.
- Monitor ASSA-B.ST versus the STOXX Europe 600 over the next 1-3 months for distributor commentary on price competition in SMB access/security. Consider a tactical short only if management flags margin pressure or delayed channel orders; absent that evidence, feature-launch news alone is insufficient.
- Set an alert for EU procurement, cybersecurity-certification or privacy-rule developments affecting Chinese surveillance equipment. A material tightening would be a negative read-through for China-linked physical-security vendors and a potential relative positive for European incumbents such as ASSA-B.ST and Canon/Axis (7751.T).
- Before considering a long exposure to smart-security beneficiaries, require evidence within two earnings cycles of recurring software/cloud attach-rate growth exceeding hardware growth and stable gross margin; otherwise treat wireless bundling as potentially margin-dilutive hardware competition.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Wake up! The long bond’s up two points!
- US tech stocks tumble as investors fret over AI spending
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI in Asset Management: 2026 Statistics That Hold Up
- What is Broker Research and RMS Systems (And How to Actually Use Them)