
Disney's Lakeshore Lodge Opens July 1, 2027, with Nature-Inspired Guest Rooms Rooted in Disney Storytelling
Source: PR Newswire
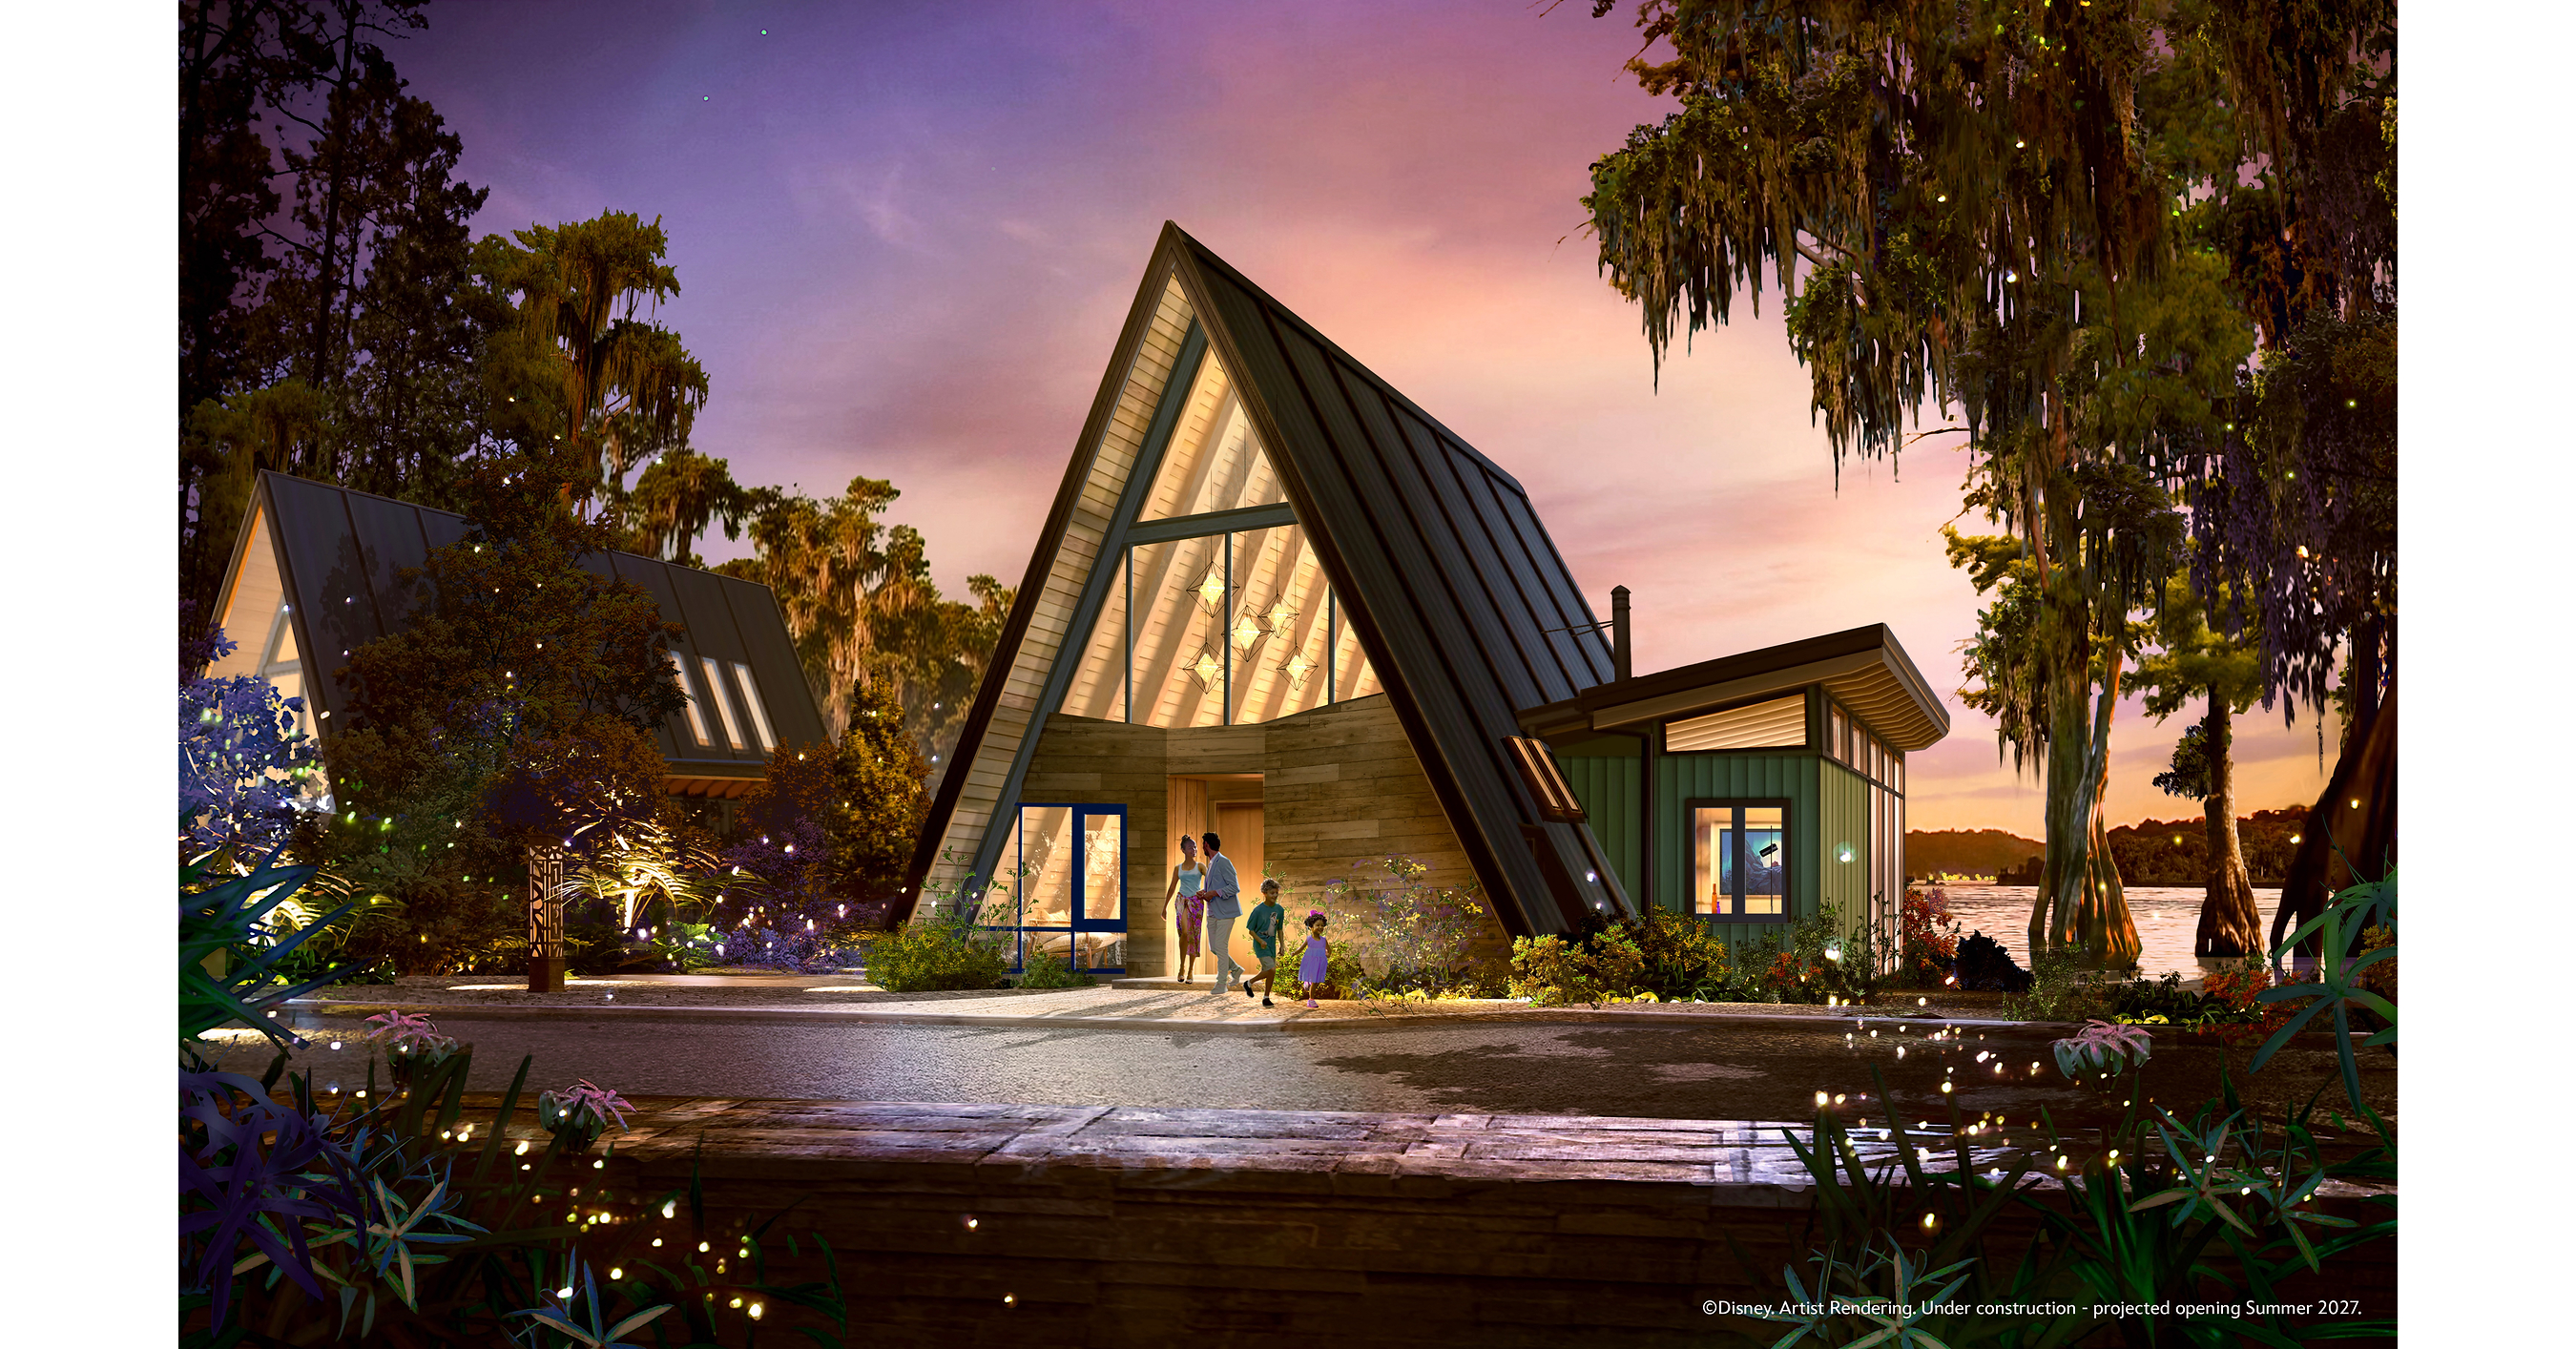
Disney Vacation Club provided a first look at accommodations for Disney’s Lakeshore Lodge, a new waterfront resort at Walt Disney World opening July 1, 2027. The resort will include 967 guest rooms (including A-frame Lake Houses with kitchen and washer/dryer), plus amenities and dining options anchored to Bay Lake. Disney Vacation Club members get first rental access starting Oct. 6, followed by annual passholders Oct. 7 and general guests Oct. 8 online/call, signaling a modest positive push for future travel demand.
Analysis
This is more a brand- and yield-management signal than a near-term earnings catalyst. A new on-property lodging asset only matters if Disney can hold a meaningful rate premium and keep occupancy high; otherwise it simply reallocates demand from existing Disney rooms and adjacent Orlando hotels. The main upside is not room-night growth in isolation, but tighter control of the guest wallet through higher-margin packaging, food/beverage, and membership conversion inside the Disney ecosystem.
The second-order winner is the DVC flywheel: fresh inventory can support direct sales of points, which is structurally more attractive than pure transient hotel demand if Disney can keep resale leakage low. The losers are offsite family hotels and some premium Orlando chains that rely on Disney-adjacent demand; the competitive risk is less about head-to-head luxury substitution and more about Disney reducing share of stay spend that would otherwise spill to the broader market. If the resort opens into a soft consumer backdrop, Disney may be forced to discount or bundle, which would compress margins and delay the payback on what is likely a heavy capital outlay.
Time horizon matters: the market reaction should be muted today because the cash-flow impact is 2027+, while the first real read-through comes at reservation launch and initial pricing in Oct. 2026. The thesis breaks if booking velocity is ordinary, if rates fail to clear existing deluxe inventory by a meaningful premium, or if Orlando leisure demand slows enough that Disney has to fill rooms with promotions. In that case, this becomes a capital deployment story with little incremental earnings leverage rather than a meaningful re-rating event.
Contrarian view: the consensus may overestimate the earnings significance of any Disney resort announcement. For DIS, the big swing factor is not aesthetics or IP storytelling; it is whether the property can monetize scarcity in a way that expands DVC economics instead of cannibalizing other Disney lodging. Without evidence of premium pricing, this is more of a qualitative brand win than a quantitative EPS driver.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade: DIS impact is too long-dated for a clean catalyst, and the current announcement should be treated as low-confidence signal rather than earnings revision.
- Set an alert for Oct. 2026 reservation pricing and booking pace; if nightly rates and package mix clear comparable Disney deluxe inventory by 5-10%+, consider adding a tactical long DIS position for the 1-3 month follow-through.
- If booking data disappoints or discounts appear within the first 30-60 days of sales, fade the move with a short DIS trade into any strength; that would imply the asset is cannibalizing existing inventory rather than adding pricing power.
- Watch ORL leisure proxies and hotel REITs with Disney exposure; a stronger-than-expected launch would be mildly negative for offsite family-lodging demand, while weak demand would confirm the market is already saturated.
- For options-oriented accounts, a small DIS Jan-2028 call spread on a pullback is the cleaner expression than stock, but only if later booking data supports premium positioning; otherwise the risk/reward is too dependent on 2027 execution.
More News
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Pokémon card values are soaring. What collectors should know before buying or selling
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- How Supreme Court justices are leaning in major 401(k) case over private funds and underperformance
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them